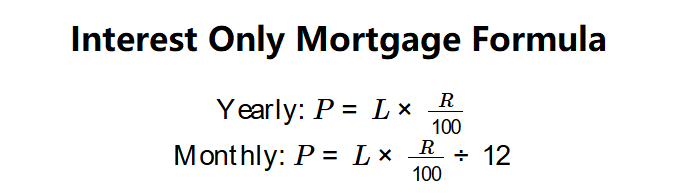The Basic Math, Straight Up
Calculating your interest-only mortgage payment is simpler than most people think, but it's also easier to get wrong if you're not careful about which numbers you're pulling from. The core formula is just principal multiplied by the monthly interest rate. That's it. You take your outstanding loan balance, divide your annual rate by twelve, and multiply those two figures together. No amortization tables, no principal reduction, just raw interest for that month. I worked through this calculation for hundreds of clients over the years, and the number one mistake I saw wasn't in the math itself. It was in the input data. People would grab their current balance from a statement that had already been updated with late fees or adjustments, then plug in a rate from an old document before their adjustment period kicked in. The payment they calculated looked right on paper but was off by hundreds of dollars in practice. Always verify both the principal figure and the applicable rate against the most recent monthly statement before you do anything with the formula.
How to Work Out Interest Only Mortgage Payments Step by Step
Start by pulling your current outstanding principal balance from your latest mortgage statement. Don't use an estimate or a number you remember from last quarter. Interest-only periods can drag on for five, ten, even fifteen years depending on the loan structure, and the balance on your original closing documents may not reflect any changes that happened after that. Next, find your annual interest rate. This should be listed right on the statement. If you're dealing with an adjustable-rate mortgage, the rate on your document might be the current rate or it might be the introductory rate from when you closed. Check whether there have been any recent adjustments and confirm which rate is actually being applied to your payments right now. I once had a borrower who was paying at a fully indexed rate that was 2.5 percentage points higher than what her statement showed as the "contract rate." She had no idea because the lender wasn't calling it out anywhere on her monthly breakdown. Convert the annual rate to a monthly rate by dividing by twelve. If your rate is 6.5 percent, that's 0.065 divided by 12, which equals approximately 0.005417. Keep as many decimal places as your calculator allows. Rounding too early introduces error that compounds over time, especially on larger balances where even a fraction of a percent matters.
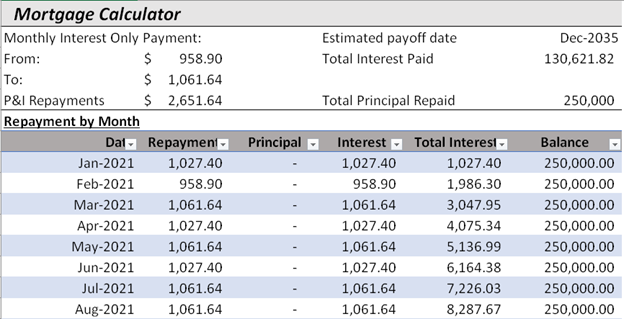
Multiply your principal balance by the monthly rate. If you owe $400,000 at 6.5 percent, your monthly payment works out to about $2,166.67. That's your interest-only payment for that month. It stays the same only if your rate doesn't change and no additional charges get added to your balance. With an adjustable-rate loan, this number will shift whenever the index adjusts. With a fixed-rate interest-only loan, it stays locked until the interest-only period ends and the amortization kicks in.
Get the Full Details
What Actually Happens After the Interest-Only Period Ends
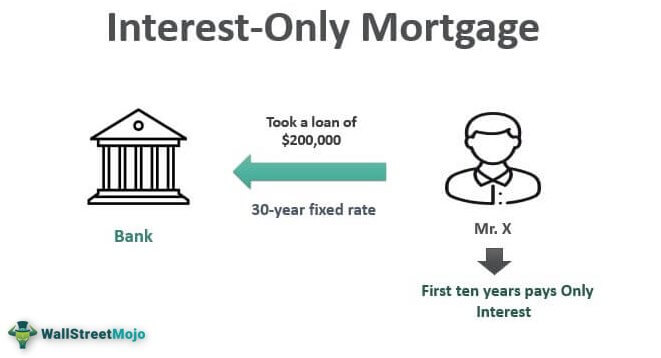
This is where most people get blindsided. When your interest-only period expires, your payment doesn't just stay the same. The loan typically starts amortizing over the remaining term, which means you're now paying both principal and interest on the full outstanding balance. On a $400,000 loan at 6.5 percent with a 30-year term, your payment could jump from roughly $2,167 to about $2,528. That's a 17 percent increase for no reason other than the loan structure changing. I've seen borrowers who planned to sell before the conversion hit and were perfectly fine with the temporary payment. Then life happened, the market slowed, and they were stuck making a payment they couldn't afford for years. Another thing nobody tells you upfront: some interest-only loans have a negative amortization feature built in. If your monthly payment doesn't cover the full interest due that month, the unpaid interest gets added to your principal balance. The loan grows instead of staying flat. This is more common with payment-option adjustable-rate mortgages that existed in droves before the 2008 crash, but they still pop up in certain subprime products. Check your loan documents for a clause about unpaid interest being capitalized. If it's there, your payment calculation is more complicated than the simple formula above because your principal changes every month even if you make all your payments on time.
The Numbers That Actually Matter Beyond the Monthly Payment
Your monthly interest payment is only one piece of the puzzle. Property taxes and homeowners insurance are almost always escrowed into your mortgage payment whether you realize it or not. A $2,167 interest payment might become a $3,200 total payment once you add in taxes and insurance. I had a client who budgeted strictly around her interest-only payment and was caught completely off guard when her escrow shortage came due after the servicer did an annual review and recalculated the tax and insurance portions based on rising rates in her area. The shortfall was $4,000 in a single payment. Lender fees and servicer charges are another hidden cost. Some interest-only mortgages carry monthly servicing fees of $10 to $25 that don't get itemized clearly on your statement. Over a ten-year interest-only period, that's $1,200 to $3,000 you're paying for something that does absolutely nothing for you. Review your statements line by line every year and flag anything that looks like a recurring administrative charge. You can sometimes get these waived by calling the servicer, but they won't remove themselves.
When This Strategy Actually Makes Sense and When It Doesn't
Interest-only mortgages aren't inherently bad products. They make sense for people who have a clear exit strategy or a defined timeline. A fix-and-flip investor who knows the property will sell in eighteen months benefits from lower monthly carrying costs. A professional who expects a significant bonus or promotion within the interest-only window can use the lower payment to maintain cash flow while saving aggressively for the upcoming payment increase. The key is having a real plan, not just hoping things work out. The strategy fails for people who treat the low payment as permanent income relief. I've reviewed enough refinancing applications from borrowers trapped in this situation to know that the pattern is predictable. People buy at the low payment, assume it will stay low, spend the difference on lifestyle upgrades, and then hit the amortization cliff with no equity cushion and no savings buffer. By the time they realize what's happening, they're either underwater on the property or dependent on a refinance that won't qualify because their debt-to-income ratio has drifted too high from years of unchecked spending.

Practical Tips for Managing the Calculation Ongoing
Set up a spreadsheet or use a simple budgeting tool to recalculate your payment every time your rate adjusts. Don't rely on your servicer's numbers alone. They have incentives to present information in the most favorable light for retention, not for your financial clarity. Cross-reference their statements with the actual terms in your original loan documents. If the payment they're charging doesn't match the calculation, call them and ask for a written explanation. Most of the time it's a simple discrepancy they'll correct within a few business days. A small number of times, it's a systemic error that has been accumulating for months, and catching it early saves you real money. If you're working out interest only mortgage payments as part of a broader financial plan, factor in the balloon payment scenario. Some interest-only loans require the full principal to be paid at the end of the term rather than transitioning into a traditional amortizing mortgage. This means you need a lump sum ready or a refinancing plan that's already in motion before the due date arrives. Missing this deadline can trigger default clauses that are far more severe than a simple payment increase. The calculation itself takes about two minutes once you know where to find your numbers. The planning around what happens after that calculation stays relevant for years, and that's where the real work lies.