Getting Straight to the Point on Small Business Bookkeeping
I've spent more years than I care to count reconciling general ledgers for businesses that treat their accounting as an afterthought. Most of them are bleeding money without knowing it because they never look past the monthly P&L. Here is what actually moves the needle when you need to set up a functional system quickly, and I mean genuinely quick — not the kind of quick that requires a complete redo three months later. The foundation is chart of accounts structure, not software choice. I recently worked with a client who had switched between three different platforms in two years. Every time, the problem wasn't the tool. It was that their account grouping didn't map to how they tracked profitability by division. They were running five product lines through a single revenue account. Fixing the structure took about 45 minutes. Sorting out the mess that had accumulated from six quarters of mismatched entries took two full days. I still have the reconciliation spreadsheets from that job sitting in a shared drive.
Accounting Tips Quick That Actually Work in Practice
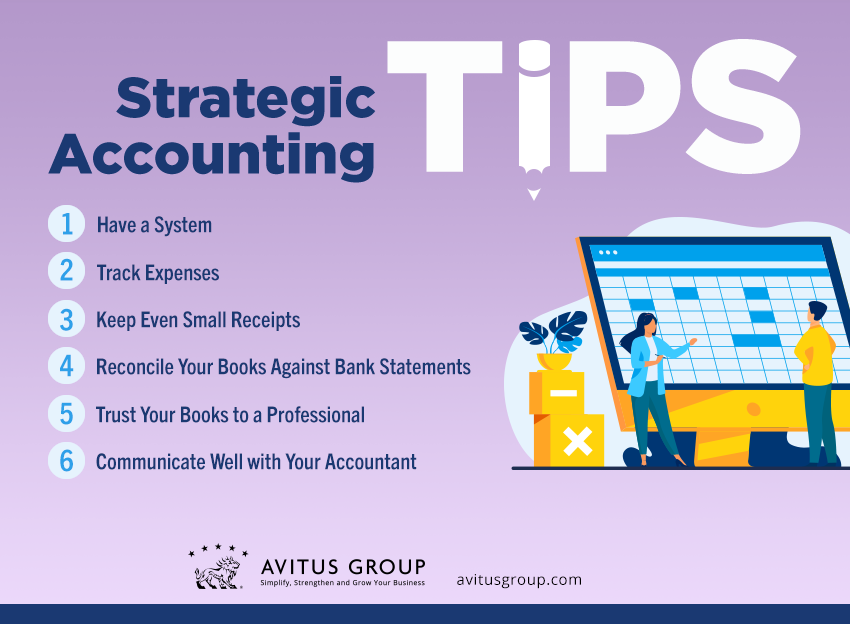
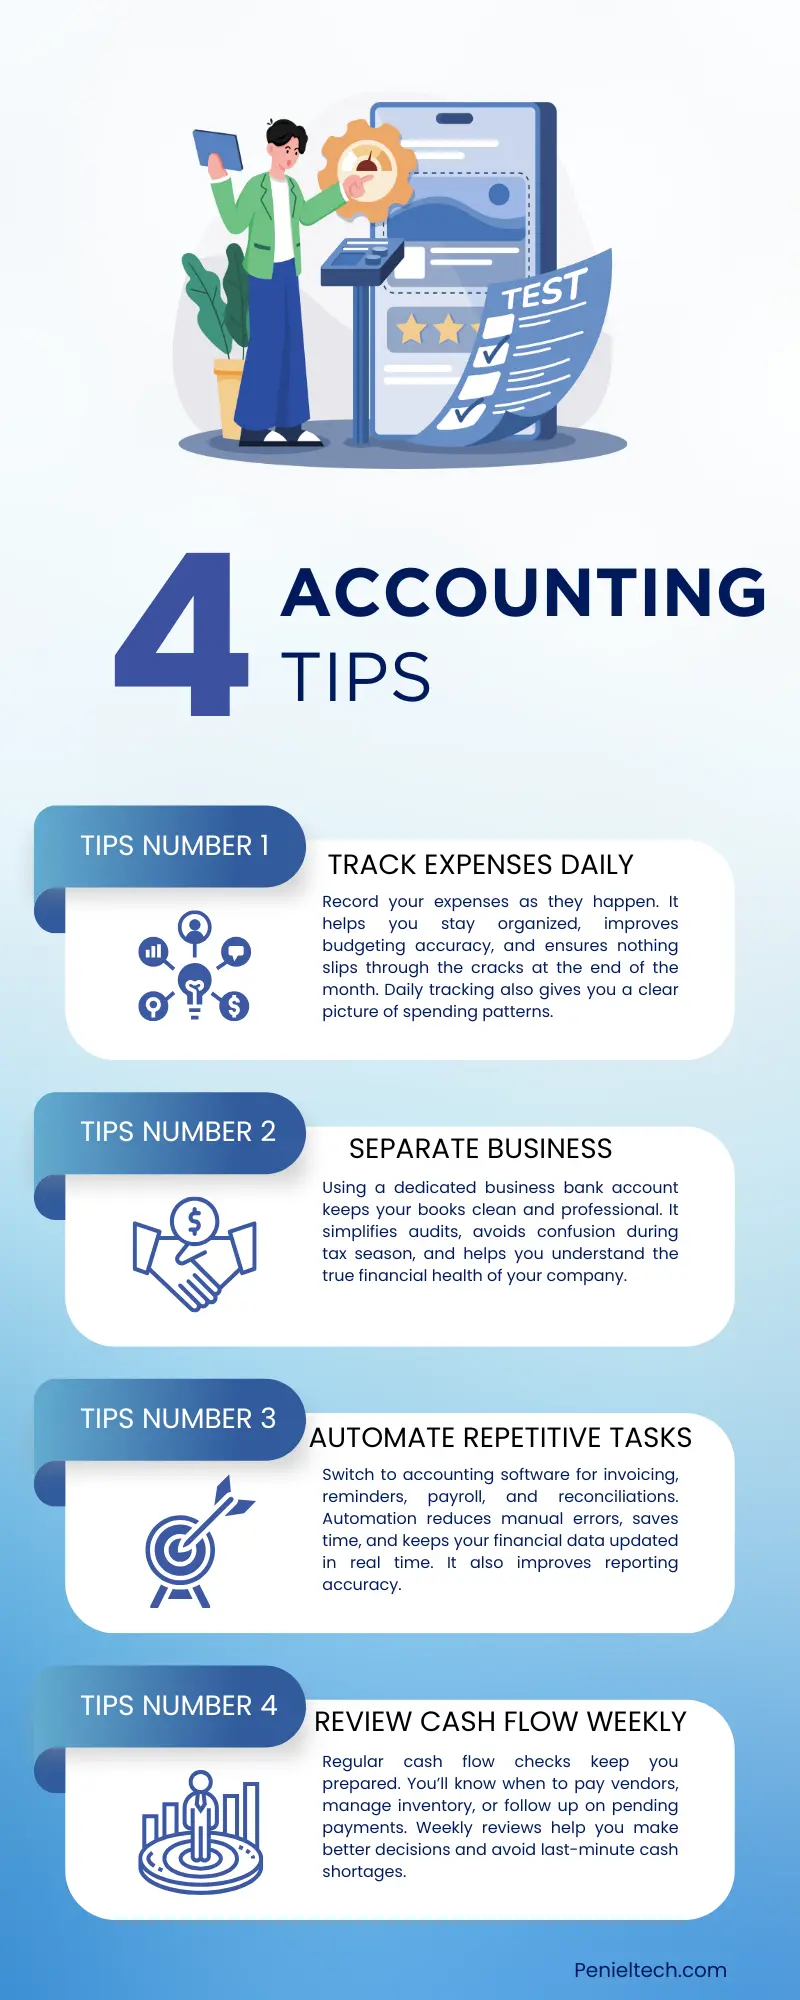
Start every month with bank and credit card feeds reconciled to the penny before you touch anything else. This isn't advice you can skip. The moment you let discrepancies pile up beyond thirty days, you lose the ability to spot the category errors and duplicate charges that cause most small business tax headaches. Most people wait until they get the annual tax notice to figure things out. By then the gap between recorded income and actual deposited income has usually grown large enough to require a forensic walk-through of three months of transaction history. Moving to categorization rules now saves hours later. Set up recurring transaction rules for your top ten recurring expenses — software subscriptions, rent, utilities, insurance premiums. When you do this, the automated categorization in your system handles roughly sixty percent of your monthly entries without human intervention. The remaining forty percent, the ones that need actual judgment, is where mistakes happen. That's the part you need to review manually every single month. Separate owner draws from business expenses immediately. This is the most common error I see. Personal purchases routed through the business account, even occasionally, create classification problems that make end-of-year adjustments messy. A sole proprietor or single-member LLC owner thinking of a purchase as "taking money out" doesn't change the fact that the business paid for it. If it's a business expense with a valid deduction, document it with the receipt and categorize it properly. If it's a personal draw, route it through an owner's equity account. The tax treatment is different. Mixing them up will cost you more in corrections than the occasional deductible expense is worth.
Here is something most beginners miss. Accrual versus cash basis accounting isn't just a tax election. It fundamentally changes how you read your financial statements. Under cash basis, your revenue looks nothing like your actual sales activity because invoices sit unpaid and you have no record of work completed but not yet collected. If you're on a cash system and trying to understand whether you can afford to hire someone, you're working with incomplete data. Switching to accrual accounting for internal reporting purposes costs nothing and gives you visibility into receivables and payables that cash basis completely obscures. Many smaller firms operate under cash basis for tax filings while running an accrual-based internal tracker alongside it. The dual setup adds maybe two hours per month of bookkeeping work, but it eliminates guessing about whether you actually have enough collected revenue to cover upcoming obligations. Another thing that catches people off guard. The profit and loss statement tells you nothing about whether you can pay your bills next week. You need to maintain a separate cash flow forecast updated weekly. I use a simple rolling fourteen-day projection for every client. It shows expected deposits, scheduled outgoing payments, and any known irregular expenses coming up. This takes about twenty minutes each Friday and has prevented more missed payments than any software feature ever has. The biggest limitation with quick setup methods is that they depend entirely on consistent input. No system — not QuickBooks, not Xero, not a spreadsheet — will produce accurate reports if the underlying transactions are entered incorrectly or inconsistently. Automated bank feeds reduce this risk but don't eliminate it. Bank import files sometimes map transactions to wrong categories, especially for newer vendors or unusual charge types. Monthly review of auto-categorized entries catches these errors. Skipping that review means you're trusting the automation to do something it wasn't designed to do perfectly.
Get the Full Details

The Edge Case That Teaches the Most
There is one scenario where quick methods break down completely, and I learned this the hard way. Multi-currency operations. A client of mine was invoicing Canadian clients in CAD while holding their primary operating account in USD. The exchange rate fluctuation between the invoice date and the payment date created realized gains and losses that didn't appear anywhere in their standard reporting. They were losing money on every transaction where the dollar strengthened between invoice and collection. Their P&L looked fine because the revenue line showed the full invoiced amount. The loss was hidden in the bank account reconciliation, appearing only as a small unexplained discrepancy between the recorded deposit and the invoice total. The workaround was enabling multi-currency tracking in their accounting platform and setting up a foreign exchange gain/loss account. Each transaction needed to be recorded at the exchange rate on the transaction date. When payment arrived, the system calculates the difference between the recorded rate and the actual deposit rate, posting the variance to the FX account automatically. This added about thirty minutes of setup time and required a minor adjustment to how they recorded customer invoices. The ongoing maintenance is negligible — the system handles the conversion logic. But without this adjustment, their financial statements were systematically understating the true cost of doing business internationally. If you run a business with any cross-border activity, this adjustment should be part of your initial setup, not an afterthought. The tax implications of FX gains and losses also differ by jurisdiction, so consult a CPA if you're dealing with significant currency exposure. The quick setup framework I described above works well for straightforward domestic operations. It doesn't cover everything, but it covers the majority of what small business owners actually need on a day-to-day basis. Beyond that, you need specialized guidance tailored to your specific situation.
The tools exist to keep your books current with minimal friction. The bottleneck is always discipline, not technology. Spend twenty minutes each Friday on the cash flow forecast. Reconcile to the penny every month. Review auto-categorized transactions. Keep owner draws and business expenses strictly separated. That routine handles the vast majority of what goes wrong with small business accounting. Everything else is optimization work for when you have time for it.