What You Need to Know About the ACA Basics Exam
The Affordable Care Act Basics Exam is a short assessment used by health insurance carriers and brokers during certification or onboarding. It covers the core provisions of the ACA—individual mandate history, subsidies, Medicaid expansion, essential health benefits, and marketplaces. You can expect roughly 20 to 30 multiple-choice questions. Passing score is usually 70% or 80%, depending on the organization administering it. I have seen people search for this exact phrase constantly. The honest answer is that there is no single official document called "Affordable Care Act Basics Exam Answers." Different programs use different exams. The Department of Health and Human Services does not publish a master answer key. The test varies by state, by carrier, and by the training platform you are using. If you are looking for study materials, the real sources are the official HHS website, your state's Medicaid agency, and the Marketplace Enrollment Resource Center. Those give you the actual regulations. Study guides and practice quizzes circulate on educational sites, but they are not official. I learned this the hard way during a certification cycle in 2019 when I relied on a third-party quiz site that had outdated information about the individual mandate penalty being zero after the Tax Cuts and Jobs Act change. My answers were technically correct for an older version of the law. I failed the first attempt because the exam expected the post-2019 penalty structure.
How the Exam Actually Works
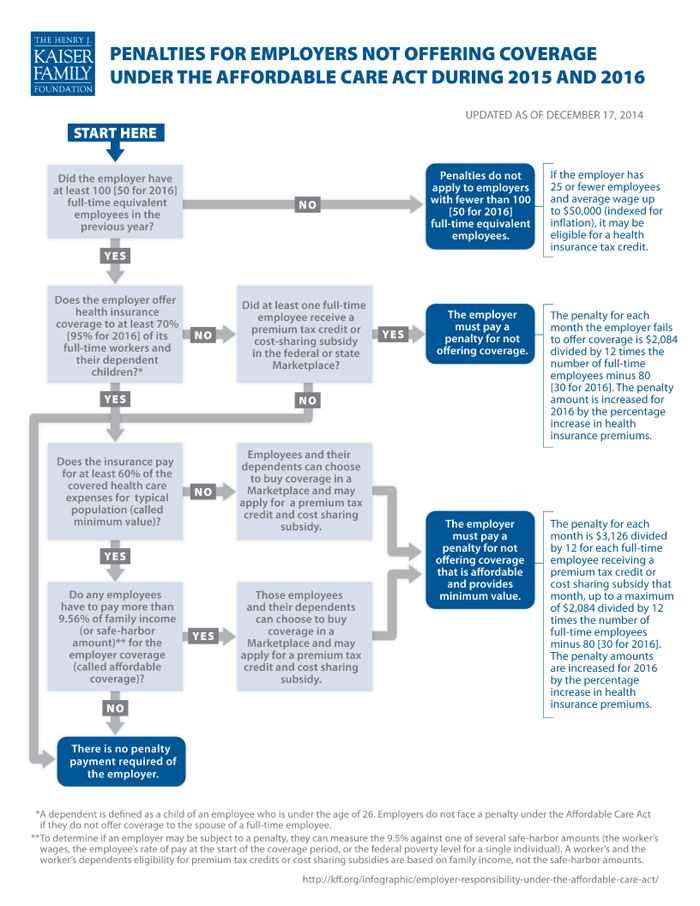
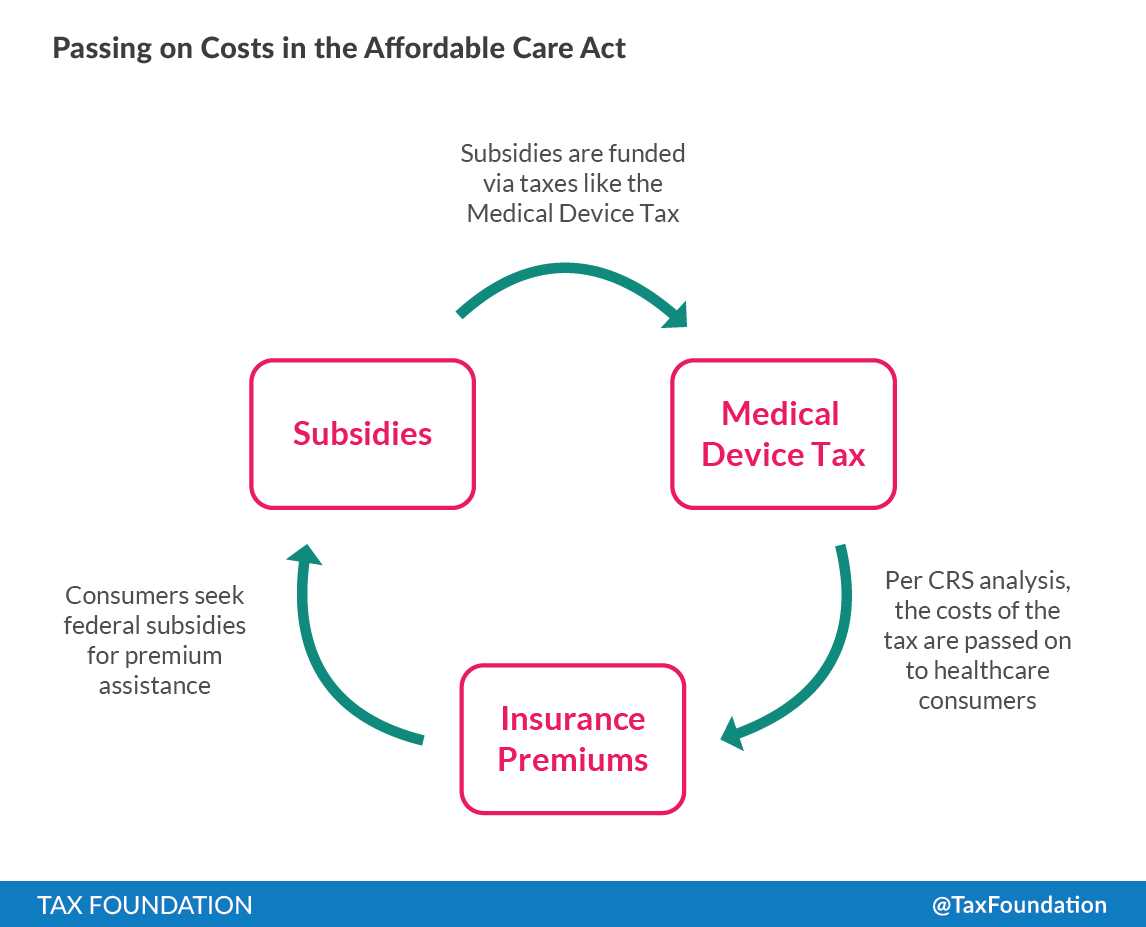
Most ACA basics exams are built around the four pillars of the law. The individual mandate, which was effectively neutered starting in 2019 when the federal penalty dropped to zero. Subsidies, including premium tax credits and cost-sharing reductions. Medicaid expansion, which varies by state. And the marketplace structure, which includes federally facilitated exchanges and state-based exchanges. You need to understand how premium tax credits are calculated. They are based on household income relative to the federal poverty level and apply only to silver plans. Cost-sharing reductions are only available to people who qualify for both premium tax credits and silver plan coverage. That detail trips up a lot of people taking the exam. The essential health benefits categories are ten specific areas. Mental health and substance use disorders count as one category. Preventive services must be covered without cost-sharing for most plans. Here is something the basic study materials often miss. The distinction between a qualified health plan and any other insurance product matters more than you might think. Exchanges only sell QHPs. If someone asks whether an employer-sponsored plan is an exchange plan, the answer is no. These things are separate tracks. Employers with 50 or more full-time equivalent employees face the employer shared responsibility provisions, also known as the employer mandate. That is a completely different rule set than the individual side of the law.
Common Pitfalls People Hit
I have watched brokers and agents lose points on questions that sound straightforward but contain a subtle trap. One common one involves the definition of a household. For subsidy purposes, the relevant unit is the tax household, not just the people living under one roof. A dependent who files a separate tax return changes the entire subsidy calculation. Another trap is the timing of coverage changes. The general open enrollment period runs from November 1 to December 15. But special enrollment periods exist for qualifying life events, and the list is long. Marriage, birth, loss of other coverage, moving to a new service area, and changes in income that affect subsidy eligibility all qualify. Here is a specific edge case I ran into. A client moved mid-month from one county to another. The local exchange rules treated the two counties as different market rating areas. The move qualified for a special enrollment period, but the agent on the other end refused to process it because the client's new address was still pending utility activation. I solved it by having the client provide a lease agreement and a utility bill under the new name. The exchange accepted those documents and activated coverage with a retroactive effective date of the move. The exam will ask about what counts as proof of residency. Be ready to cite the specific document types.
Get the Full Details
How to Actually Pass This Exam
Do not memorize answer keys. They will not help you because different platforms use different questions. Study the underlying regulations. Read the HHS guide on the individual mandate changes. Review the IRS publications about premium tax credits. Look at your state's Medicaid eligibility thresholds. That last one is critical because Medicaid expansion states and non-expansion states have wildly different income cutoffs. Practice with question banks that are current. Anything published before 2020 is likely inaccurate on the penalty issue. Focus on understanding why an answer is wrong, not just which option is correct. When I built a study routine around this, I spent more time on the subsidy formulas than on the general provisions. The math checks out roughly like this: your household income divided by the federal poverty level determines your tier. Premium tax credits cap your contribution at a percentage of income, and that percentage rises as income rises. The exact tables are in IRS publication 974. Another thing nobody tells you about these exams. They often include scenario questions where you have to pick the best course of action, not just the technically correct fact. You might be asked what to do when a caller's income dropped unexpectedly and they want to change their plan mid-year. The answer usually involves checking whether the income change triggers a special enrollment period and then recalculating subsidy eligibility. These questions test your ability to apply rules, not just recall them.
What the Exam Does Not Cover
It is worth noting the limits. The ACA basics exam does not go deep into employer-side compliance. It does not cover the SHOP marketplace in detail unless your certification path requires it. It generally skips over the intricacies of grandfathered plans and the transition rules that applied during the early implementation years. If your role involves advising self-insured employers on minimum value standards, you will need additional training beyond this exam. The exam also does not test state-specific nuances that go beyond the federal floor. Some states have expanded Medicaid further than the federal requirement, imposed their own individual mandates, or created their own exchange structures. If you work in California, Colorado, or Massachusetts, for example, the state-level rules add layers on top of the federal framework. A generic practice test will not prepare you for those variations.
Final Notes
I have taken and reviewed enough of these assessments to know that the ones that look easiest are usually the ones where people make careless mistakes. They rush through the subsidy questions and pick the answer that sounds right without checking the income thresholds. They confuse cost-sharing reductions with premium tax credits. They forget that the employer mandate threshold is measured in full-time equivalents, not just headcount. Take your time. Read each question twice. When you see a number in the question, write down the relevant threshold and compare it to the scenario. The exam is designed to be passable for anyone who actually studied the material, but it punishes people who skim. There is no shortcut around reading the actual regulations. The search results you find online are mostly recycled content from three or four websites. The original sources are government domains. Go straight to them. If you are preparing for this exam because you need it for a job or certification, invest a few hours in the HHS Marketplace resources and the IRS guidance. That will give you a better foundation than any answer key you can download. The knowledge sticks when you understand the logic behind the rules, not when you memorize a list of correct options. I have seen people pass on the first try after two days of focused study using official sources. I have also seen people fail after weeks of studying because they used outdated materials. The difference is almost always the quality of the source, not the amount of time spent.
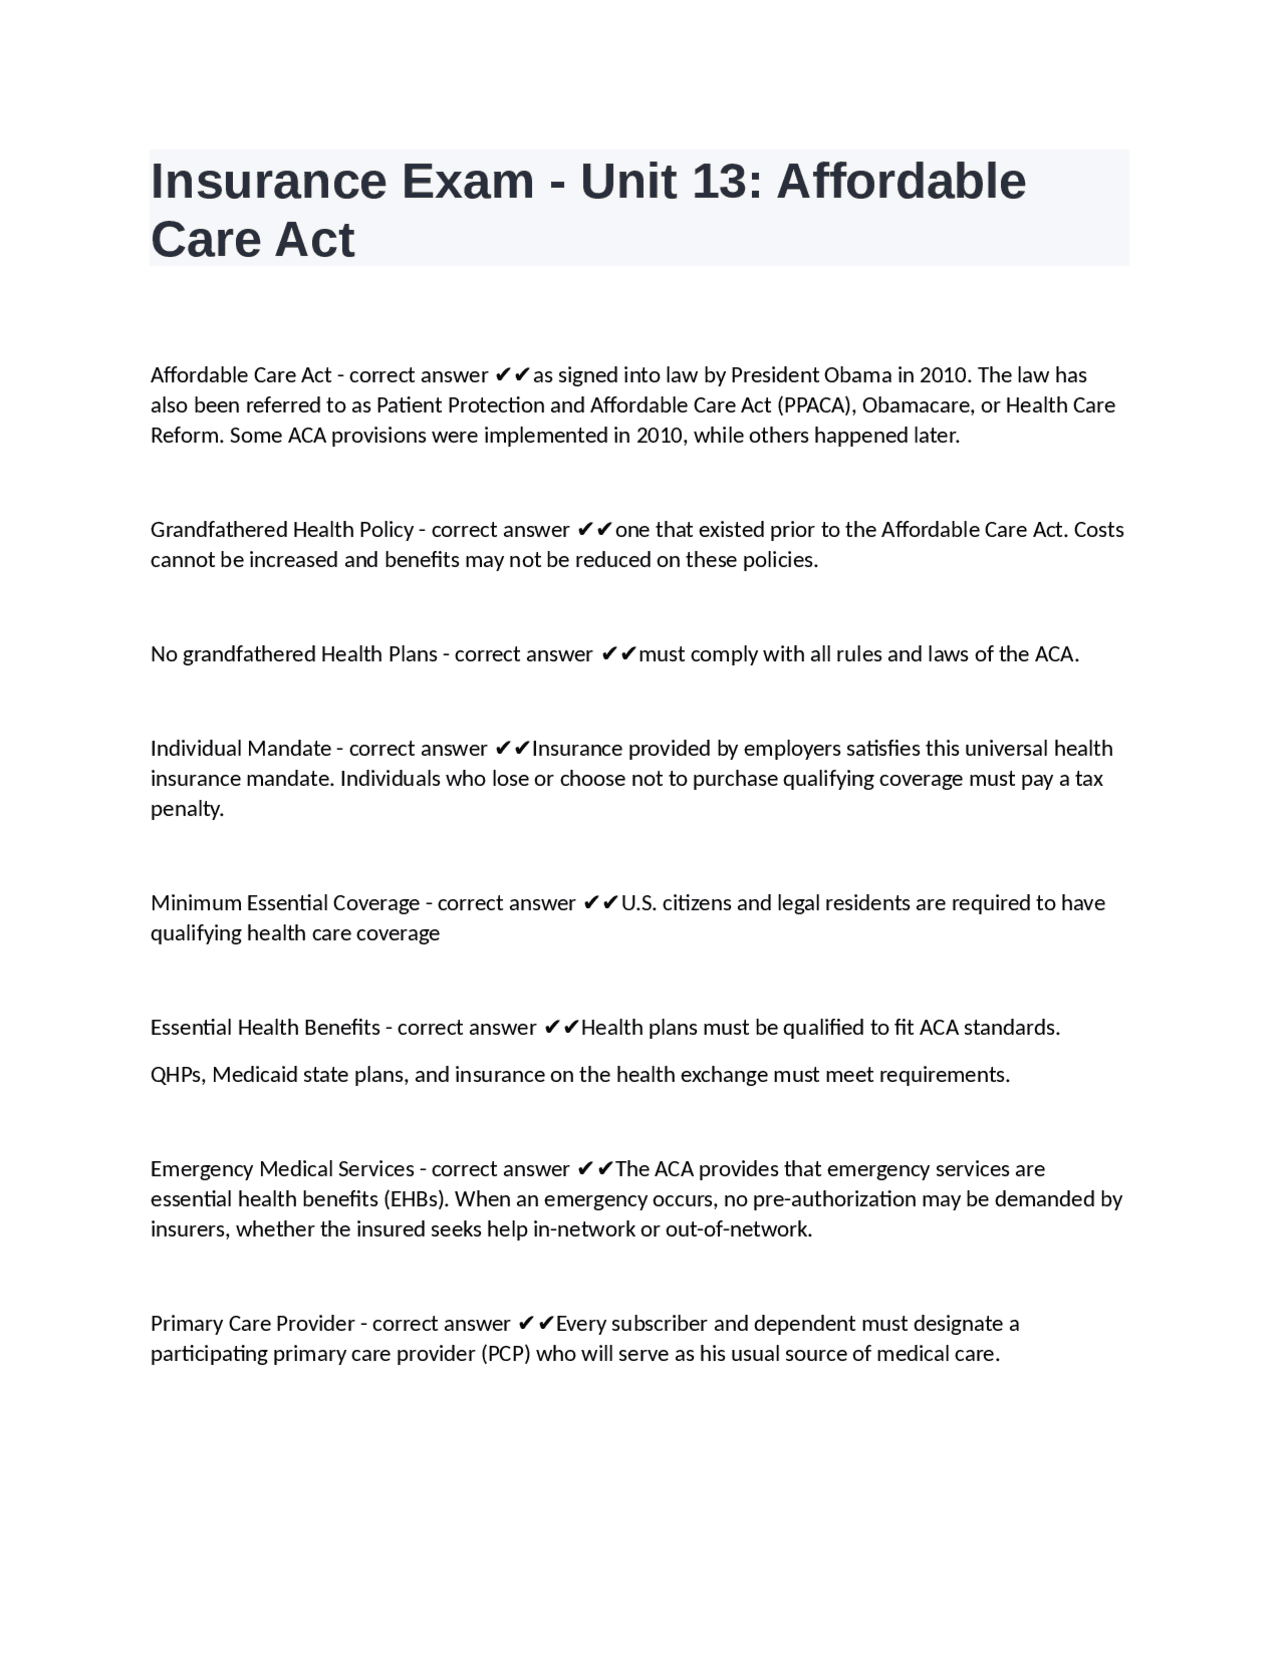
The Affordable Care Act is still changing in some respects. Court cases and regulatory adjustments happen periodically. Make sure your study materials reflect the current law. If a practice question mentions a $695 penalty or discusses the mandate as an enforceable federal requirement, that material is obsolete. The penalty was reduced to zero starting in 2019. Anything that says otherwise is wrong, and the exam will not accept it. I do not have a direct download link for an answer key because no legitimate one exists. What I can tell you is that the most efficient path is to use the free resources from HHS and your state's exchange portal. Work through the sample questions they provide. Take notes on the areas where you hesitate. Come back to those topics with the official regulation text. That process took me about 10 hours total for a standard ACA basics exam, and I passed on the first attempt. Your mileage will vary depending on how familiar you already are with health insurance concepts, but the method is reliable. The exam itself is not difficult if you approach it correctly. It is a baseline competency test, not a trick exam. It wants to confirm that you understand the major provisions and can apply them in common scenarios. Focus your energy on those two things. Everything else is noise.
One last thing from experience. When you take the exam, flag the questions you are unsure about and move on. Come back to them at the end. Many people get stuck on a single tricky scenario and waste time that would be better spent confirming answers they already know. The scoring usually does not penalize you for skipping around. Use that flexibility to your advantage. Finish the questions you can answer quickly, then return to the harder ones with fresh eyes. It is a simple strategy that most people overlook under pressure.