What You Need to Know About Balloon Payment Amortization
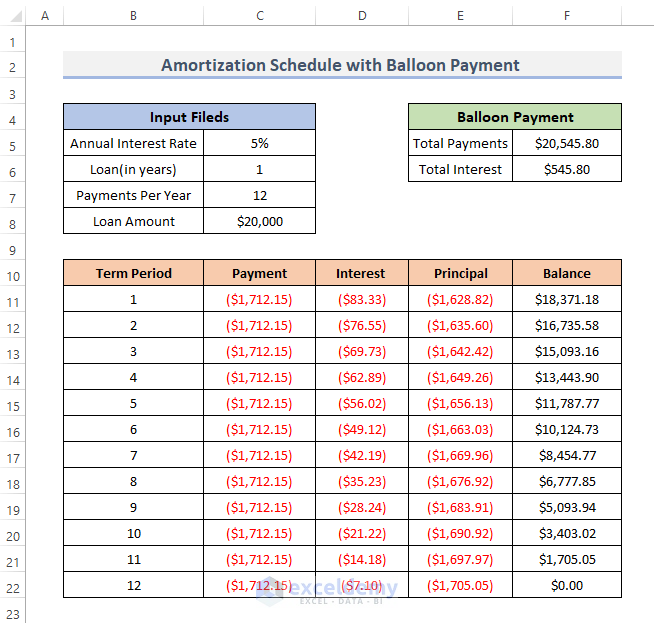
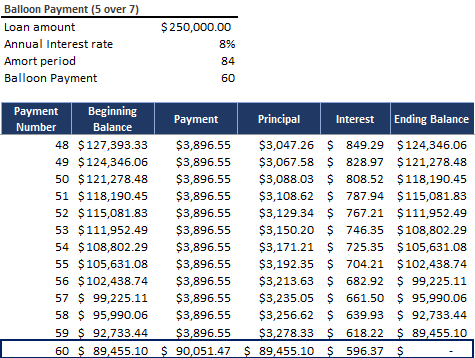
An amortization chart with balloon shows a loan structure where most of the principal stays unpaid until a large final payment. The monthly amounts look normal for years, then everything collides at the end. I built a few of these for clients who wanted lower monthly outflows on commercial real estate deals, and it's not as straightforward as most calculators make it look. The basic mechanics are simple enough. You take the full loan amount, apply your interest rate, figure what the monthly payment would be if the loan amortized normally over the full term, then strip out the principal portion so that only interest covers the monthly payments. The remaining balance becomes the balloon. That's the easy part.
Building an Amortization Chart With Balloon
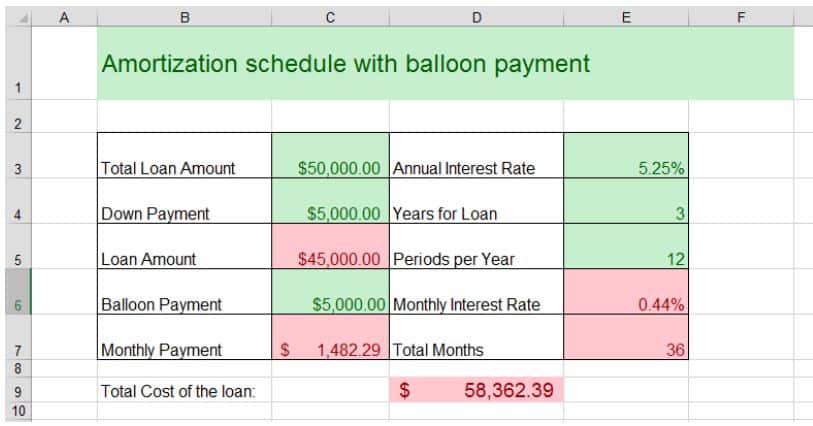
Most spreadsheets I've seen do this wrong because they don't account for payment timing and compounding frequency properly. Here's the practical approach I use. Start with the full loan amount and the total amortization period. Say you have a $500,000 loan at 6.5% annual interest with a 30-year amortization schedule but only a 7-year balloon. The monthly payment calculation uses the standard annuity formula: payment equals the principal times the monthly rate divided by one minus one plus the monthly rate raised to the negative number of total payments. That gives you the payment as if the loan would fully amortize over thirty years. Run the amortization schedule month by month for only seven years. Each month, multiply the remaining balance by the monthly rate to get the interest portion, subtract that from the payment to find the principal paid down that month, and reduce the balance. After eighty-four payments, whatever remains on the balance sheet is your balloon payment.
In this example, the monthly payment works out to roughly three thousand one hundred forty dollars. After seven years, the remaining balance sits around three hundred eighty thousand dollars. That's the balloon. Most people get tripped up here because they confuse the balloon with a penalty fee. It's not a fee. It's the unpaid principal that was never scheduled to be paid off during the regular term.
Get the Full Details
Common Pitfalls I've Seen
The biggest issue I run into is lenders and borrowers disagreeing about what "balloon" means in practice. Some structure it as a true demand note where the lender can call the full amount at any time after a certain period. Others lock it in as a fixed maturity date. This matters enormously for cash flow planning and refinancing strategy. I once had a client who thought his balloon was a soft maturity with a guaranteed refinance window. It wasn't. The lender could have demanded full payment on sixty days notice after year five. We caught it in the fine print during due diligence, but it was close to costing them a forced sale. Another problem is the tax treatment. Balloon payments don't change your interest deduction schedule in most jurisdictions, but they do change your cash flow timing dramatically. You're deferring principal repayment, which means you still owe it. I've seen borrowers treat the balloon like it doesn't exist until it hits. That's how properties get lost. Calculators online tend to oversimplify this. They'll show you the monthly payment and the balloon amount but rarely let you adjust for things like payment frequency variations, compounding periods that don't match payment periods, or partial periods at the start or end of the loan. If you need precision, you build it yourself or use something that lets you tweak the underlying assumptions.
When This Structure Makes Sense
Short-term holds where you plan to sell before the balloon drops. Investment properties flipped within five to seven years. Projects where rental income doesn't cover full debt service but you're counting on appreciation or a refinance to bridge the gap. Business loans where revenue is expected to jump significantly in year three or four, making a lower initial payment useful for cash flow management. It doesn't work well when you're relying on a refinance that may not materialize. Interest rates move. Property values move. Lending standards move. A balloon assumes you'll either sell or refinance, and neither of those is guaranteed. I've watched this structure fail in downturns because the refinancing market simply wasn't there when the balloon came due. If you're going to use one, build a stress case where rates are two points higher than expected and the property doesn't appreciate as projected. See if you can still make the balloon payment or refinance under those conditions. If the answer is no, reconsider the structure.
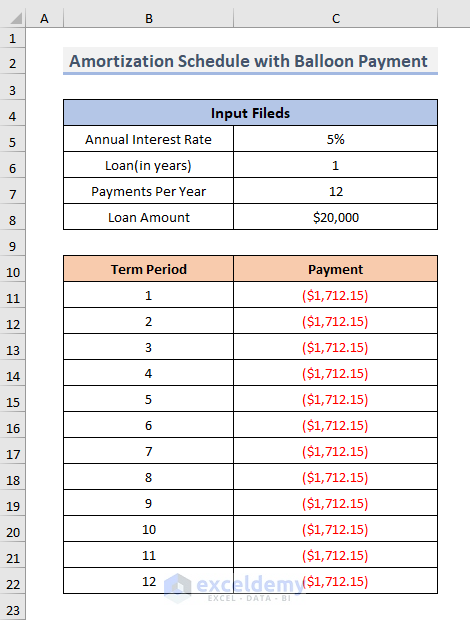
The amortization chart itself is straightforward to generate once you have the parameters locked down. I usually build mine in a spreadsheet with columns for payment number, beginning balance, payment amount, interest portion, principal portion, ending balance, and cumulative principal paid. A separate section flags the balloon payment date and amount prominently so it doesn't get buried in the rows. You can export this to PDF or share it with lenders and advisors. The key is making sure everyone reading it understands that the balloon is real money that has to be addressed, not just a line item that disappears.