The Mechanics of Currency Value Changes
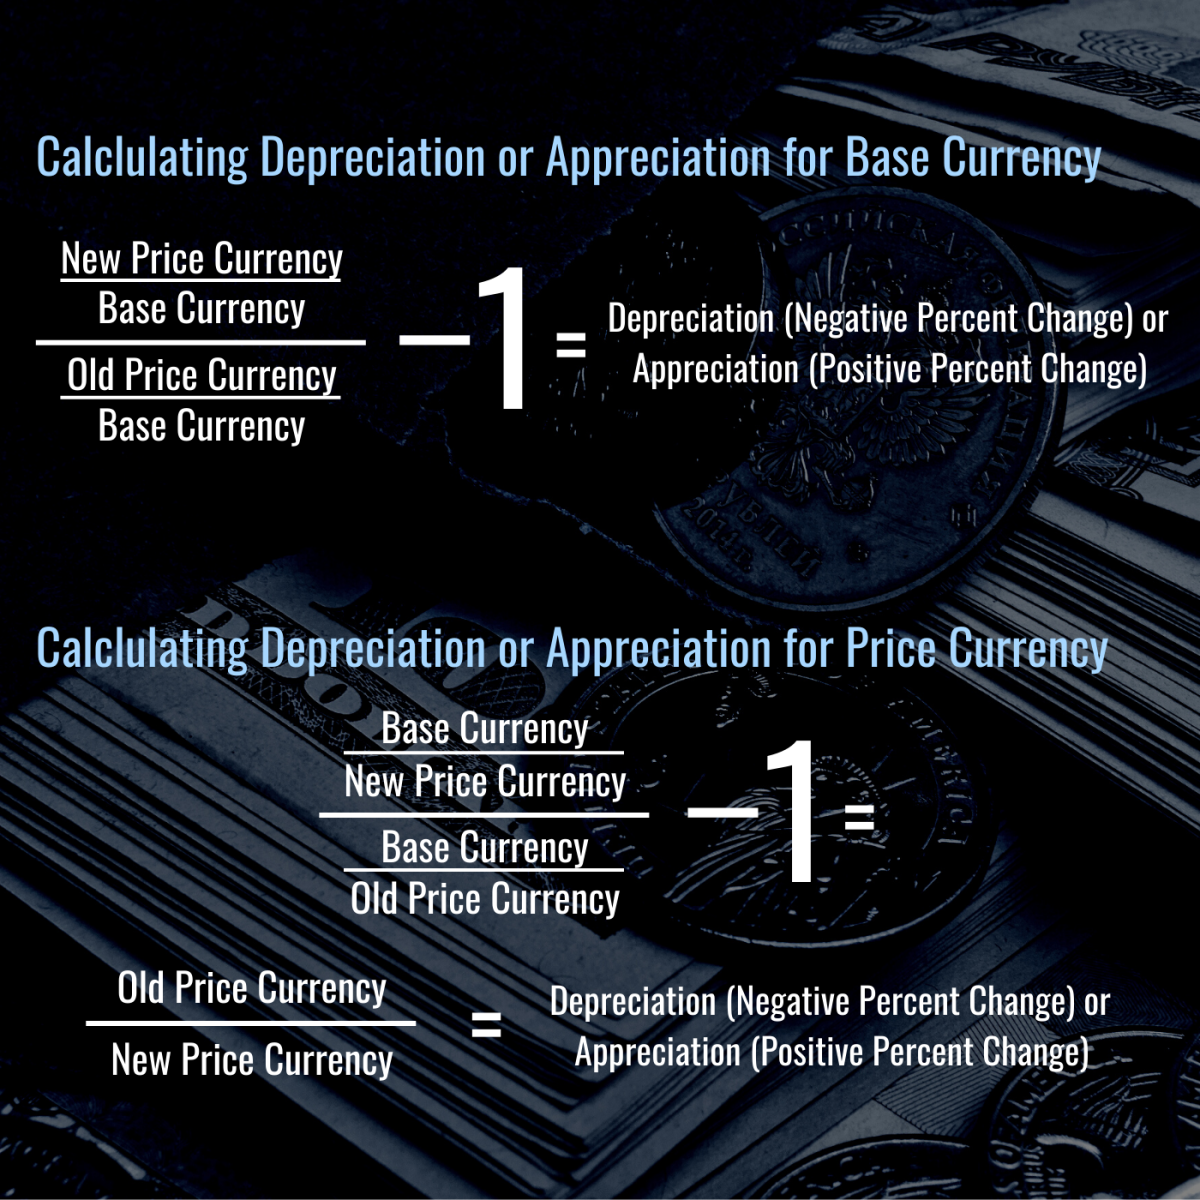
Currency appreciation and depreciation are changes in a currency's value relative to another currency or a basket of currencies. When a currency appreciates, each unit buys more of another currency. When it depreciates, each unit buys less. This matters because it directly affects import costs, export competitiveness, and the real value of cross-border contracts. Most people learn the definition in an economics class and think they understand it until they actually have to price something across borders during a volatile period. Here's the straightforward part. The nominal exchange rate is the price you see quoted. The real exchange rate adjusts that price for inflation differences between two countries. A currency can nominally appreciate while its real purchasing power barely moves if the home country has higher inflation than the trading partner. That distinction matters when you're evaluating whether an appreciation actually gives you a competitive advantage or just keeps things level in real terms. To calculate the percentage change in a currency's value against another, you take the new exchange rate minus the old exchange rate, divided by the old exchange rate, multiplied by 100. If the USD/EUR rate moves from 1.10 to 1.15, the dollar has appreciated approximately 4.55 percent against the euro. The euro has depreciated against the dollar by about 4.35 percent. The asymmetry in those two percentages is a common source of error in spreadsheets and financial models.
What Actually Drives These Movements
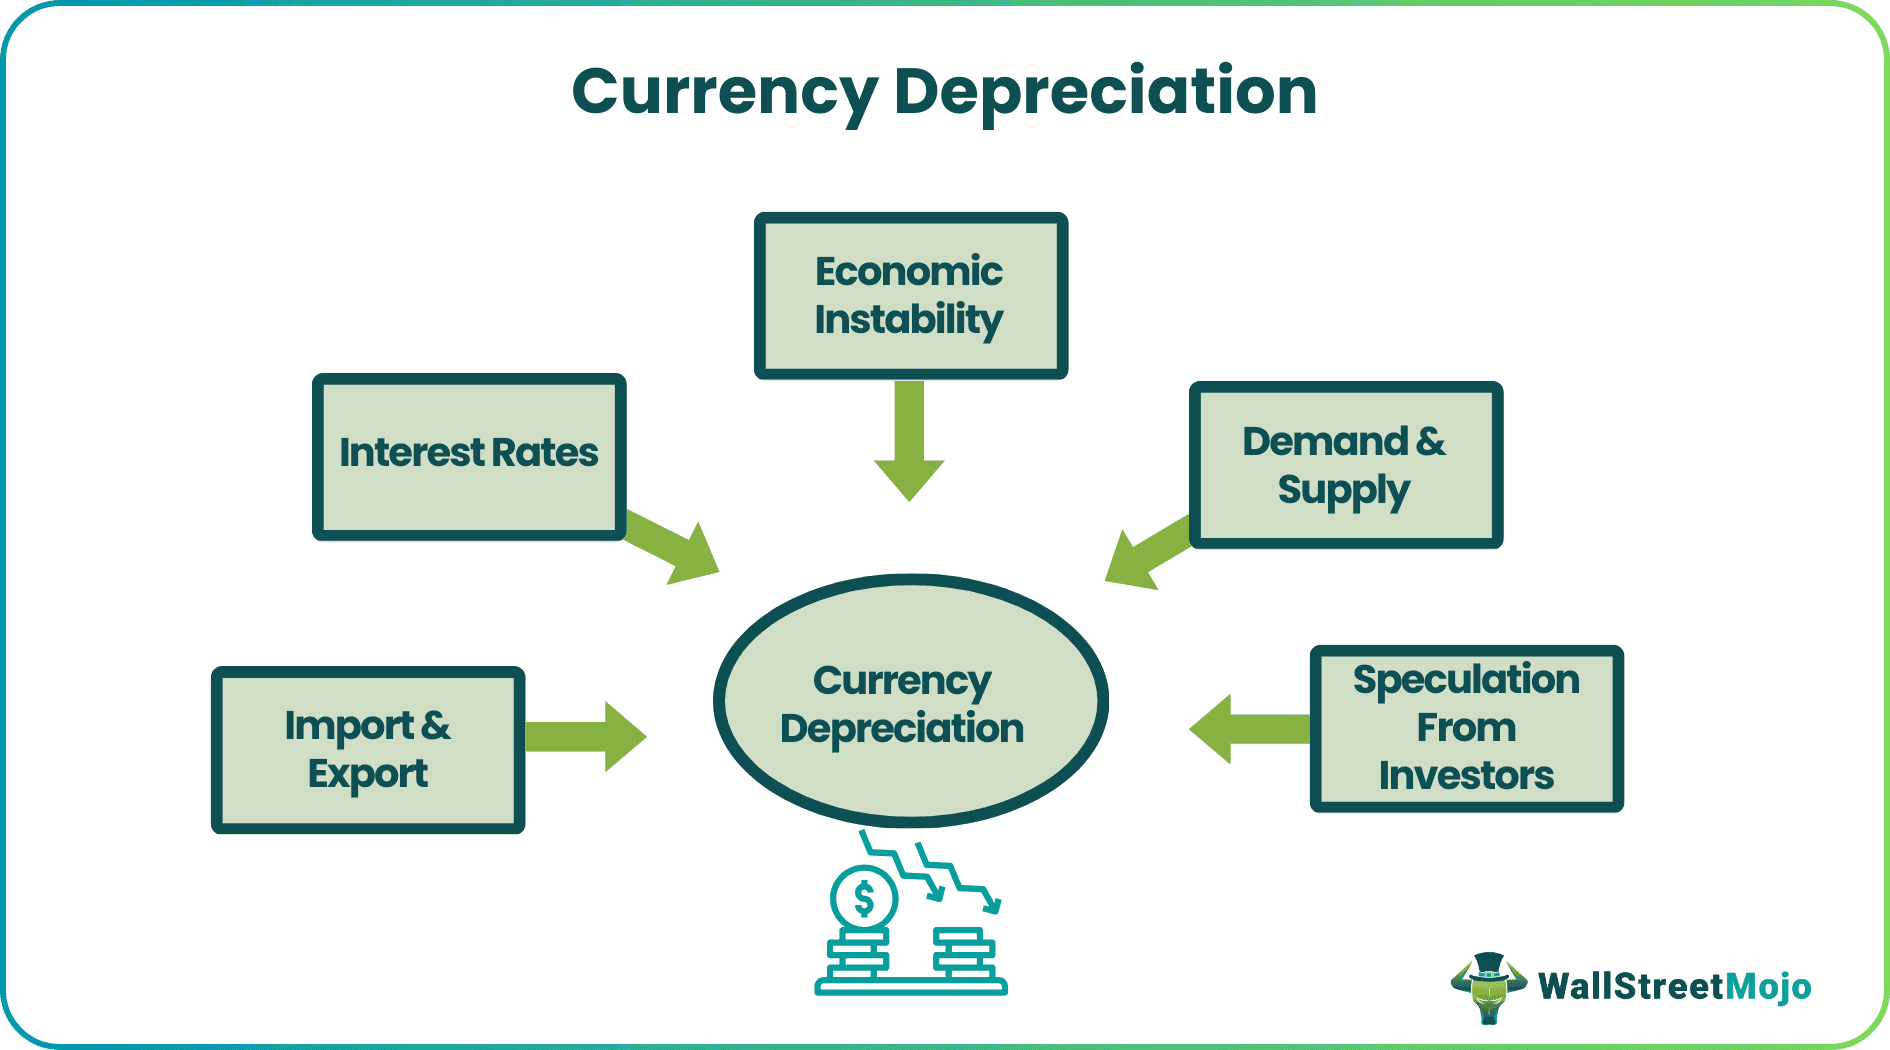
Interest rate differentials are the primary short-to-medium term driver. When the Federal Reserve raises rates while the European Central Bank holds steady, capital flows toward dollar-denominated assets, pushing the dollar higher. This is the most reliable relationship in the data, but it's not mechanical. Carry trades can stay irrational longer than expected, and the relationship breaks down during risk-off episodes when investors flee to safety regardless of yield spreads. Inflation differentials matter through the lens of purchasing power parity. A country with persistently higher inflation than its trading partners will see its currency depreciate over time. This plays out over years, not weeks. Trade balances and current account positions exert pressure too, but a large trade deficit doesn't guarantee depreciation if capital account inflows are strong enough to offset it. That's why countries like the United States can run persistent deficits without a collapsing dollar. Speculative positioning and market sentiment create short-term noise on top of the fundamentals. Central bank intervention is a direct force, though less common now among major economies. Managed float regimes like China's use intervention to smooth volatility while maintaining some degree of control over the exchange rate trajectory. Free float systems let market forces dominate, but even then, central banks occasionally step in during extreme moves.
The Calculation Methods in Practice
For nominal effective exchange rates, you weight each bilateral rate by the trading partner's share of total trade. The result is a single index that shows whether a currency is broadly strengthening or weakening across all major partners. Most analysts at least scan the trade-weighted dollar index when assessing whether dollar strength is concentrated or widespread. Real effective exchange rates add the inflation adjustment to that trade-weighted framework. This is the measure that matters for competitiveness. A manufacturing exporter in Germany doesn't care about the nominal euro-dollar rate as much as the real rate adjusted for German and American inflation. When the real effective exchange rate rises, your goods become more expensive relative to foreign competitors even if the nominal rate hasn't moved much. Cross-rate calculations come up when you need a currency pair that isn't directly quoted or when you're reconciling discrepancies across venues. Multiply the USD/EUR rate by the EUR/GBP rate to get USD/GBP. Triangulation works when markets are liquid and orderly. It falls apart during stress when spreads widen asymmetrically across pairs.
Get the Full Details

A Problem I Ran Into During a Real Hedging Cycle
I was managing currency exposure for a mid-market industrial company that imported components from Japan and exported finished goods to Europe. We had yen-denominated payables and euro-denominated receivables, and the dollar was the reporting currency. The yen appreciated sharply against the dollar while the euro stayed relatively flat. On paper, our yen costs were rising in dollar terms and our euro revenue was stable, creating a squeeze on margins. The problem was that we were using a simple rolling hedge ratio based on trailing volatility, which assumed the correlation between the yen and euro remained stable. It didn't. During a specific quarter in 2018, the yen-euro cross-rate moved independently of both rates against the dollar due to a combination of BoJ policy signal confusion and ECB quantitative tightening expectations. Our hedge model was off by roughly eight percentage points because it treated the two exposures as independent when they actually had a drifting correlation structure. The workaround was to switch from a static hedge ratio to a dynamic one that incorporated the yen-euro cross-rate volatility and the rolling correlation between JPY/USD and EUR/USD. We also started sizing hedges based on scenario analysis rather than purely historical volatility, which gave us better coverage during the dislocation. This reduced our unhedged exposure variance by approximately 40 percent over the following six months. It also required more frequent rebalancing, which added transaction costs but the math worked out in our favor given the volatility environment.
Counter-Intuitive Things Beginners Miss
First, a depreciating currency does not automatically improve the trade balance. The J-curve effect describes the lag where the trade balance actually worsens before improving after a depreciation. Existing contracts are denominated in the old currency values, so import costs rise immediately while export volumes respond only after new orders flow in at the updated price competitiveness. This lag can last anywhere from six to eighteen months depending on the sector and contract structures. If you're advising someone to sell into a weakening currency expecting immediate improvement, the data doesn't support that timeline. Second, strong economic fundamentals can produce currency weakness in the short term. When a country raises interest rates aggressively to combat inflation, the rate hike itself signals economic distress. Markets may price in future slowdown or recession, and capital may flow out on growth concerns even while yields are attractive. This happened in several emerging markets during the 2022-2023 rate cycle. The currency weakened despite higher rates because the growth outlook deteriorated faster than the yield appeal could compensate.
Where This Framework Falls Apart
Appreciation and depreciation models assume floating exchange rates and functioning capital markets. In countries with strict capital controls, the official rate and the parallel market rate can diverge significantly. Argentina is a persistent example where the official peso-depreciation figures tell one story and the blue market rate tells another. Using official rates for valuation or hedging decisions in those environments produces misleading results. Petrocurrencies and commodity-exporting nations follow their export prices more than conventional monetary models predict. The Australian dollar and Canadian dollar often move with iron ore and oil prices respectively, sometimes overriding interest rate differentials entirely. If you're modeling AUD depreciation solely on RBA policy expectations and ignore iron ore futures, your forecast will be systematically wrong. Emerging market currencies during balance of payments crises don't depreciate gradually. They gap. The Turkey lira in 2018 and the Argentine peso in 2023 both experienced discrete jumps rather than smooth depreciation trajectories. Any model assuming continuous adjustment will underestimate downside risk in those environments. Stop-loss orders and hedge execution during these events are frequently filled at levels far worse than the pre-crash rate.

Practical Estimation Shortcuts
For quick mental math, the approximate percentage change in a currency pair equals the difference between the two countries' annualized inflation rates. If domestic inflation is 3 percent and foreign inflation is 1 percent, expect roughly 2 percent annual depreciation of the domestic currency under PPP. This approximation works reasonably well over multi-year horizons but fails completely for quarterly or monthly forecasts where capital flows and risk sentiment dominate. When estimating the impact of a known appreciation or depreciation on a specific contract, multiply the transaction amount by the percentage change. A EUR 500,000 payable that becomes more expensive by 5 percent due to euro appreciation adds EUR 25,000 to the cost in the home currency's equivalent. This simple multiplication is where rounding errors accumulate in portfolios with hundreds of transactions across dozens of currency pairs. Use consistent decimal precision throughout the calculation chain.
A Note on Tools and Data Sources
For exchange rate data, the IMF's International Financial Statistics provides the most consistent long-form series across countries. The Federal Reserve's WEO database is adequate for quarterly macro work. Bloomberg and Refinitiv are faster for intraday data but their datasets sometimes diverge on historical reconstructions during periods of rate regime changes. When backtesting or comparing models across vendors, verify which rate convention each source uses—mid-market versus closing spot can create material discrepancies in high-volatility periods. Most spreadsheet-based models for tracking appreciation and depreciation can be built without specialized software. The challenge isn't the calculation, it's maintaining accurate historical rates and ensuring the base currency convention stays consistent. I've seen multiple models break because one analyst entered rates as direct quotes (USD per foreign currency) while another used indirect quotes (foreign currency per USD). The math produces opposite results from the same numbers.
When to Hedge and When to Let It Ride
If your exposure is transactional and the timeframe is under twelve months, hedging is generally prudent. The cost of hedging through forwards or options is typically a small fraction of the potential swing from an adverse move. For strategic exposure spanning multiple years, full hedging becomes expensive and may distort the underlying economics of the investment. Partial hedging with a rolling strategy is the standard compromise. Natural hedging through operational adjustments should be considered before financial hedging. If you can shift procurement to the currency of your revenue stream, you reduce the exposure at the source. This is operationally difficult but structurally superior to financial hedges because it doesn't require ongoing capital allocation to maintain coverage. The companies that get this right usually have diversified supply chains that allow sourcing flexibility without sacrificing quality or cost targets.