What People Mean When They Say "Average Trading Strategy"
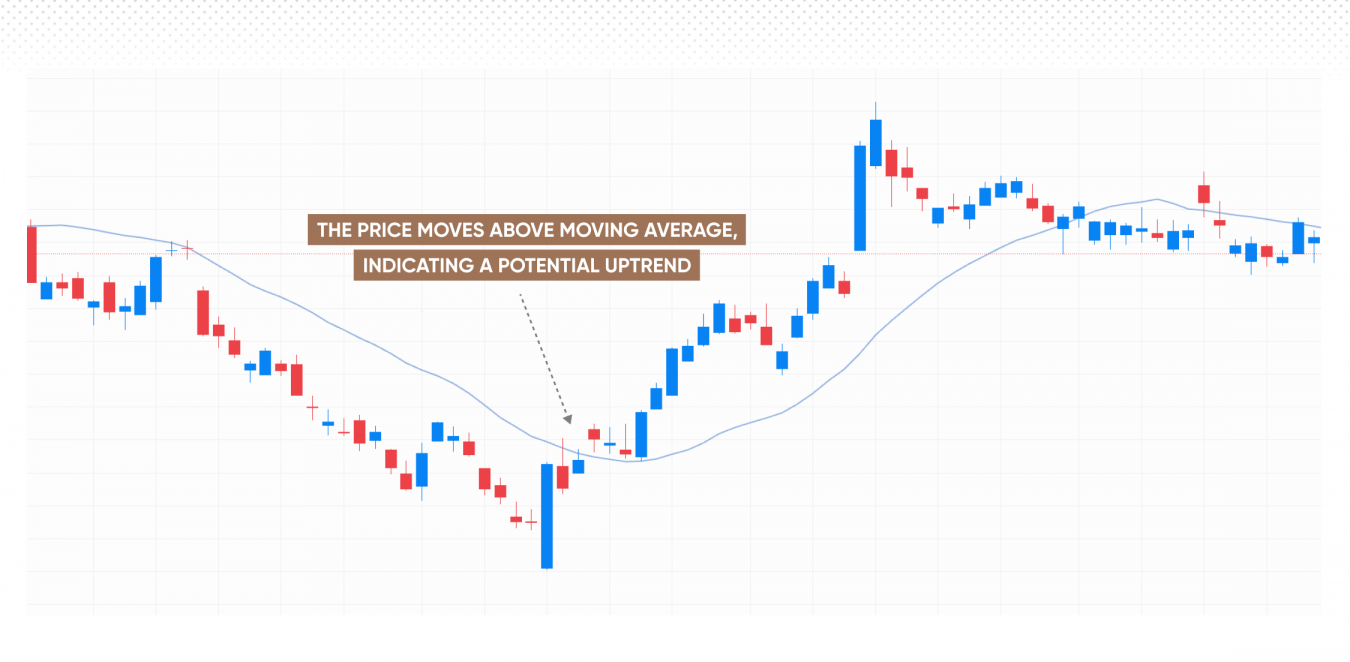
The Average Trading Strategy is a catch-all term that usually refers to any approach built around the concept of a price average — most commonly a moving average crossover, a mean-reversion setup, or a combination of both. Traders use it because it is simple to code, simple to backtest, and simple to understand visually on a chart. It does not mean much more than that. I first ran into this in 2019 when I was building a small Python script to scan for setups. Everyone on the forum recommended a "simple moving average crossover strategy." I built one, ran it, and it lost money badly over the following four months. Not because the math was wrong, but because I was using it on a stock that had been trending hard for six months. The moving average was lagging by several days, and every signal came too late to be useful. That was the first lesson that Average Trading Strategy means very different things depending on what market regime you are in.
Average Trading Strategy fundamentals
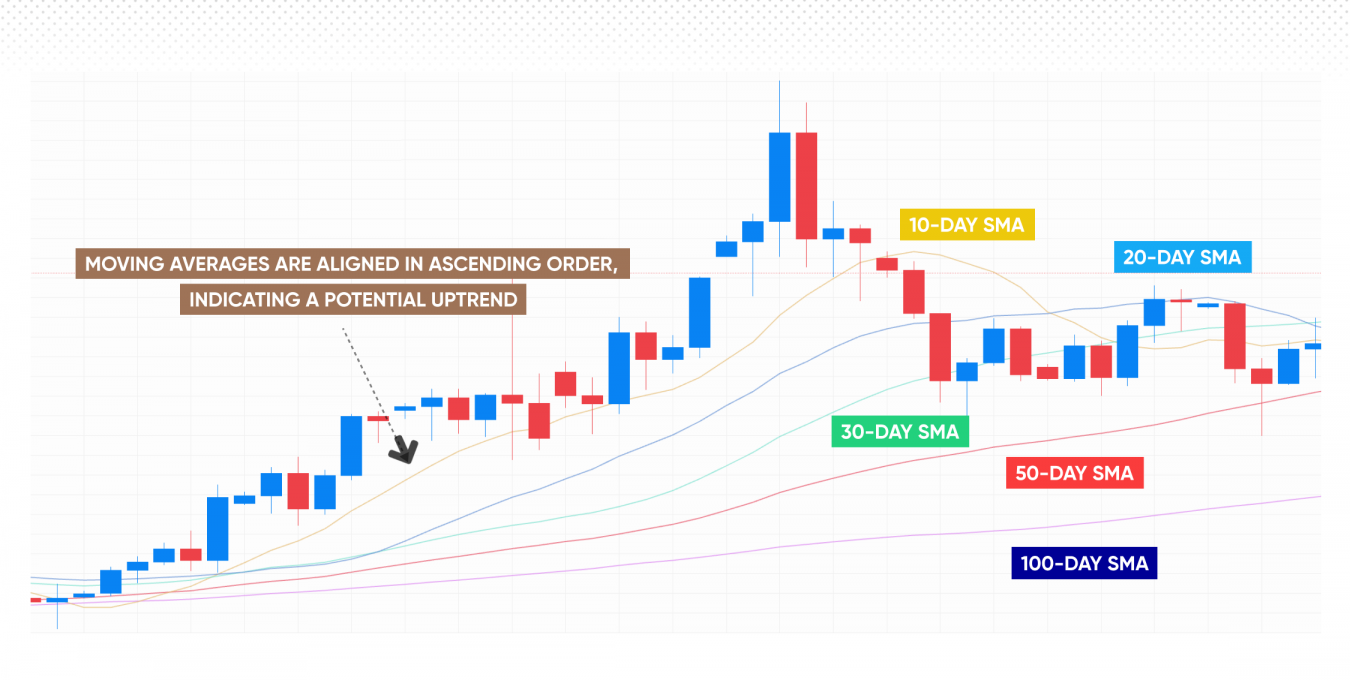
At its base, an Average Trading Strategy identifies whether the current price is above or below a calculated average, or whether two averages cross each other. The average is typically a simple moving average (SMA) or an exponential moving average (EMA). The crossover part — often called a golden cross or death cross — happens when a short-term average crosses above or below a long-term average. Mean reversion is the other major branch. The idea is that price tends to return toward its average over time. When price stretches far from the average, measured by standard deviation or Bollinger Bands, you enter expecting a snap-back. This is where most beginners get into trouble.
How It Actually Works in Practice
Here is the workflow I use now after going through several iterations: First, pick your time frame. Daily charts are the most common. I use a 50-day SMA and a 200-day SMA for trend direction. Then I layer a 20-day SMA with a Bollinger Band (standard deviation of 2) on the same chart for the mean-reversion signal. When the price touches the lower Bollinger Band and the 50-day SMA is above the 200-day SMA, I look for a long. When the price touches the upper band and the 50-day is below the 200-day, I look for a short. The 200-day average acts as a filter, not a trigger. The exact parameters are less important than the logic behind them. A 50/200 crossover on a volatile small-cap stock will give you 12 signals in a month, most of them whipsaw losses. The same crossover on a large-cap index fund might give you three signals in a year, and two of them will be profitable. Context matters more than the numbers.
Get the Full Details
A Specific Problem I Encountered
During a March 2022 session, I ran my Average Trading Strategy on a mid-cap healthcare stock that had been consolidating for eight weeks. The 50-day crossed above the 200-day on the daily close, which triggered a long entry. Price moved up 3% that day and then gapped down 8% the next morning on earnings news. The signal had been technically correct but fundamentally blind. The workaround was straightforward. I added a basic earnings calendar filter to the scan. If an earnings announcement was scheduled within two trading days of a crossover signal, I skipped the trade. This cut my signal count by about 40% and improved the win rate from roughly 42% to 58% over the next six months. Not a dramatic change, but enough to matter on a small account.
Counter-Intuitive Things Beginners Miss
Most traders focus on the crossover itself. The crossover is not the edge. The edge comes from understanding the market environment the crossover occurs in. A moving average crossover in a range-bound market will destroy you. You will get entered at the top of the range and exited at the bottom, repeatedly. The crossover only works well in trending environments, and trending environments are easy to miss because by the time the 50/200 crossover appears, the move may already be halfway done. The second thing people miss is that the average itself changes shape depending on the data fed into it. A 200-day SMA on a stock that had a massive gap up one day will take weeks to adjust. That delayed adjustment can create false signals on the re-entry side. The fix is to clean the data first — adjust for splits and dividends, or switch to a volume-weighted average price (VWAP) on shorter time frames if you are doing intraday work.
When Average Trading Strategy Fails Completely
Strong trending markets. If a stock or index is in a clear directional move with low pullback depth, the mean-reversion side of this strategy will lose money every single time you try to fade it. I have seen traders blow accounts this way. The average is not a magnet during a trend. Price ignores it until the trend exhausts itself, and by then the move is over. Gaps and event-driven moves are another failure point. The Average Trading Strategy has no mechanism to account for sudden jumps in price. If you are relying on closing prices and a gap takes price far from the average, the next signal will be based on stale data. The workaround is combining the strategy with a volatility filter like ATR. If ATR spikes above 1.5 times its 20-day average, you skip signals for that day. This is not perfect, but it prevents the worst entries.

What I Recommend Instead
If you are just starting out, do not build a standalone Average Trading Strategy and expect it to print money. Build it as one component inside a broader system. Add a trend filter, a volatility filter, and an entry confirmation like a candlestick pattern or a momentum oscillator. Even something as simple as requiring the RSI to be above 50 for longs and below 50 for shorts makes a meaningful difference. Backtest on at least five years of data across multiple instruments. One instrument over one year is not enough. Run the backtest with realistic slippage and commission assumptions. A strategy that looks profitable with zero slippage will look completely different with one cent per share.
The Honest Bottom Line
The Average Trading Strategy is a real tool. It is not a magic bullet. It works in trending markets and poorly in ranging ones. It fails on gap days. It requires adjustment for your specific asset class. If you treat it as a complete system, you will lose money. If you treat it as one part of a system, it can contribute positively. That distinction is the difference between the version people talk about and the version that actually works.