
Getting started with investing without blowing up your account
The first time I opened a brokerage account I put $2,000 into three different ETFs and a single stock I picked because a YouTube video said it was "undervalued." That stock dropped 18 percent in two weeks. The ETFs kept going up slowly, which felt less exciting but actually worked. I learned more from that one loss than from any textbook. This guide walks through the basics of getting started in investing when you are new. I am not going to tell you it changes your life. It does not. It changes your bank account over decades, and even that is not guaranteed.
Buyer Guide For Investing For Beginners
Before you put any money in, you need to understand what you are buying. A stock is ownership in a company. An ETF is a basket of stocks or bonds you buy as one unit. A mutual fund is the same idea but usually with higher fees and less flexibility. A bond is a loan you give to a government or company in exchange for periodic payments. I once tried to explain all four of these to someone at a dinner party. They asked whether an ETF was like a stock. I said yes and also no. They were still confused. Writing this down helps avoid that conversation.
Where your money goes first
If you have credit card debt above 15 percent interest, pay that down before investing. The math is brutal. You cannot reliably earn 15 percent in the market consistently. The S&P 500 averages about 10 percent per year before inflation, and that average includes years where it drops 30 percent or more. Build an emergency fund before anything else. Three months of expenses in a high-yield savings account. Six months if your income is irregular. I lost my job once and had exactly two months of savings. I had to sell investments during a downturn to cover rent. That is a terrible way to learn.
Get the Full Details
Picking your first investment
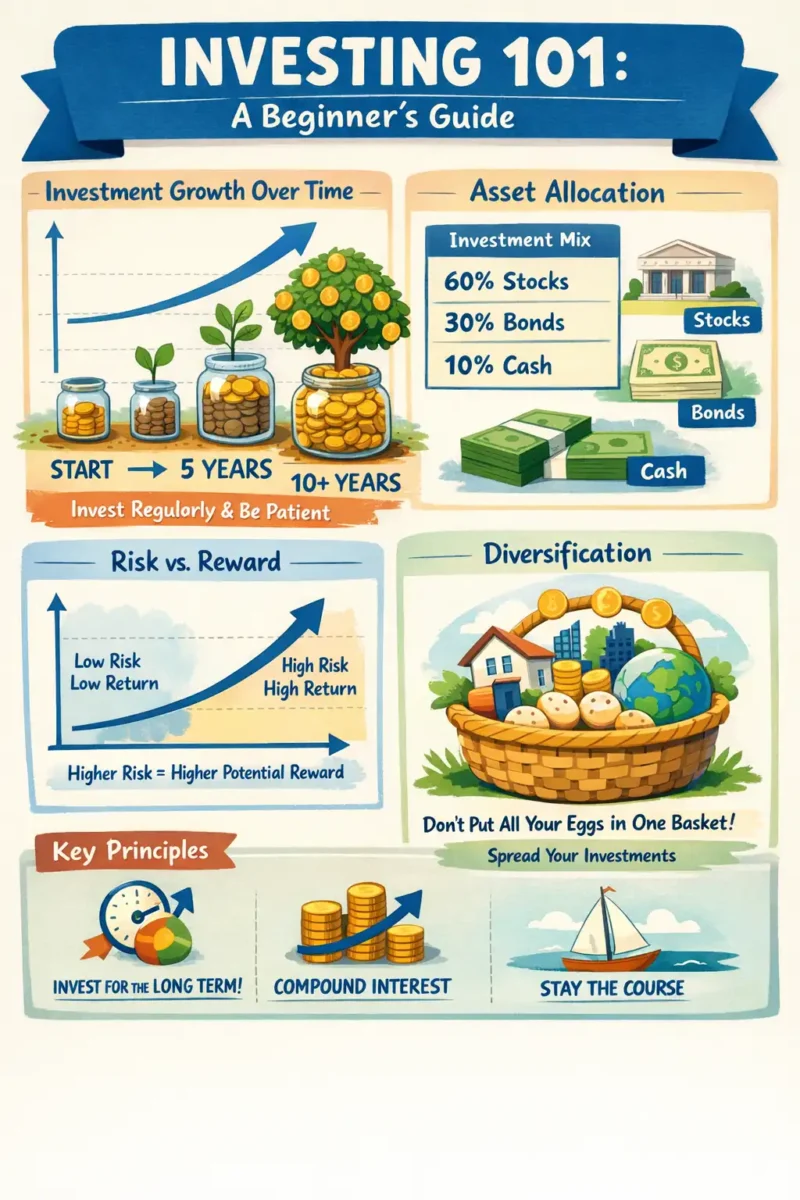
Most beginners should start with a broad market ETF. VTI covers the entire US stock market. VXUS covers international stocks. There are simpler pairs likeVOO plus a small international position. You buy one ticker and own thousands of companies. I used to think picking individual stocks was smarter. I spent hours reading balance sheets and earnings calls. My returns tracked the index minus my trading costs and taxes. The index won. Always. At least in the time period I was paying attention. When I told a colleague this he asked whether I ever picked a winner. I picked one. It went up 40 percent in eight months. Then it gave back everything plus 15 percent. The lesson was expensive but clear. Concentration increases stress and usually decreases returns.
How much to invest and when
Dollar cost averaging means investing the same amount on a fixed schedule regardless of price. You buy more shares when prices are low and fewer when they are high. It removes emotion from the equation. It also means you never time the market perfectly, which is fine because nobody does consistently. A lump sum investment statistically outperforms dollar cost averaging about two-thirds of the time. The market goes up more often than it goes down. But people who invest a lump sum and then watch it drop 20 percent in a month often panic sell. Dollar cost averaging protects you from yourself. I recommend starting with whatever amount feels survivable. $50 per month beats $500 once and then stopping. Consistency matters more than size in the early years. Your future self will thank you for showing up regularly.
Fees that eat your returns
Expense ratios are the annual fee charged by a fund. An ETF with a 0.03 percent expense ratio costs $3 per year on a $10,000 investment. A mutual fund with a 1.5 percent expense ratio costs $150 per year on the same amount. Over 30 years that difference can be hundreds of thousands of dollars. Commission-free trading is standard now. Most brokerages do not charge per trade. But some charge annual account fees or require minimum balances. Read the fine print. I once switched brokerages and missed that the new one charged $12 per month for anything below $10,000. That added up fast.
Taxes and account types
A 401(k) or traditional IRA gives you a tax break now and taxes later. A Roth IRA or Roth 401(k) gives you no break now but tax-free withdrawals later. If you expect to be in a higher tax bracket in retirement, Roth is usually better. If you expect to be lower, traditional makes sense. I maxed out my Roth IRA every year for five years. My tax bracket stayed the same. I do not know whether I made the right choice between Roth and traditional. The difference is maybe two percent annually in effective tax rate. Not worth losing sleep over. Capital gains taxes apply when you sell investments for a profit. Short-term gains are taxed as ordinary income. Long-term gains get preferential rates if you hold for more than a year. Tax-loss harvesting means selling losing positions to offset gains. It is useful but complex and sometimes pointless after accounting for wash sale rules.
What happens when things go wrong
The market drops. Sometimes 20 percent. Sometimes 40 percent. In 2008 it dropped nearly 50 percent. If you sell during a crash you lock in losses. If you wait, which most investors should, you recover eventually. The S&P 500 took about four years to recover from 2008. It took about ten months to recover from the March 2020 crash. I remember March 2020 vividly. My portfolio dropped 25 percent in two weeks. I did not sell. I added money because I still had my job. That felt counterintuitive at the time. Looking back it was the easiest decision I made. Inflation is the silent killer of cash savings. A savings account paying 0.01 percent while inflation runs at 4 percent loses purchasing power every year. This is why investing exists. Not to get rich quick. To not get poorer slowly.
Common mistakes beginners make
Chasing hot stocks is the biggest mistake. Every time there is a meme stock or a viral ticker, people pile in late and sell early. The people who make money are the ones who sold to them. Overtrading is another. Each trade costs money in spreads, commissions, and taxes. Turning a portfolio over once a year costs roughly 1 percent in frictions. Turning it over four times a year costs roughly 4 percent. That is a huge drag on compounding. I once had a client who traded weekly based on news headlines. He averaged 6 percent annual returns net of fees. The S&P 500 returned 11 percent in the same period with zero effort. He was not stupid. He was just active enough to hurt himself.

Tools and resources
Brokerage platforms like Fidelity, Vanguard, and Schwab offer low-cost ETFs and zero-commission trading. Some have no account minimums. Others require $500 or $2,000 to open. Check before you sign up. Portfolio trackers like Personal Capital or Motley Fool Foolfolio let you see your asset allocation at a glance. They also flag excessive concentration in a single stock or sector. I use one and check it monthly. More often than that leads to unnecessary watching. Books like The Psychology of Money by Morgan Housel or The Little Book of Common Sense Investing by John Bogle explain more than most courses. I read Bogle first. His argument for low-cost index funds is simple and correct. I wish I had heard it ten years earlier.
When to stop and rethink
If you are losing sleep over your portfolio you are probably invested too aggressively for your tolerance. Reduce your stock exposure until you can ignore it for a few months. This is not about maximizing returns. It is about staying invested long enough for those returns to matter. I knew a guy who had 80 percent in tech stocks and 20 percent in bonds. When tech corrected 30 percent he panicked and moved everything to cash. He missed the recovery. His allocation was fine for a bull market but broken for his psychology. Adjust accordingly. Retirement is not the only goal. Buying a house, funding education, or building a side business are all valid reasons to invest differently. There is no single correct allocation. There is only the one that lets you sleep and still grow.
The boring truth
Investing works when you are patient, cheap, and diversified. It fails when you are emotional, expensive, and concentrated. Most beginners fail because they treat it like a game instead of a habit. The game is loud and exciting. The habit is quiet and effective. I have been investing for twelve years. My biggest wins came from doing nothing. My biggest losses came from doing something. The pattern repeats. It always has. It always will. Start small. Stay consistent. Watch less. The numbers take care of themselves if you let them.

