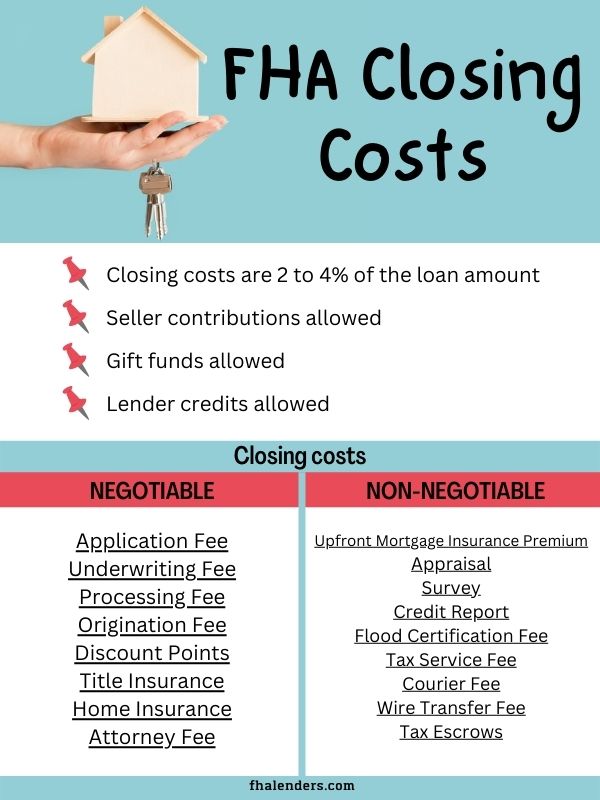
Most people walking into an FHA loan process have no idea what to budget for. The numbers look arbitrary until you break them down. Closing costs on an FHA loan typically land between 3% and 5% of the purchase price, but that range hides some pretty significant variables depending on where the property is and who the lender is.
How to Calculate Closing Costs Fha
You start with the loan amount. From there, you stack the fees. The upfront mortgage insurance premium is 1.75% of the base loan amount. That's non-negotiable. On a $250,000 home with 3.5% down, your loan is $241,250, and the upfront MIP hits $4,222. Some lenders roll this into the loan balance. Some ask you to pay it at closing. Either way, it's part of the number.
Then you have the origination fee. This varies by lender. It can be 0.5% to 1% of the loan amount, or sometimes structured as a flat dollar figure. After that, third-party costs kick in: appraisal, credit report, title search and insurance, survey, recording fees, transfer taxes, and escrow deposits. Escrow is where most first-time buyers get surprised. The lender will require deposits for property taxes and homeowners insurance to be set up before closing. That can easily add $2,000 to $4,000 to your closing table depending on the county and when your tax bills hit.
A Real Problem I Ran Into
I had a client last year trying to close on a $180,000 home in Cook County, Illinois. The estimate she got was clean — all the standard line items accounted for, seller concessions covering most of the prepaids. We were five thousand under budget at closing. It turned out the appraisal came in at $175,000 instead of the contracted price. The lender required a new appraisal because the first one had a comparables issue, and the extra $650 for that second appraisal wasn't included in the original Good Faith Estimate. FHA rules mandate two appraisals in certain situations, and the second one triggered a full redisclosure. The settlement agent had to issue an updated Closing Disclosure at least three business days before the new closing date. We ate the delay. It cost us nothing extra, but it reset the clock.
Things Beginners Miss
The six percent seller contribution cap is the most overlooked rule in FHA transactions. Sellers can pay up to 6% of the purchase price toward the buyer's closing costs and prepaid items. That's generous, but only if the contract price isn't inflated. I've seen deals where the purchase price was bumped just to maximize the seller concession, and the appraiser caught it. The deal fell apart because the adjusted value didn't cover the new price. The workaround is straightforward: let the appraisal set the real number, then structure the concession around that.
Another thing nobody warns you about is the funded discount points versus lender credits dilemma. If your credit score is solid and rates are competitive, paying one or two discount points can drop your interest rate enough to offset the cost within three to five years. But discount points are closing costs. They inflate your cash-to-close number. Lender credits work the opposite direction — the lender gives you money at closing to cover fees, but your rate goes up. It's a real tradeoff. With a FHA loan where you're already carrying MIP on top of your interest rate, the math gets tight fast.
The Brutal Limitations
The main problem with FHA closing cost estimates is that they're never final until you have a fully underwritten approval. Every change — a new debt on your credit report, a job change, a deposit over two pay periods — can restart the entire disclosure clock. The three-day review period on a revised Closing Disclosure means any adjustment pushes your closing date back a minimum of four to five calendar days. It's not a big deal if you have flexibility. It's a disaster if you're trying to align with a seller's move-out timeline or lock expiration.
GFE and HUD-1 forms have been replaced by the Closing Disclosure under TRID, which simplified the paperwork but made the disclosure process much more rigid. There's no gray area anymore. The numbers have to match within tolerances, and the tolerances are tighter than they used to be. Cumulative errors from one lender versus another can swing your out-of-pocket by a thousand dollars or more on a mid-range purchase.
What Actually Works
Request two Closing Disclosures before you sit down at the table. Compare them line by line. Focus on the Loan Estimate from your application against the final CD. Look specifically at the "Calculating Cash to Close" section at the bottom. That's where surprises hide — in the prorated items, the escrow setup, the adjustments for HOA fees or rural delivery charges that the original estimate didn't anticipate.
Don't accept the first estimate as gospel. Call the settlement agent directly and ask for a line-item breakdown before closing day. Most of the time the lender sends a generic template. The actual settlement statement has nuances that matter. I've found missing line items for flood zone certification, unexplained HOA transfer fees, and prepaid interest calculated from the wrong date. All of these are fixable if you catch them early.
Gallery Calculate Closing Costs Fha
FHA Loan Closing Costs for Beginners (Must Watch Before Buying A House ...
Down Payment And Closing Costs For Fha Loan at Ella Byatt blog
Fha Loan Closing Costs: Everything To Know – YCVPJV
Understanding FHA Closing Costs
FHA Loan Closing Costs: What Are They and How Much to Pay?