Year-End Accounting Is a Mess If You Don't Plan It
Most people treat the closing process like it shows up magically on December 31st. It doesn't. I've watched teams scramble through January because nobody mapped out a sequence before the books started closing. The difference between a clean close and a three-week disaster is usually a single document that existed six months earlier. Let me walk through what actually works, not what some textbook says should work.
Practical Ideas For Accounting Yearly Closing
Start with your trial balance before you touch anything else. I've seen accountants go straight into bank recs without confirming the unadjusted trial balance has reasonable subtotals. That's how you miss a $40,000 misclassification in depreciation that sits there quietly until someone notices revenue looks wrong by March. Here's the sequence I use: lock the prior period first. This means running a quick check on whether any prior-year entries got posted after the close. Most accounting software doesn't flag this by default. I write a simple SQL query against the GL table checking for transactions dated in the previous year but posted after the cutoff date. Takes about five minutes. Saved me from reissuing financials once because a vendor adjustment for 2022 hit the GL in January 2023 without anyone noticing. Accruals are where most year-ends die. Not because the concept is hard, but because people treat them as an afterthought. My approach is to build a running accrual schedule that updates monthly, not annually. I keep a spreadsheet that tracks every accrued liability and expense with three columns: the original estimate, the actual invoice when it arrives, and the variance. Over twelve months this tells you something most firms never learn until audit season — your estimates are consistently off by 15 to 30 percent in certain categories, and you can adjust before year-end instead of during it.
Fixed assets need a similar discipline. Depreciation schedules are usually set and forgotten in April. By December 31st, someone has likely purchased equipment, disposed of something, or moved an asset between departments and the depreciation module doesn't catch it. I pull a fixed asset register report two weeks before close and physically verify the top ten acquisitions. The ones that don't match the ledger are your problem right now instead of in April when the tax preparer calls. Inventory is a different beast entirely if you carry stock. Cycle counts during the year are fine, but they don't replace a full physical count for financial statement purposes. The problem isn't the count itself — it's the timing. If you count on December 31st and your warehouse is still receiving and shipping that day, your numbers are garbage regardless of how careful you are. I shut down the warehouse for four hours over a weekend in late December and do the count then. Yes, it requires coordinating with the operations team. Yes, it costs a day of productivity. It's cheaper than discovering your COGS is wrong by $120,000 after you've already filed. Accounts receivable needs an aging review with a purpose. Don't just pull the report and move on. I have each sales manager certify their own bucket — current, 30, 60, 90-plus. The 90-plus column is where bad debt lives, and management needs to make a deliberate decision about each account rather than applying some generic percentage to the whole thing. Last year I caught a $67,000 receivable that was four months overdue and still showing as current because the billing system hadn't pushed the aging update. The customer had stopped responding to emails in September. We wrote it off before close instead of discovering it in the annual review.
Get the Full Details
Reclassifications deserve their own file. During the year, things get miscoded constantly — expense vs. asset, liability vs. equity, revenue vs. other income. I keep a running reclass journal that posts monthly. When close time hits, this file becomes the primary source for adjusting entries instead of creating them from scratch. It's not glamorous, but it turns what should be a two-day reclassification exercise into something that takes half a day. Payroll and benefits need verification against the general ledger, not just the payroll system. The payroll processor sends you a summary. The GL might show different numbers because of accruals for PTO, bonus reserves, or benefit contributions that haven't been paid yet. I reconcile the gross payroll expense line by line against the GL for the last three pay periods of the year. The mismatch is almost always small, but the few times it's large it's because a quarter-end bonus or a layoff hit a different period than expected. Loan and debt schedules require the same treatment. Interest accruals need to be calculated through the actual close date, not the last payment date. I've seen interest expense understated by weeks at a time on revolving credit facilities because the final accrual entry was skipped. Pull your loan amortization schedule and manually calculate the accrual from the last payment date through December 31st. Check it against what the system posted.
Tax provisioning is where people cut corners and then regret it later. Don't use last year's effective rate as a shortcut. Recalculate it based on current year pre-tax income, permanent differences, and any jurisdiction changes. I had a client who used a flat 24 percent rate all year when their actual blended rate was creeping toward 27 percent because of state tax changes. The catch-up entry in January was a $90,000 hit that wiped out their net margin for the quarter. A quarterly review of the provision would have flagged this months earlier. Management reporting is often an afterthought, but it's the part that actually gets used. The statutory financial statements sit in a drawer. The management package — KPIs, margin analysis, cash flow commentary — is what the owners and board look at. Build this alongside the close process, not after it. I prepare a draft management pack two weeks before close with placeholder numbers and fill in the real data as it comes through. This means the final version is ready the Monday after the books close instead of the Thursday of the second week. Documentation matters more than people admit. Every adjusting entry needs a supporting document attached — a calculation, an email, a contract excerpt. Not because an auditor will definitely ask for it, but because six months from now when someone asks why you recorded a $50,000 reserve in Q4, you need to be able to point to something instead of saying "it felt right at the time." I name my supporting files with a consistent format: date, account number, description, preparer. It takes ten seconds per entry and saves an hour of hunting later.
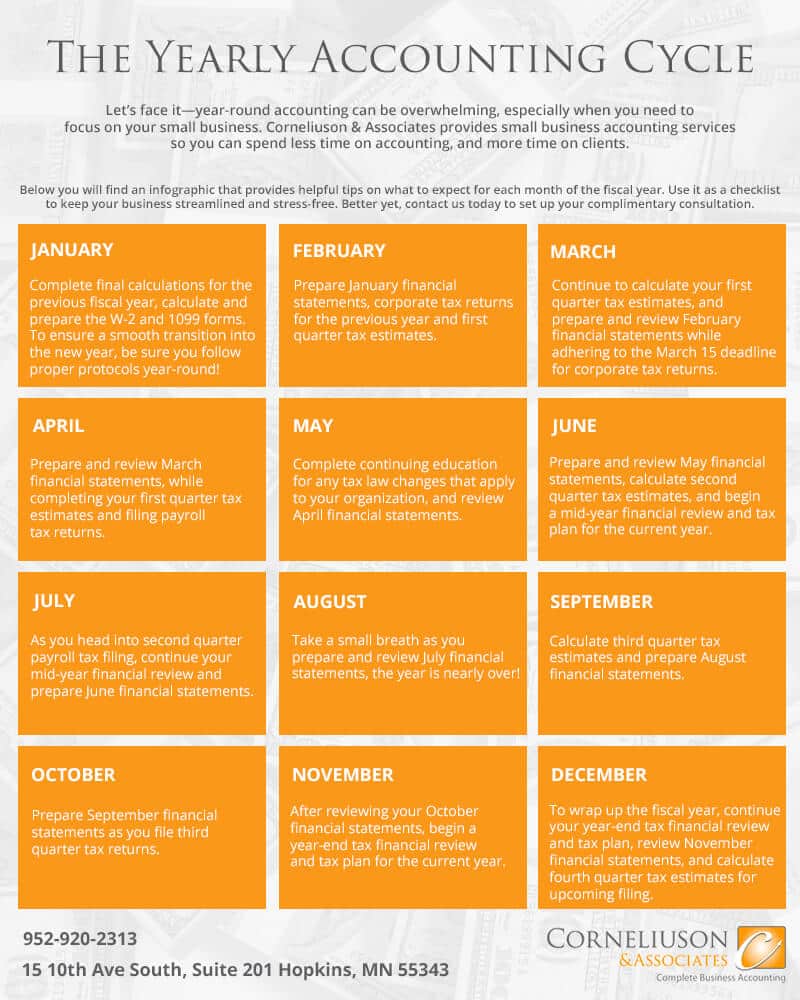
The biggest mistake I see is treating the close as a series of disconnected tasks. It's a sequence. Bank recs feed the cash account. Cash feeds the debt accruals. Debt accruals feed interest expense. Interest expense feeds the tax provision. Tax provision feeds retained earnings. If you do step one wrong, everything downstream is wrong. Map your dependencies before you start, and you'll close faster and with fewer revisions. Some of these steps can feel excessive for smaller companies, and they are. A business with under $2 million in revenue and simple operations doesn't need all of this. But the moment you cross into multi-entity, multi-currency, or inventory-heavy territory, the shortcuts start costing you more than the discipline requires. I learned that the hard way with a client who tried to run a three-entity close using the same checklist as their single-entity operation. They missed an intercompany elimination that inflated revenue by $200,000. The fix took three weeks and a restatement. If you're starting from scratch, don't try to implement all of this at once. Pick the three areas where you've had the most problems in past closes and build the process there first. Then add another three next year. Year-end accounting is rarely exciting, but it's also rarely forgiven when it's wrong. Getting it right is mostly about not being surprised.