What the Cpa Ethics Exam Actually Tests
Most people treat the ethics exam like it is a formality. You sign up, you take a multiple choice test, you move on. That approach works for about half the candidates. The other half fail on questions that have nothing to do with memorizing a code of conduct and everything to do with recognizing what the question is really asking. The AICPA ethics exam covers professional responsibility, independence rules, confidentiality obligations, and the conceptual framework approach to threats. But the way those topics show up on the actual test is where most people trip up. The questions are rarely direct recall. They present a scenario, give you four plausible answers, and ask you to pick the one that a reasonable CPA would choose under the rules. The trap is that three of the four answers often look defensible if you are thinking like a business person instead of thinking like a licensed professional.
Working Through Cpa Ethics Exam Questions Without Losing Your Mind
Here is how I actually prepare for this exam, not some generic advice you can find anywhere. First, stop trying to memorize the entire code. It does not work. The exam draws from the AICPA Code of Professional Conduct and state board rules, but the scenarios are designed to test application, not recall. You need to understand the conceptual framework: identify the threat, evaluate the significance, and apply safeguards. That structure shows up in roughly 60 percent of the questions if you learn to recognize it. Second, practice with actual scenario-based questions. The AICPA offers a self-study course that includes practice exams. Use it. But do not just check your score. When you get a question wrong, spend ten minutes understanding why the right answer is right and why each wrong answer is wrong. The explanations are where the real learning happens. Most people skip this step and move on, which is why they walk into the exam repeating the same mistakes.
Third, pay attention to the independence section. This is where candidates lose the most points. The rules around financial interests, business relationships, and nonaudit services for audit clients are nuanced. A common pitfall is assuming that any consulting work for an audit client automatically violates independence. It does not. The test looks at whether the service creates a mutual equity relationship, whether it involves management responsibilities, or whether you are auditing your own work. Those are the specific triggers, not the broad label of "consulting." One specific problem I ran into during my own prep involved a question on confidential client information. The scenario described a situation where a CPA was approached by a prospective client who wanted to know whether the CPA was currently representing their competitor in a tax matter. The answer choices ranged from disclosing the representation to refusing to discuss it at all. I initially picked the option that seemed safest, which was to decline any comment. That was wrong. The correct approach is that you can acknowledge that you have a professional relationship with the competitor without disclosing any confidential information. The exam expects you to understand that simply confirming a client relationship is not a breach, provided you do not reveal details about the engagement. I had to go back and reread the confidentiality provisions twice before that distinction clicked.
Get the Full Details
What the Exam Structure Actually Looks Like
The AICPA ethics exam is typically 100 multiple choice questions, though some state boards use different formats. You generally have about two hours. The scoring threshold is 75 percent, which sounds generous until you realize how many questions are designed to look equivalent when they are not. The content breaks down roughly like this: professionalism and responsibilities make up about 25 percent of the exam, the code of conduct and professional standards account for another 35 percent, independence rules for approximately 25 percent, and remaining topics including state-specific regulations and regulatory bodies cover the rest. If you are sitting for a state board ethics exam instead of the AICPA version, the content will overlap significantly but the weighting may differ. Some states emphasize their own rules on continuing education requirements, scope of practice, and disciplinary procedures. Check which exam you are actually taking before you start studying. I have seen candidates waste three weeks studying AICPA material for a state exam that focused heavily on their specific licensing statutes.
Practical Study Strategy That Actually Works
Do not spread your study sessions out over months. The ethics material is not dense enough to require long-term memorization. Two to three weeks of focused review is usually sufficient for someone who already has a foundational understanding of accounting principles. Start by reading through the AICPA Code of Professional Conduct at least once, even if you think you know it. You will find provisions you did not remember. The professional responsibilities section, especially the responsibilities to members and the responsibilities to.practicing members, contains language that appears almost verbatim in exam questions. After the initial read, move to practice questions. Take a full timed practice exam under realistic conditions. No notes, no phone, no breaks. This tells you where you stand before you invest time in targeted review. Most people score between 60 and 70 percent on their first attempt, which means there is concrete room to improve.
Focus your second round of study on the weak areas you identified. If independence was your problem, spend a full session working through independence scenarios. Draw out the relationships on paper. Who is the client, who is the affiliated entity, what is the reportable relationship, and which member of the engagement team is involved. Writing it out forces you to slow down and apply the rules systematically instead of guessing based on intuition. Take another full practice exam a few days before your scheduled test date. This reinforces the material and builds test stamina. The ethics exam is not particularly long, but the mental fatigue from reading dense scenarios for two straight hours can cause careless errors if you are not used to it.
Common Mistakes That Cost People Points
The biggest mistake I see candidates make is overthinking the scenario. The exam writers construct situations with extra details that are irrelevant to the correct answer. Your job is to separate the signal from the noise. If a question includes a paragraph about office politics or personal relationships, ignore it. Focus on the factual elements that trigger a specific rule: a financial interest, a gift, a contingent fee, a scope limitation, a conflict of interest. Another frequent error is choosing the answer that sounds the most ethical rather than the answer that is correct according to the code. These are not always the same thing. The exam tests compliance with professional standards, not moral philosophy. An answer that involves disclosing information to protect the public may sound right in a general sense, but if the code requires you to maintain confidentiality in that specific situation, it is the wrong answer on this exam. There is also a tendency to second-guess yourself when the question involves a gray area. The ethical landscape has gray areas, yes, but the exam questions are designed to have one clearly correct answer based on the applicable rule. If you find yourself torn between two options, reread the question and look for the specific trigger. The rule that matches the trigger is your answer. Do not pick the option that requires the fewest assumptions.
When the Ethics Exam Is Not Enough
Passing the ethics exam is a requirement in most jurisdictions, but it is not a guarantee of good judgment in practice. I have seen licensed CPAs who scored well on the exam struggle with real-world ethical dilemmas because the exam conditions are artificial. There is no client breathing down your neck, no partner asking for a favorable opinion, no deadline pressure. The exam tests your knowledge of the rules in a vacuum. Professional judgment under real conditions requires something more. If you want to build actual ethical decision-making ability, supplement your exam preparation with case studies and discussion with experienced colleagues. Look at disciplinary cases published by your state board. Reading about what actually went wrong for other CPAs is more instructive than any multiple choice question. The ethics exam is a gate. You need to pass through it, but getting through it does not mean you understand everything you will face as a practicing CPA. Treat it as a foundation, not the entire building.
Final Notes on Timing and Test Day
Arrive early or log in early depending on whether your exam is in person or online. Technical issues during the login process are rare but they happen, and they eat into your time. Give yourself a buffer. Do not rush through questions you find easy. The straightforward recall questions are there to build confidence, but they are easy to misread if you are speed-reading. Read the question stem completely before looking at the answer choices. I have lost points on questions where I assumed the answer based on the first sentence and then committed to the wrong option when the second sentence changed the scenario entirely. Flag questions you are unsure about and move on. The exam is not designed to make you sit on a difficult question for five minutes. You can return to flagged questions later if time allows. Spending 90 seconds on a tough question and moving on is better than spending three minutes and running out of time for questions you would have answered correctly.
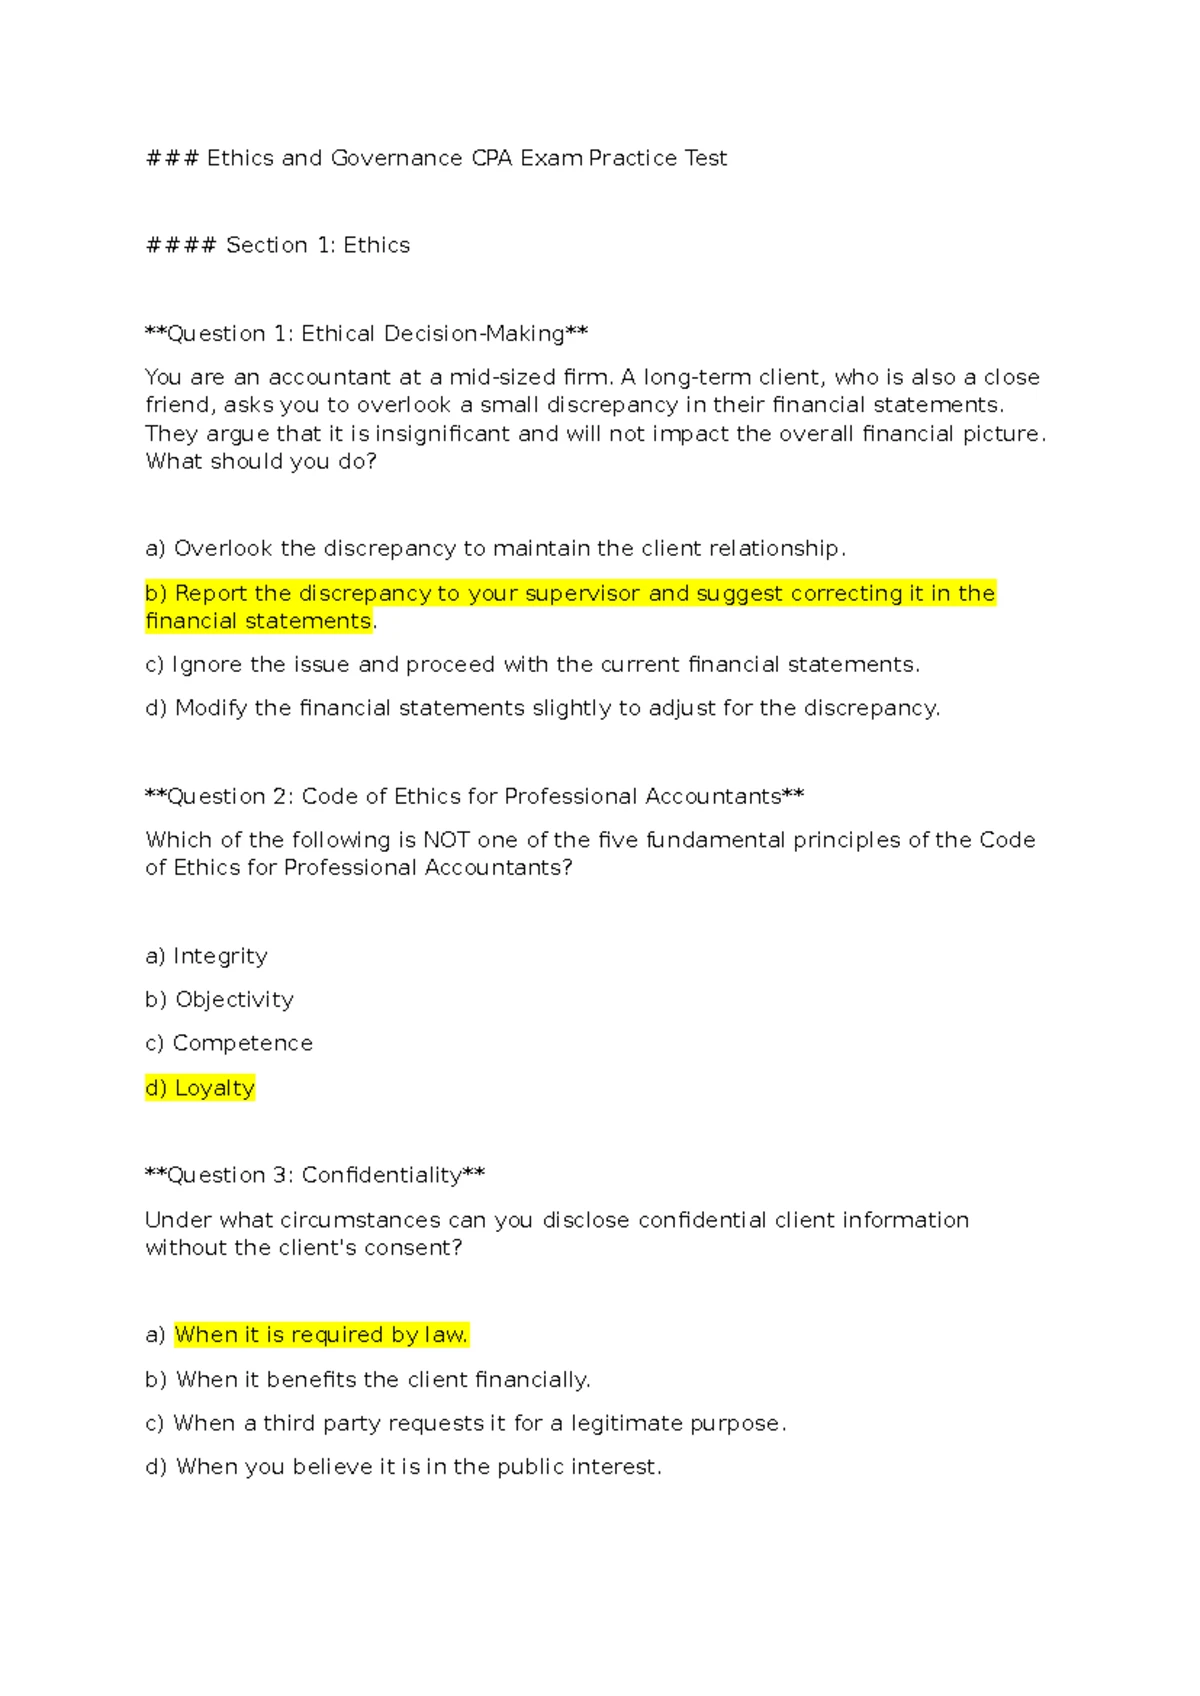
The AICPA offers downloadable resources and sample questions on their website. State boards usually publish their own study materials. Use whatever official resources are available for the specific exam you are taking. Third-party study guides can be helpful for additional practice questions, but they should supplement official materials, not replace them. The wording on third-party questions sometimes does not match the precision of the official exam, which can create confusion about what exactly the rule says. Good luck with it. It is a manageable exam if you approach it with the right strategy and do not treat it like a memorization test.