The Actual Process of Using a FAR Study Guide
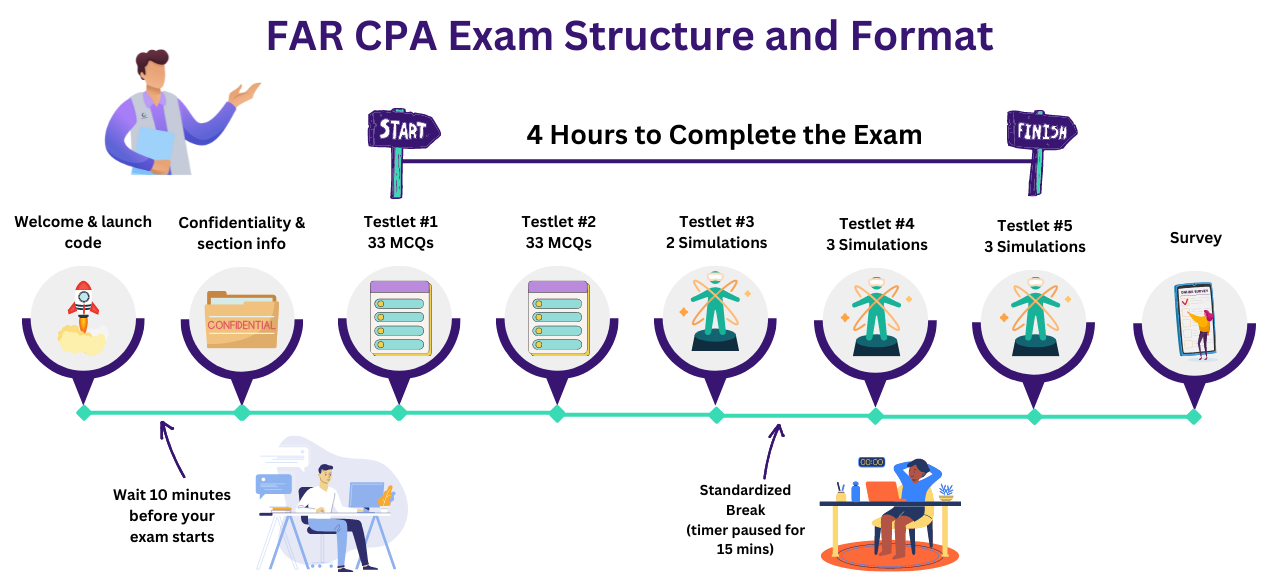
Most people treat study guides like they're going to read them cover to cover before the exam. That approach doesn't work. The FAR exam is roughly 200 questions split across two three-hour sessions. You need to move through material efficiently and then practice applying it under timed conditions. A Cpa FAR Study Guide is only useful if you treat it as a reference tool layered on top of active practice, not as something to passively consume. I started with the high-weight topics and worked backward from there. Governmental accounting and not-for-profit organizations combined for about 15 to 20 percent of the exam. Cash basis versus accrual basis confusion shows up constantly in questions, so I spent more time on the mechanics than most people expect. Lease accounting after ASC 842 took me roughly two weeks to fully grasp because the right-of-use asset and lease liability calculations interact in ways that aren't obvious until you work through five or six complete problems from scratch. The method I used was straightforward. Each day I picked one topic, read the relevant section of my guide for 45 minutes, then immediately did 20 to 30 multiple choice questions on that exact topic. If I scored below 70 percent, I went back and reworked the problems I got wrong instead of moving forward. That habit alone prevented the illusion of competence that catches a lot of candidates off guard during review weeks.
Revenue recognition under ASC 606 is another area where the surface-level summary in most guides misses the practical difficulty. The five-step model sounds clean on paper. The actual exam questions layer in variable consideration, constraints on variable consideration, and satisfaction over time all in a single scenario. I ran into a problem once where a performance obligation was satisfied over time but the measure of progress kept shifting because the contract included a milestone payment tied to regulatory approval. The guide I was using explained the concept but never showed a question where that interaction actually occurred. I had to go to a separate question bank and hunt for similar problems until I could calculate the constraint adjustment correctly without second-guessing myself.
What the Guides Actually Get Wrong
Several widely used study guides compress bond accounting into a simplified format that omits certain edge cases the exam still tests. Discount and premium amortization using the effective interest method is usually covered adequately. What tends to be underrepresented is the treatment of bond issuance costs under ASU 2015-03 and how they interact with debt modification analysis. A candidate who only knows the basic entry might struggle with a question that combines debt extinguishment with a troubled debt restructuring scenario. Pension accounting under ASC 715 has a similar gap pattern. The guides explain service cost, interest cost, and expected return on plan assets. They rarely show a complete problem that requires calculating the amortization of prior service cost alongside a gain or loss corridor test in the same year. That combination is exactly what appears on the exam when they want to differentiate between candidates who have memorized definitions and those who can run through the full pension worksheet. The biggest bottleneck I found was time management during the review phase. Working through full minibeds and performance assessments takes significantly longer than practice questions alone. A standard two-beat performance assessment can take 25 to 40 minutes depending on the task complexity. Trying to do those before you have the underlying concept solid usually just wastes time. I waited until I had completed at least one full pass through each major topic area before introducing formal write-ins and task-based simulations. That timing cut my simulation practice time by roughly half compared to earlier attempts.
Get the Full Details
Choosing Between the Main Guide Options
The three dominant providers structure their FAR content differently. One organizes material by financial reporting areas in a linear progression from financial statements through governmental accounting. Another bundles concepts into shorter weekly modules with heavy question integration built into each lesson. The third relies on condensed note sets and expects you to fill gaps with a separate question bank. None of these approaches is wrong. They just match different learning styles. If your background is in auditing rather than financial reporting, the linear progression format tends to work better because it builds concepts from the foundation up. If you are retaking the exam after a previous attempt, the condensed note set paired with an extensive question bank will save you time by removing content you already understand. I retake candidates often skip straight to question banks and use study guides purely for targeted review of weak areas. That shortcut fails for first-time test takers because the gaps are usually broader than they appear.
Practical Workarounds and Known Limitations
No single guide covers every question variation. Governmental accounting subsections on interfund transactions and trust fund reporting are where most guides fall short. I ended up using supplementary materials from a separate provider specifically for that topic. The gap was noticeable when I took a full-length mock exam and missed three questions on internal activity elimination entries. After two days of focused additional practice, those disappeared from my wrong answer log. Another limitation is that study guides cannot replicate the actual testing software experience. The FAR exam interface has specific tools like the ticker, calculator function, and flag feature that behave in ways that matter during a timed session. My recommendation is to run at least three full simulated exams in the official testing environment before test day. The simulation software provided by the main study guide vendors is acceptable but not identical to the Prometric interface. The differences are small but they add up when you are working under pressure. Cost is a factor worth noting. A complete FAR preparation package from a major provider typically runs between four hundred and six hundred dollars. Some candidates combine a lower-cost course with a standalone question bank and end up spending less while covering more practice material. The trade-off is that you lose the integrated review system. For candidates with tight schedules, the integrated package saves time even if it costs more upfront. For candidates studying over several months, the modular approach is usually sufficient.
The FAR exam rewards depth in a few core areas rather than breadth across every topic. Mastering financial statements, leases, pensions, revenue recognition, and governmental accounting at a strong level will cover the majority of your score. The remaining topics act as tiebreakers. I recommend focusing your study guide usage accordingly instead of treating every chapter with equal weight.