Building a Daily Finance Worksheet That Actually Works
I spent three years trying to get my personal expense tracking to stick. The problem was never motivation. It was the tool. Most spreadsheets people build are either too simple to be useful or so complicated you abandon them by November. A Daily Finance Worksheet sits somewhere between a grocery receipt and a full general ledger. Getting it right matters more than you'd think. Here's how I ended up with something I actually use daily instead of something that collects digital dust.
The Core Structure of a Daily Finance Worksheet
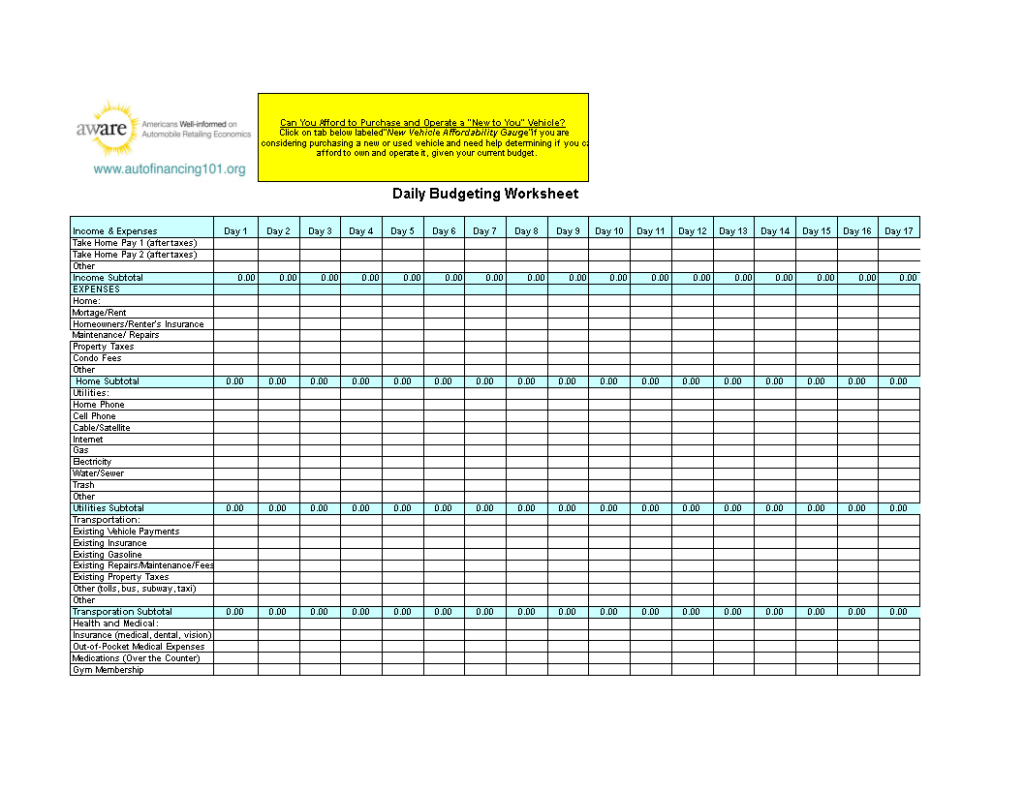
Start with columns you'll actually fill in without thinking. Date, transaction description, category, amount in, amount out, and running balance. That's it for the main grid. Anything beyond that is noise in the beginning. I used to add subcategories for everything. Food, then food at home, food out, groceries, takeout. Ended up spending more time categorizing than tracking. The fix was collapsing it down to two top-level buckets: necessities and everything else. I could always go back and split later if I needed more granularity for a tax return or budget review. The running balance column is where most people mess up. It's not just a total. It's a checkpoint. If your running balance doesn't match your actual bank balance at the end of the week, you have a missing transaction or a double entry. Catching that on Wednesday is easy. Catching it at month end is a nightmare.
What No One Tells You About Maintenance
The biggest mistake I see is building a worksheet with way too much automation right out of the gate. VLOOKUPs, INDEX/MATCH, data validation dropdowns everywhere. None of that matters if you're not going to maintain it. I spent a weekend building a fully automated dashboard with conditional formatting and charts. Used it for eleven days. Then I built something with plain cells and basic SUMIF formulas that I've kept running for two years. Keep the math simple. Use SUM for totals. Use COUNTA to check you haven't missed a row. If you need to categorize, just type and keep it consistent. Consistency beats cleverness every time.
Get the Full Details
One Specific Problem I Ran Into
I had a recurring issue where my worksheet showed a different balance than my bank statement because of pending transactions. The worksheet would show money as spent the moment I typed it in, but the bank hadn't actually settled it yet. This caused false alarms constantly. I thought I was overspending when I wasn't. The workaround was adding a second section below the main log called Pending Transactions. Every time I made a purchase that hadn't cleared, I logged it there with a pending label. Once it showed up on the bank statement, I moved it to the main log and deleted it from pending. This took maybe ten extra seconds per transaction. It eliminated all the false discrepancies immediately. Another edge case I hit was with subscription payments. A monthly fee hits on the 3rd, but sometimes it falls on a weekend and posts on the Monday. My worksheet had it logged under the wrong month and my monthly totals were off by a full cycle. I started checking the actual post date on the bank statement rather than assuming. Now I always verify before entering anything recurring.
Advanced Details That Separate Useful Worksheets From Clutter
Once you have the basic structure down for a few weeks, there are a few things worth adding. The first is a monthly summary sheet. Not complex. Just a tab that pulls totals from your daily log using SUMIF against the category column. It takes maybe thirty seconds to set up and saves you fifteen minutes at the end of every month when you're reviewing where your money went. The second is a cash category. Most people forget about physical cash and small purchases that slip through. Coffee, tips, parking meters. A twenty-dollar weekly category might not seem like much. Add it up over a year and it's almost a thousand dollars with no idea where it went. I track cash separately now. It shows up clearly in the monthly summary and it forces you to notice it. One counter-intuitive thing I learned: the more detailed your categories are early on, the worse your data quality becomes. People stop logging small purchases because they don't want to spend thirty seconds picking the right category from a list of twenty options. Broad categories produce more complete data. You can always split later when you have a reason to.
Common Pitfalls to Avoid
Don't try to track every single transaction from day one. That's a fast track to burnout. Start with your biggest categories first. Rent, groceries, utilities, transportation. Fill those in consistently for a month. Then layer in the smaller stuff. You'll already have the habit and the system won't feel overwhelming. Another trap is using your worksheet as both a record-keeping tool and a forecasting tool. They serve different purposes. The daily log should record what happened. A separate forecast sheet can project where you're headed. Mixing them confuses the data. Keep the logs clean and simple. Build forecasts separately if you need them. The third pitfall is never reconciling. I know people who fill in their worksheets for months and never compare them against their bank statements. That defeats the entire point. Reconciliation is what makes the data trustworthy. Do it once a week at minimum. Monthly is acceptable if you're strict about it. Anything less and you're just maintaining a fiction.

When a Daily Finance Worksheet Isn't the Right Call
This approach works well if you're tracking personal finances or a small household budget. It breaks down if you're managing accounts receivable for a business with dozens of clients, or if you need real-time multi-account synchronization. Those are better served by dedicated accounting software. A worksheet gives you control and transparency. It doesn't give you automation at scale. If your transaction volume is high enough that manual entry takes more than twenty minutes a day, you're better off connecting your accounts to something like a personal finance app and exporting the data periodically. The app handles the grunt work. The worksheet can still serve as your summary and analysis layer on top of that exported data. For most people though, a straightforward daily log with a running balance and basic categories is all you need. It doesn't require subscriptions. It doesn't depend on an internet connection. And it works as long as you actually use it, which comes down to keeping it simple enough that it doesn't feel like a chore.
Getting Started With Your Own Daily Finance Worksheet
You can build this in any spreadsheet program. Google Sheets works fine. Excel works fine. The tool doesn't matter. What matters is the structure. Set up the columns I mentioned. Log your first week. Reconcile at the end of it. If it takes longer than twenty minutes a day, cut something out. If you skip more than three days in a row, simplify further. The worksheet should serve your habits, not the other way around. I've seen people build beautiful multi-sheet financial dashboards with pivot tables and macros. Then they abandon them after two weeks. I've also seen people log transactions in a plain text file for years and come out ahead. The difference isn't the tool. It's whether the system fits into an existing routine without fighting it.