Mapping Where Europe Gets What It Needs
The Distribution Of Natural Resources In Europe is uneven by design, and anyone who has tried to model supply chains around it quickly learns that "Europe is resource-poor" is the right headline but the wrong summary. The continent imports roughly 69% of its energy, 98% of its critical raw materials, and still manages to be a net exporter in a few narrow categories. That contradiction is where the real story lives. I spent three years working on a project tracking rare earth and battery mineral flows into the EU, and the first thing that hit me was how badly most public maps lie. They show reserves on paper. They don't show who controls the refining, the shipping lanes, the tariff schedules, or the single plant in Slovenia that processes 40% of Europe's boron. I learned to stop looking at extraction maps and start looking at processing chokepoints. The chokepoints tell you everything.
Understanding The Distribution Of Natural Resources In Europe
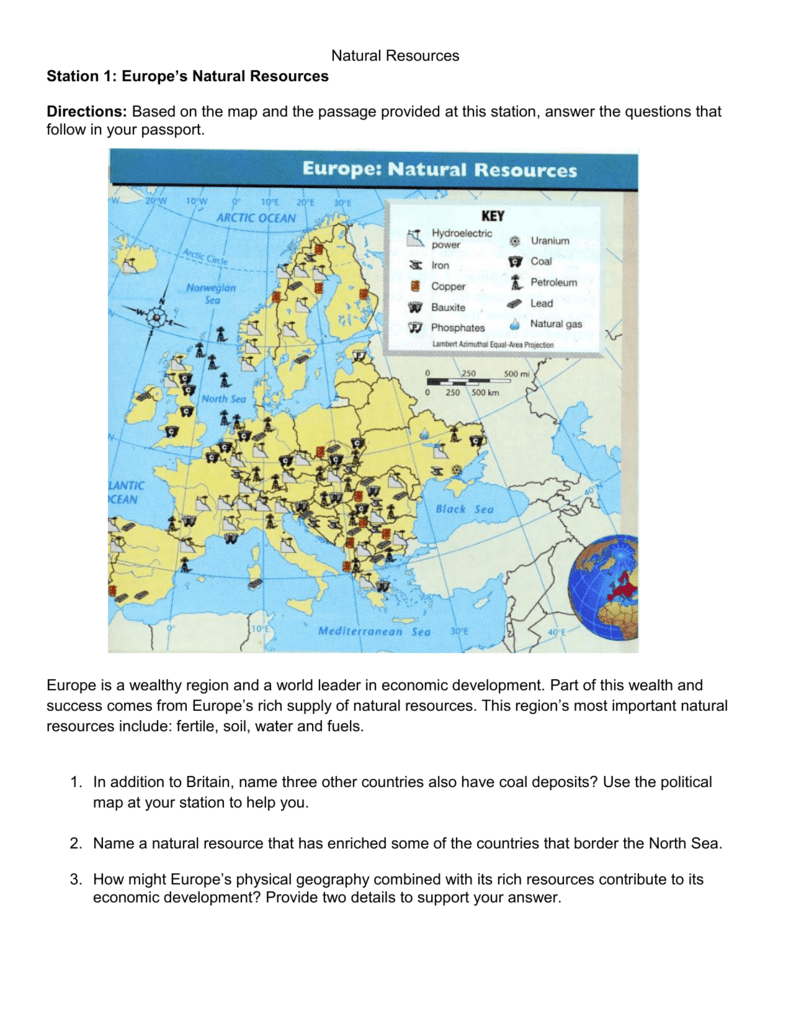
Here is the baseline before we get into the stuff nobody talks about. Europe's most significant domestic resources fall into a few buckets. Coal is still mined in Poland, though at declining volumes. Iron ore comes mainly from Sweden and Finland, with smaller operations in Romania and Spain. Copper deposits exist in Poland, Finland, Sweden, and Portugal. Bauxite is mined in Hungary, Greece, Romania, and France. Potash and salt deposits run through Germany, Poland, and the Baltic states. Natural gas reserves sit under the Netherlands, Norway, Denmark, and Romania. The North Sea gas fields peaked around 2015 and have been in structural decline ever since, which changed the entire calculation for German and European industrial policy. Rare earth elements and critical raw materials are another story entirely. Europe has deposits. Lithuania has some. Russia has the vast majority of near-European deposits in the Kola Peninsula. But having ore in the ground and having usable supply are two different things. The EU's list of critical raw materials runs to about thirty entries, and fewer than five have any meaningful domestic production pipeline. Most of the rest depend on single-country supply chains that run through China, South Korea, or Democratic Republic of Congo.
How I Actually Track These Flows
When I needed reliable data for a client in 2021, I stopped using aggregate reports and started pulling from six overlapping sources. Eurostat's material flow accounts gave me trade-level detail by commodity code. The British Geological Survey's Mineral Resources Data System had decent European reserve estimates. The JRC's Critical Raw Materials reports covered the policy and supply-risk angles. The U.S. Geological Survey mineral commodity summaries filled in gaps, especially for non-EU European countries like Norway and Turkey. For refining capacity, I used company annual reports and the IEA's Mineral Market Reports. And for shipping data, I looked at UN Comtrade for bilateral trade flows, which exposed things the aggregated EU data smoothed over. The specific problem I ran into was with gallium and germanium. On paper, Europe had some secondary production from zinc and coal processing. The numbers looked fine. Then I traced the actual output from the Solvay plant in Belgium and the two German facilities that processed these metals as byproducts, and realized their combined output covered maybe 8% of EU demand. The rest came through China, which had tightened export controls in 2023. The workaround was simple but expensive: I reclassified those supply figures as "theoretical European capacity" rather than "available supply," which made the risk picture much more accurate and forced the client to rebuild their procurement strategy around alternative sourcing or material substitution.
Get the Full Details

The Counter-Intuitive Parts Nobody Teaches
First, geographic proximity to deposits does not equal supply security. Norway sits on massive offshore gas and significant onshore mineral potential, yet its refining capacity for many processed metals is limited. Meanwhile, landlocked countries like Austria and Switzerland host major refining and processing operations because of their engineering capacity, logistics access, and regulatory environment. The resource is not where the value is added. Second, recycled content in Europe is far more significant for supply security than most people realize. Secondary aluminum production in Europe accounts for a large share of domestic aluminum supply. Copper recycling handles a meaningful portion of demand. The problem is that recycling rates vary wildly by material. You can recycle aluminum almost indefinitely with minimal quality loss. Recycling rare earths from magnets is technically possible but economically marginal at current scales. So the distribution of recycled supply is itself uneven, and it concentrates in countries with established sorting and processing infrastructure—Germany, Italy, Sweden, Spain.
Where The Data Breaks Down
Here is what most guides won't tell you. The reserve figures for many European countries are outdated or intentionally vague. France doesn't publish detailed mineral reserve data publicly anymore. Italy's data is sporadic. Turkey straddles Europe and Asia and often appears in both datasets with inconsistent classification. Non-EU European countries like Ukraine, Serbia, and North Macedonia have deposits that are geopolitically relevant but rarely included in standard EU resource models. I had to pull Serbian mining permit data directly from the ministry because no Western database covered it adequately. Also, the EU's own Critical Raw Materials Act has thresholds that create blind spots. Materials below certain strategic relevance cutoffs don't get tracking priority, but they can still cause supply disruptions. I saw this when a minor ceramic-grade clay shortage from Spain delayed production for a German industrial ceramics manufacturer. The clay wasn't on any critical materials list. It wasn't critical to anyone until it was.
What Works For Planning
If you are building a supply chain assessment around European resource distribution, start with processing capacity, not reserves. Map every step between ore and end product. Identify which step has the fewest geographically diversified nodes. That is your risk point. Then layer in trade dependency data to see which risk points overlap with single-country export controls or tariffs. You will find that the overlap zones are where actual supply shock happens. For energy, the domestic picture is simpler but less comforting. Russia supplied about 45% of EU gas imports before 2022. Norway replaced most of that volume by 2024. LNG terminals brought in additional diversification, but at higher cost. The net result is energy security improved materially, and prices settled at a permanently higher floor than the 2010–2021 period. That price shift alone has reshaped European industrial competitiveness, particularly for energy-intensive sectors like fertilizers, aluminum, and chemicals. The resource is still distributed the same way. The economics around it changed completely.

What I Would Do Differently
Earlier in my career, I treated raw resource distribution as a static problem. It isn't. Climate change is opening new access questions in the Arctic, particularly around Norwegian and Russian territory. Deep-sea mining regulations are still being written and could either unlock European seabed resources or shut them down entirely before they start. The green transition is creating demand for materials Europe doesn't meaningfully produce, which means the distribution question is becoming a negotiation question rather than a geology question. The countries that figure out how to structure offtake agreements, joint ventures, and processing partnerships now will have a structural advantage over those that wait for domestic deposits to become economical. They almost certainly won't be economical in most cases within the next decade.