Building a Monthly Finance Journal That Actually Sticks
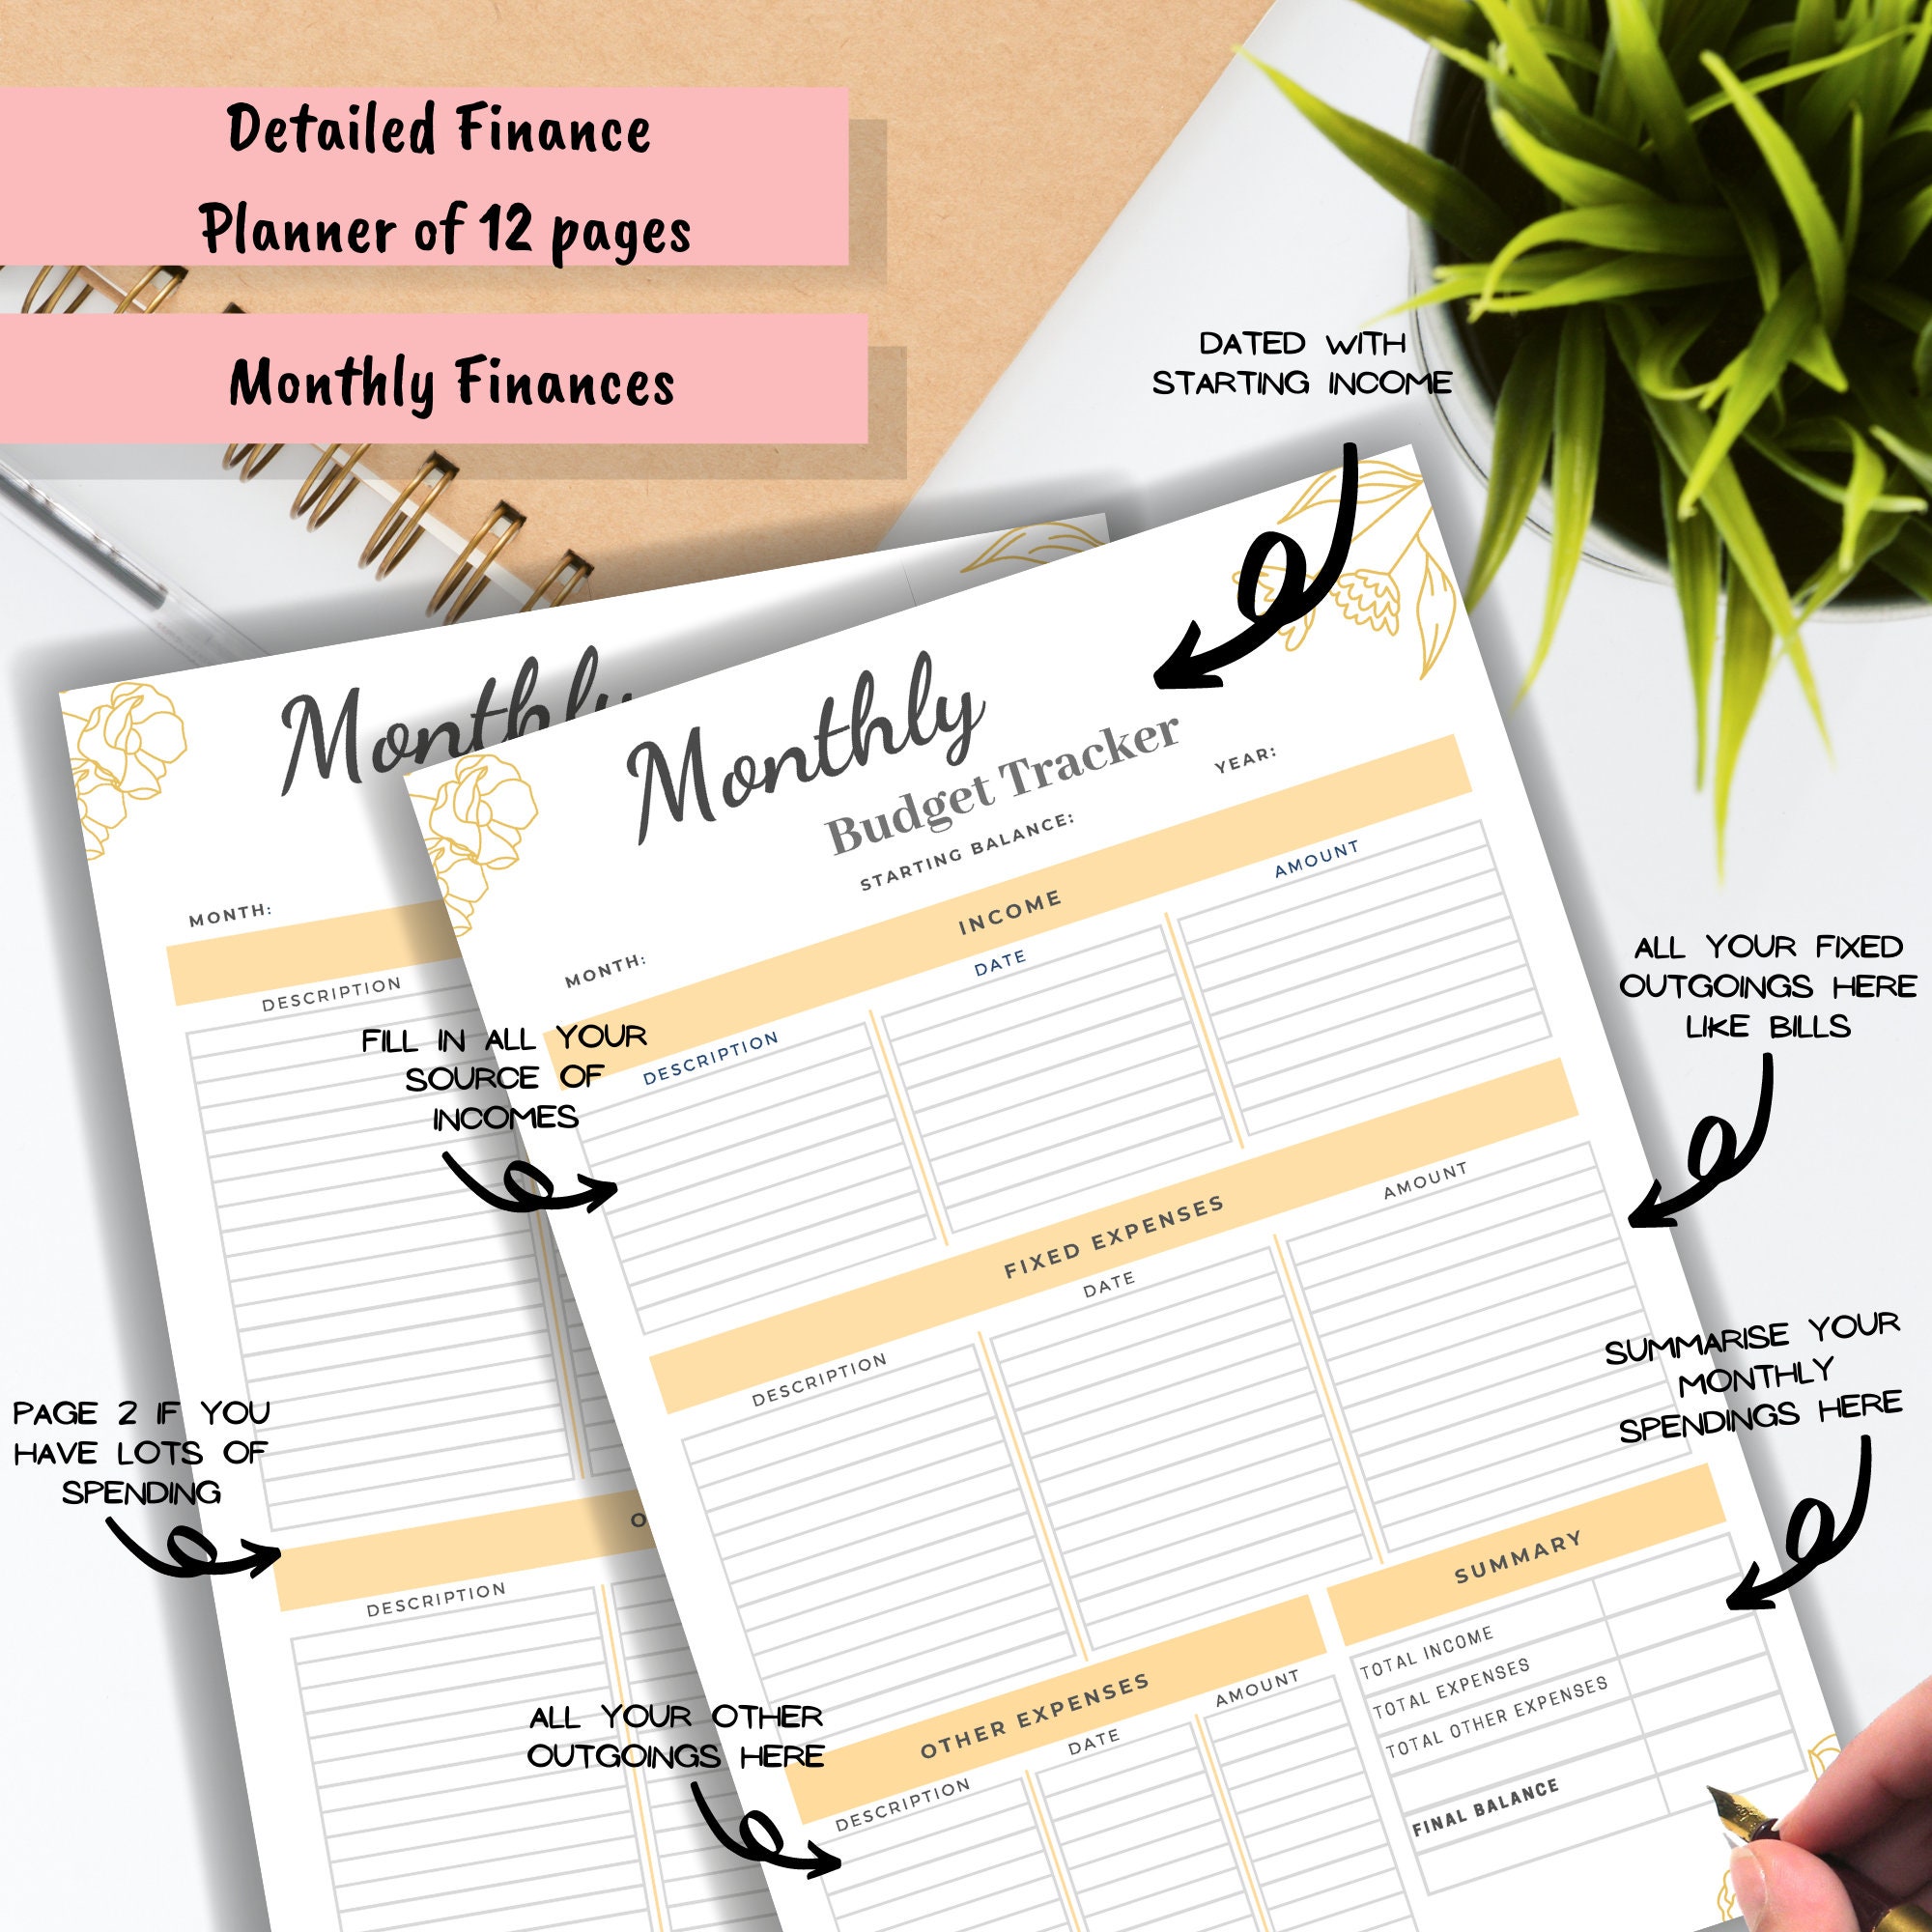
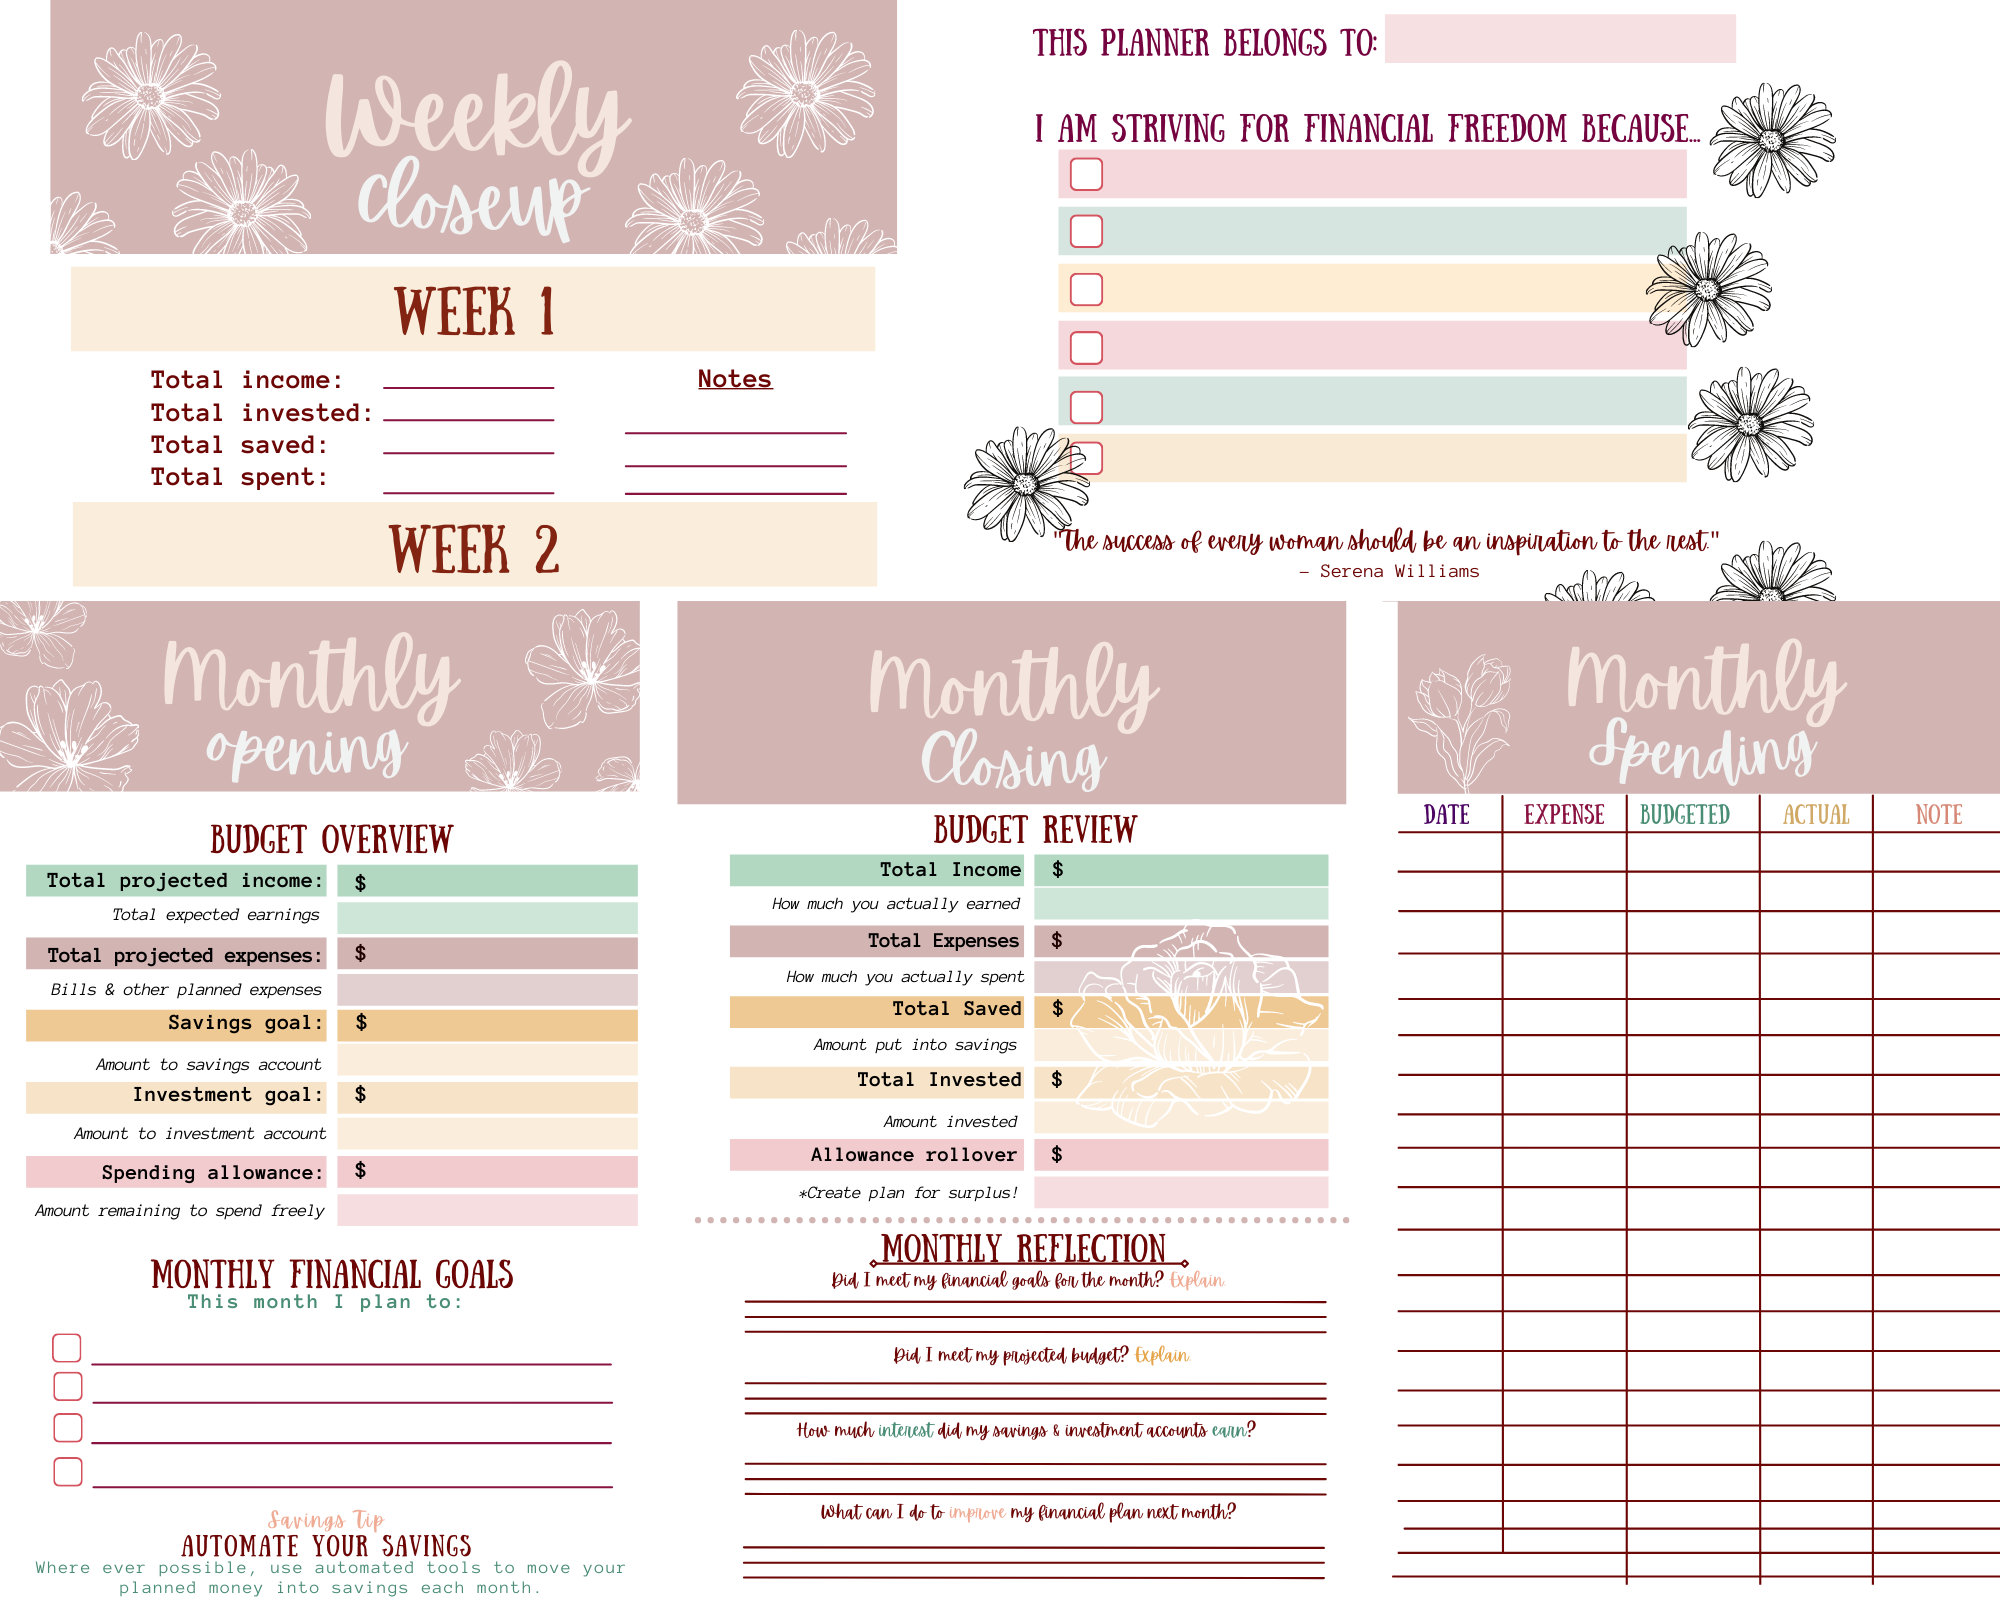
I spent about three years trying to get my own spending tracked consistently before I figured out that the structure matters more than the tool. Most people abandon their finance journal within six weeks because they built something too rigid for how they actually live. The monthly layout for women tends to work better when it accounts for irregular income cycles, cyclical expenses that don't fall on the same dates every month, and the reality that many women still manage the bulk of household budgeting alongside other responsibilities that eat into admin time. The core layout breaks down into five sections that repeat every month: opening balance, fixed expenses, variable spend categories, saving goals, and a closing reconciliation. You set the opening balance once at the start of the month. Fixed expenses go on first because they are non-negotiable and they tell you immediately what you have left to work with. Variable categories come next, organized by frequency rather than alphabetically, which is a detail most templates miss. The saving goals section stays visible at all times so you are not constantly re-deriving how much progress you have made. Reconciliation closes the loop. I built my first version in a Google Sheets workbook and filled it by hand every Sunday evening. It took me about forty minutes each week. After eight months, I started skipping weeks because life got busy, and the whole system collapsed under its own detail. The fix was not adding more columns. It was removing the ones nobody checked. I dropped sub-categories for groceries and dining out and merged them into a single food category with a single weekly cap. That cut my weekly entry time from forty minutes to roughly twelve.
The layout should fit on one screen or one page if possible. When you need to scroll or flip between sheets, you will stop using it. I know because I watched myself do it. A single sheet with color coding by category works better than a multi-sheet workbook with perfect formulas. People respond to visual patterns, not mathematical elegance.
What to Include and What to Leave Out
Include a column for transactions that come outside your normal cycle. Period products, annual subscriptions, birthday gifts, car registrations, and pet meds do not happen on schedule, and if you do not have a home for them, they disappear from your tracking and show up as confusion at the end of the month. I used to lose track of quarterly insurance premiums until I created a notes column for upcoming non-monthly items. That one change reduced my end-of-month surprises from about five per year to zero. Leave out complex categorization rules that require decisions. If you find yourself debating whether a purchase belongs in "home" or "personal care" for more than ten seconds, your categories are too granular. Merge them. Use broad buckets that map to how you actually think about money. Income, fixed costs, variable costs, debt, savings, and discretionary spending are enough for most months. Anything beyond that is usually academic. Another common mistake is tracking every dollar instead of tracking what moves the needle. Receipt-level precision sounds satisfying until you realize that the variance between your planned and actual spend on coffee does not change your financial position. What changes it is whether you stayed within your total variable budget or blew past it. Focus on totals by bucket, not line-item perfection.
Get the Full Details
How to Set It Up Without Overthinking It
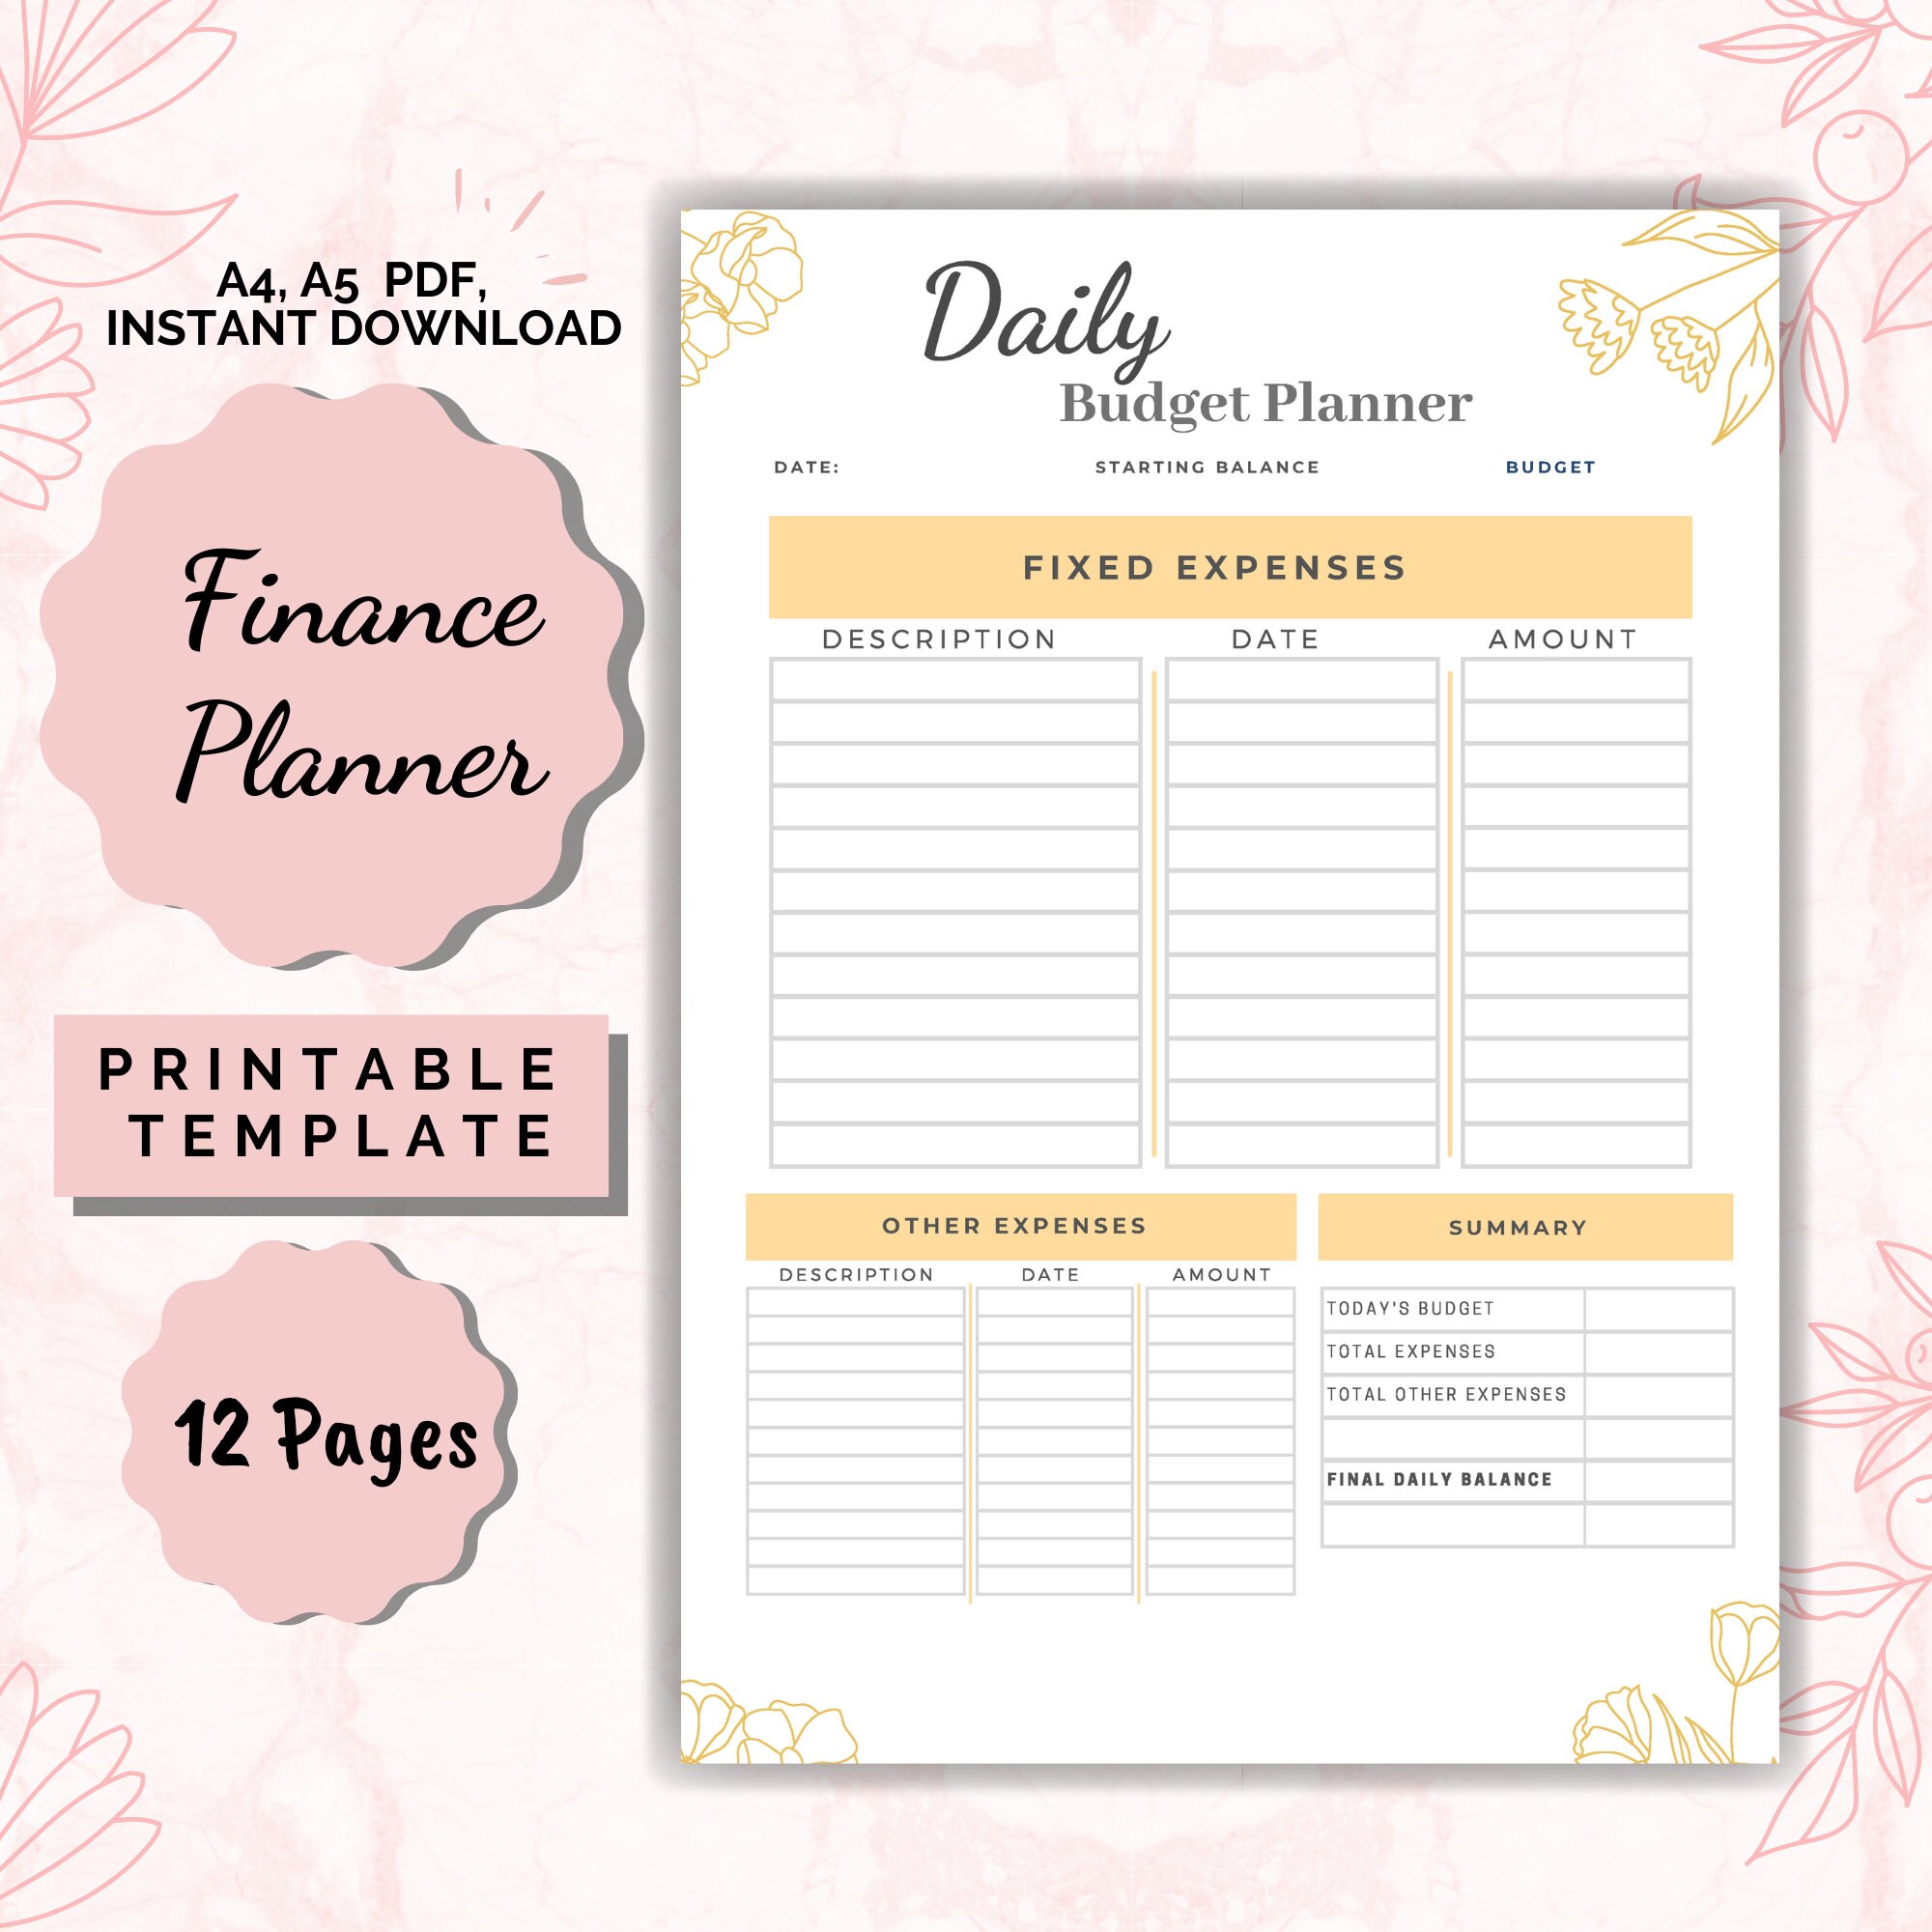
Start with the last thirty days of bank statements. Pull your actual numbers first so the layout reflects reality instead of optimism. Plug them into the five sections I mentioned above. Whatever number shows up as your average monthly spend in each category is your starting baseline. Do not try to cut budgets based on that first month. Use two full cycles before adjusting targets. You need data, not inspiration. Build the layout in the tool you will actually use when you are tired. That is usually a simple spreadsheet or a basic app, not a custom database you spent a weekend configuring. I have seen too many people waste hours building perfect financial systems and then use the paper template instead because it was faster. The best finance journal is the one you maintain when you have three minutes and low energy. If you want something printable, a single page with boxes for each category and a running balance column is sufficient. If you prefer digital, a shared spreadsheet that you can access from your phone works better than a desktop-only file. Accessibility matters more than aesthetics.
Common Pitfalls and How to Avoid Them
The biggest pitfall is setting budgets that assume ideal conditions. Your variable spend will be higher in November because of holidays, higher in January because of resolutions and gym fees, and lower in August if you take a break from eating. Adjust your expectations by month instead of forcing every month to match the same numbers. A flat monthly budget is a flat lie. Another pitfall is ignoring debt payments until the end of the month. Debt should sit inside your fixed expenses section, not hidden in a separate calculator or mental list. If you do not place it next to rent and utilities, you will treat it as optional and then wonder why your balances are not moving. Sometimes the layout itself becomes the problem. I encountered this when my income changed from biweekly to monthly mid-year. The existing template assumed two paychecks per month, which threw off my cash flow tracking for three consecutive months. The workaround was to add a separate income line that showed actual deposit dates rather than idealized pay periods. It took fifteen minutes to modify and immediately corrected the variance readings.
When This Approach Falls Short
A monthly journal layout is not sufficient if your income fluctuates by more than forty percent from month to month. In that case, you need a zero-based system tied to each paycheck rather than a monthly overview. The monthly format also struggles if you carry high-interest debt above ten percent, because the interest compounds faster than a monthly review can address it. In that scenario, prioritize a debt payoff tracker with minimum payments and extra principal columns before you invest time in general budgeting. Some people also find that a monthly cadence is too slow for their anxiety level. If checking in once a month causes panic because problems have already grown, switch to a weekly checkpoint with a monthly summary. The weekly check catches drift early, and the monthly summary keeps the big picture intact. You do not have to choose one or the other.

Where to Get a Ready Layout
You can build the layout in under an hour using a blank spreadsheet. Set up columns for date, description, category, amount, running balance, and notes. Create rows for your fixed expenses at the top, then variable categories below, then savings targets, and finally a reconciliation row at the bottom. That is the entire structure. Free templates exist on several personal finance sites, but I usually advise against copying someone else's design wholesale. Their categories do not match your habits, and adapting a foreign layout takes more effort than building your own from scratch. If you want a starting point without the guesswork, a simple monthly budget template with the five-section structure I described will get you to functional tracking within a week. After that, tweak it until it feels invisible, which is the goal. The best finance journal is one you stop noticing because it has become part of your routine.