Setting Up a Yearly Finance Journal That Actually Sticks
Most people abandon their finance journals within three months because they try to track everything at once. I learned this the hard way back in 2018 when I spent six hours a week manually entering every transaction across three accounts, just to realize my spreadsheet was so cumbersome that I stopped updating it after October. The trick is to keep the entry process under five minutes per day, or you will burn out. Start with a single master ledger, even if you have multiple bank accounts and credit cards. The initial consolidation takes effort but saves you from the administrative tax of reconciling separate books.A yearly finance journal is essentially a chronological record of every financial movement within a twelve-month period, organized by category rather than by source. I used to group entries by which account they came from, but that made quarterly reviews nearly impossible. Switching to a category-first structure changed everything for me. Your categories should reflect how you actually think about money, not some accounting textbook list. If you don't have a category for "subscription drift" where you track those small recurring charges you forgot about, you won't use the system. Here is the structure I use, and it has held up through two tax seasons without a single crisis. Start by setting up your column headers. Date, description, amount in, amount out, category, running balance, and a notes field. That is seven columns. Anything more and you are creating friction. I added a "receipt" column at one point and spent more time photographing receipts than reviewing them. Removed it immediately.
The real workflow happens in the entry process itself. Pick one time each day, preferably right after lunch when your brain is still engaged but not fresh enough to make mistakes, and go through your accounts. Pull the morning's transactions from your banking apps and enter them directly into your journal. Don't wait until Friday. Waiting until the end of the week is where the backlog grows, and suddenly you are facing forty entries on a Sunday night instead of four per day, spread across an entire week. I have lost track of the number of times I caught myself doing the mental math on Friday and realized I had no idea where three hundred dollars went because I had deferred the work. For categorization, use a consistent system. I use a simple tiered approach: primary category like groceries, then a sub-note if needed like farmers market versus supermarket. This gives you enough granularity for meaningful analysis without requiring you to pick between thirty options every time. Most people never use more than eighteen categories consistently. Build your journal around those eighteen. At the end of each month, run a reconciliation. This takes me about twenty minutes. Match your journal balance against your actual account balance. If they differ by more than a dollar, find the discrepancy immediately. Do not carry it forward. A small error left alone for three months compounds into a twenty-dollar gap that takes you an hour to trace.
The Parts People Skip That Actually Matter
Setting up the spreadsheet is the easy part. The hard part is maintaining it, and there are specific friction points that cause most people to quit. One issue is the handling of split transactions. When you buy groceries and also pick up gas at the same store, your card statement shows one charge but it represents two categories. I used to leave these as single entries and figure it out later, which created a slow bleed of category inaccuracies. Now I split them immediately during daily entry. It adds about thirty seconds per transaction but keeps your annual totals honest. Another issue is the treatment of irregular income. If you are a freelancer or have side income, your revenue streams are unpredictable. Early on I tried to wait until income hit and then categorize it properly, but the timing mismatch between when money arrived and when I categorized it created constant confusion about available funds. I now record irregular income the same day it arrives with a temporary category like "uncategorized income" and move it to its proper category during my monthly reconciliation. This way your running balance is always accurate even if the categorization isn't final yet.
Get the Full Details

The biggest mistake I see people make is building a journal that is too detailed for their actual behavior. I once built a system with seventy-two predefined categories and custom formulas that calculated projections. It took me twelve minutes to enter a single day of transactions. Realistic target is three minutes for a normal day with fifteen to twenty transactions. If your system takes longer, simplify it.
What This System Won't Do For You
It will not predict your expenses with any accuracy. If someone tells you their yearly finance tool can forecast your spending with five percent accuracy, they are either selling something or they have not tested it over more than six months. Personal finance tracking is backward-looking by nature. You can spot patterns. You can identify trends. But seasonal variations, unexpected medical bills, and life changes invalidate most forecasts within ninety days. It will not replace professional accounting if you run a business. I tried using my personal finance journal for my small consulting work and ran into problems with accrual tracking, expense allocation, and depreciation that no amount of spreadsheet gymnastics could solve. Once I switched to actual accounting software for the business side and kept the finance journal strictly personal, everything became clearer. Mixing business and personal in the same system creates noise in both directions. Automation has limits. Yes, you can connect your bank accounts through Plaid or similar services to pull transactions automatically. This cuts entry time from five minutes per day to under a minute. But automatic imports fail constantly. Bank feeds drop transactions, categorize things incorrectly, or merge multiple purchases into single line items. I recommend using automation for convenience but verifying the import every single week. I skipped verification for one week during a bank migration and had to manually re-enter forty-seven transactions to fix the errors.
Finance Journal Yearly: A Practical Template Structure
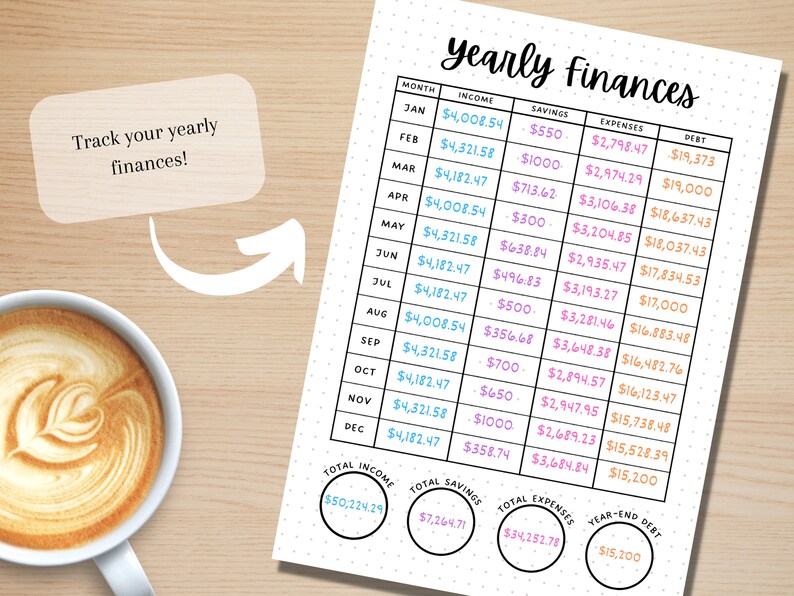
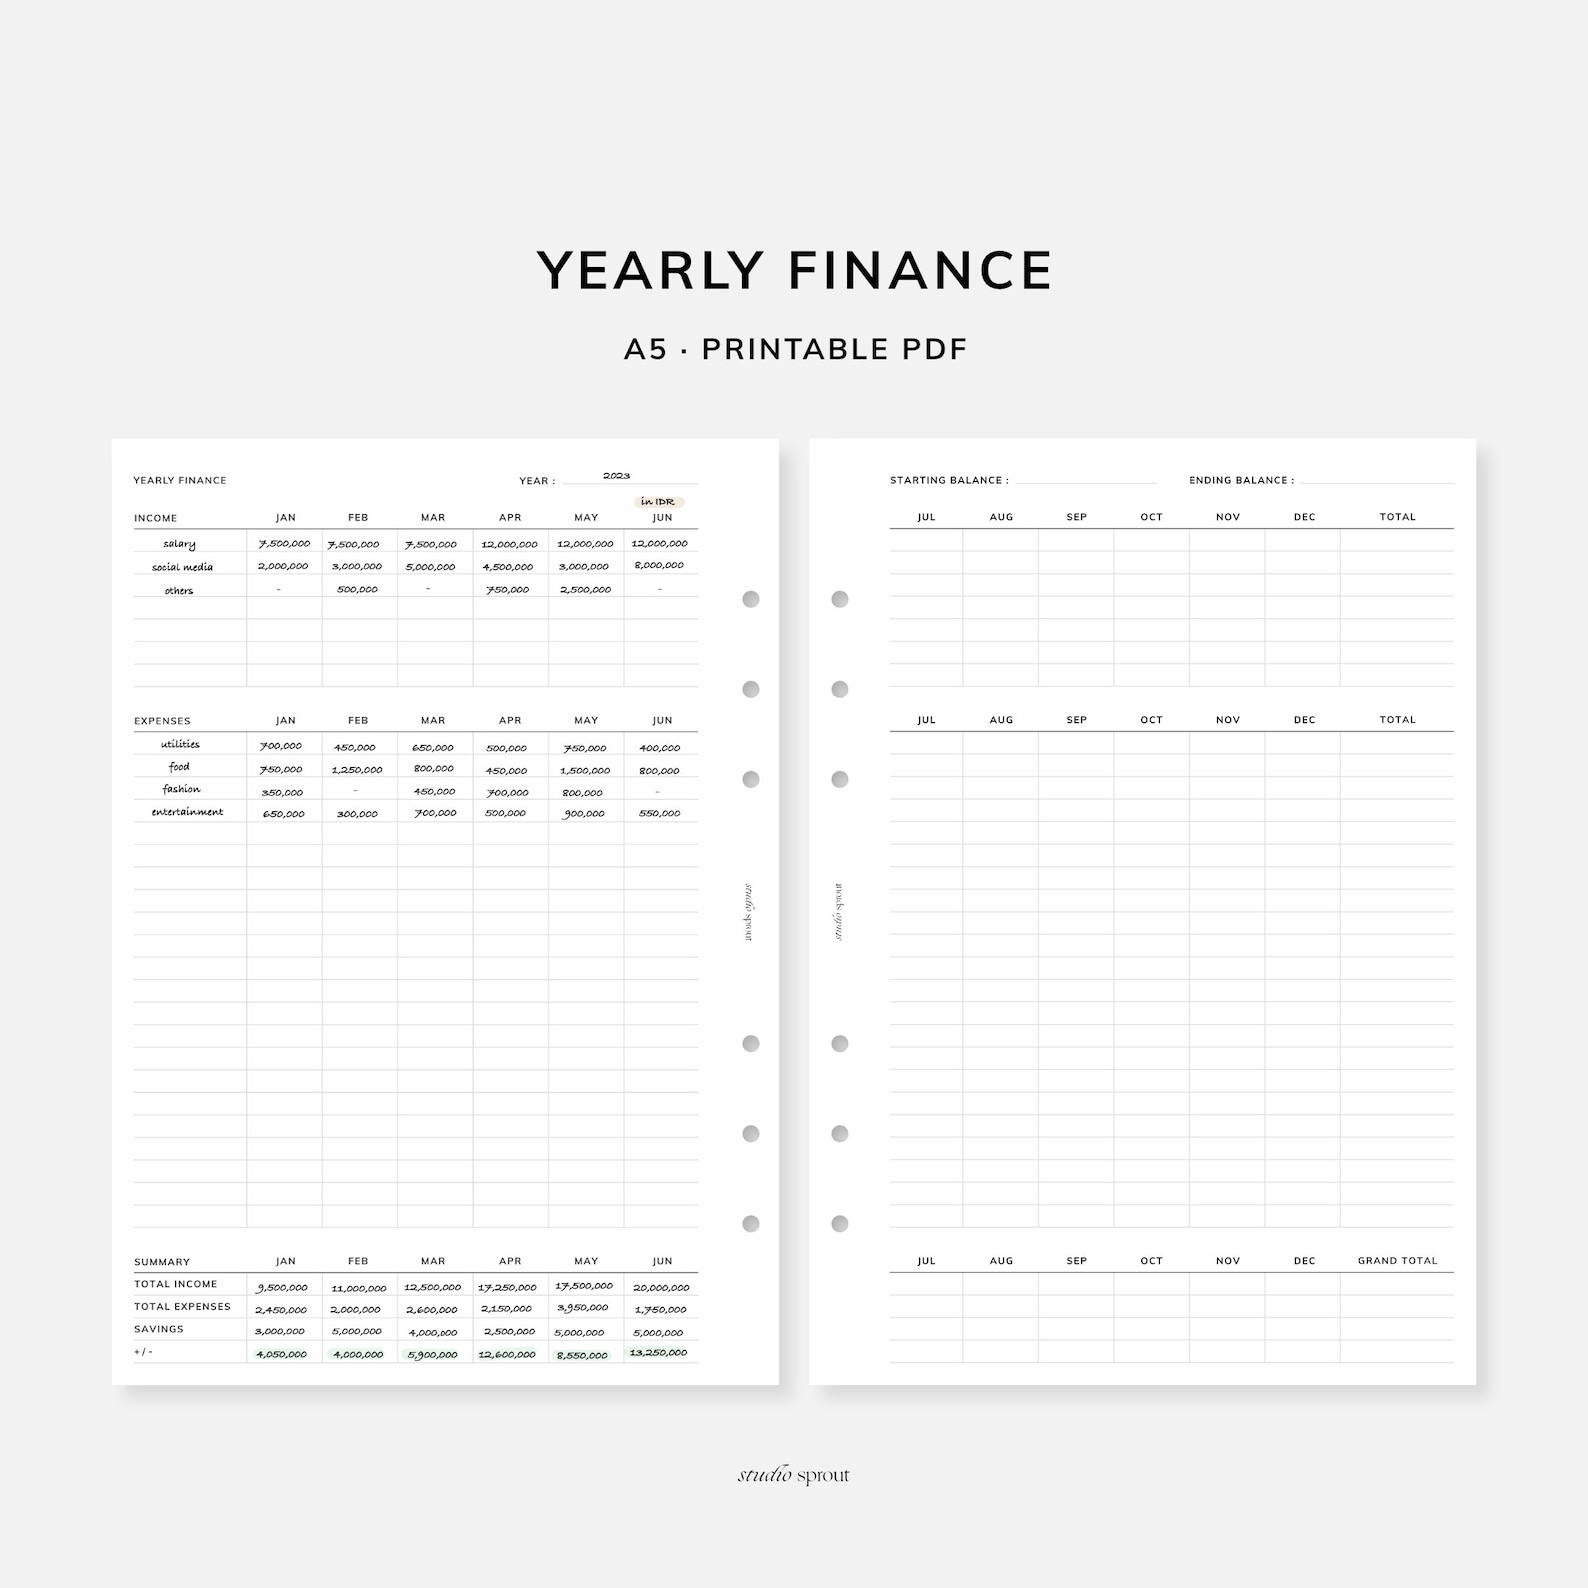
If you want to start today, here is the structure I use and recommend to anyone asking for a starting point. The master sheet contains your daily transactions with the columns I mentioned earlier. Keep it on one continuous timeline. Do not split it by month on separate sheets. Scrolling to different sheets sounds organized but adds friction every time you need to reference a prior month's entry. Your summary sheet sits next to it and pulls data from the master using SUMIFS formulas. Monthly totals by category, year-to-date totals, and a simple variance column comparing actual spending to your targets. The variance column is where most of the value lives. Without it, you are just recording history. With it, you are building a feedback loop.
I set realistic monthly targets based on the previous three months of actual data, not on what you wish your spending looked like. Baseline your targets from reality. Adjust only when your situation changes, not based on monthly performance. The categories that matter most for annual insight are housing, transportation, food, healthcare, debt payments, savings contributions, and discretionary spending. Everything else is secondary. I initially tracked twenty-three categories and found that only eight of them showed meaningful variation year over year. The rest were either fixed costs or noise. Collapse those into broader buckets. One practical detail that took me a long time to figure out: handle taxes as a category at the month level, not at the transaction level. If you have tax withholdings on every paycheck, don't create a separate transaction for each withholding. Sum them by month and enter one entry per month. This reduces thousands of entries down to twelve per year and makes the annual review actually feasible.
The system only works if you do the reconciliation. I know that sounds obvious but I have talked to dozens of people who set up elaborate journals and then never closed the loop. The monthly reconciliation is not optional. It is the step that catches the errors before they become habits. Twenty minutes once a month prevents three hours of detective work once a year. When I look at my current yearly finance journal now, five years into using this system, the value is not in any single month. It is in the pattern recognition that comes from having twelve consecutive months of clean data. I can see exactly how my housing costs shifted when I refinanced. I can trace how my food spending changed after I stopped eating out. I can identify the exact month my transportation costs spiked and backtrack to find the tire purchase I had forgotten. This is retrospective clarity, not predictive power. But clarity is valuable enough on its own. Start simple. Enter daily. Reconcile monthly. Cut categories until you have fewer than twenty. Ignore anything that takes more than three minutes to update. If it breaks your routine, it is too complex. The best finance journal is the one you actually maintain, not the one that looks best on paper.