What You Need to Know About Keeping a Finance Logbook the Old Way
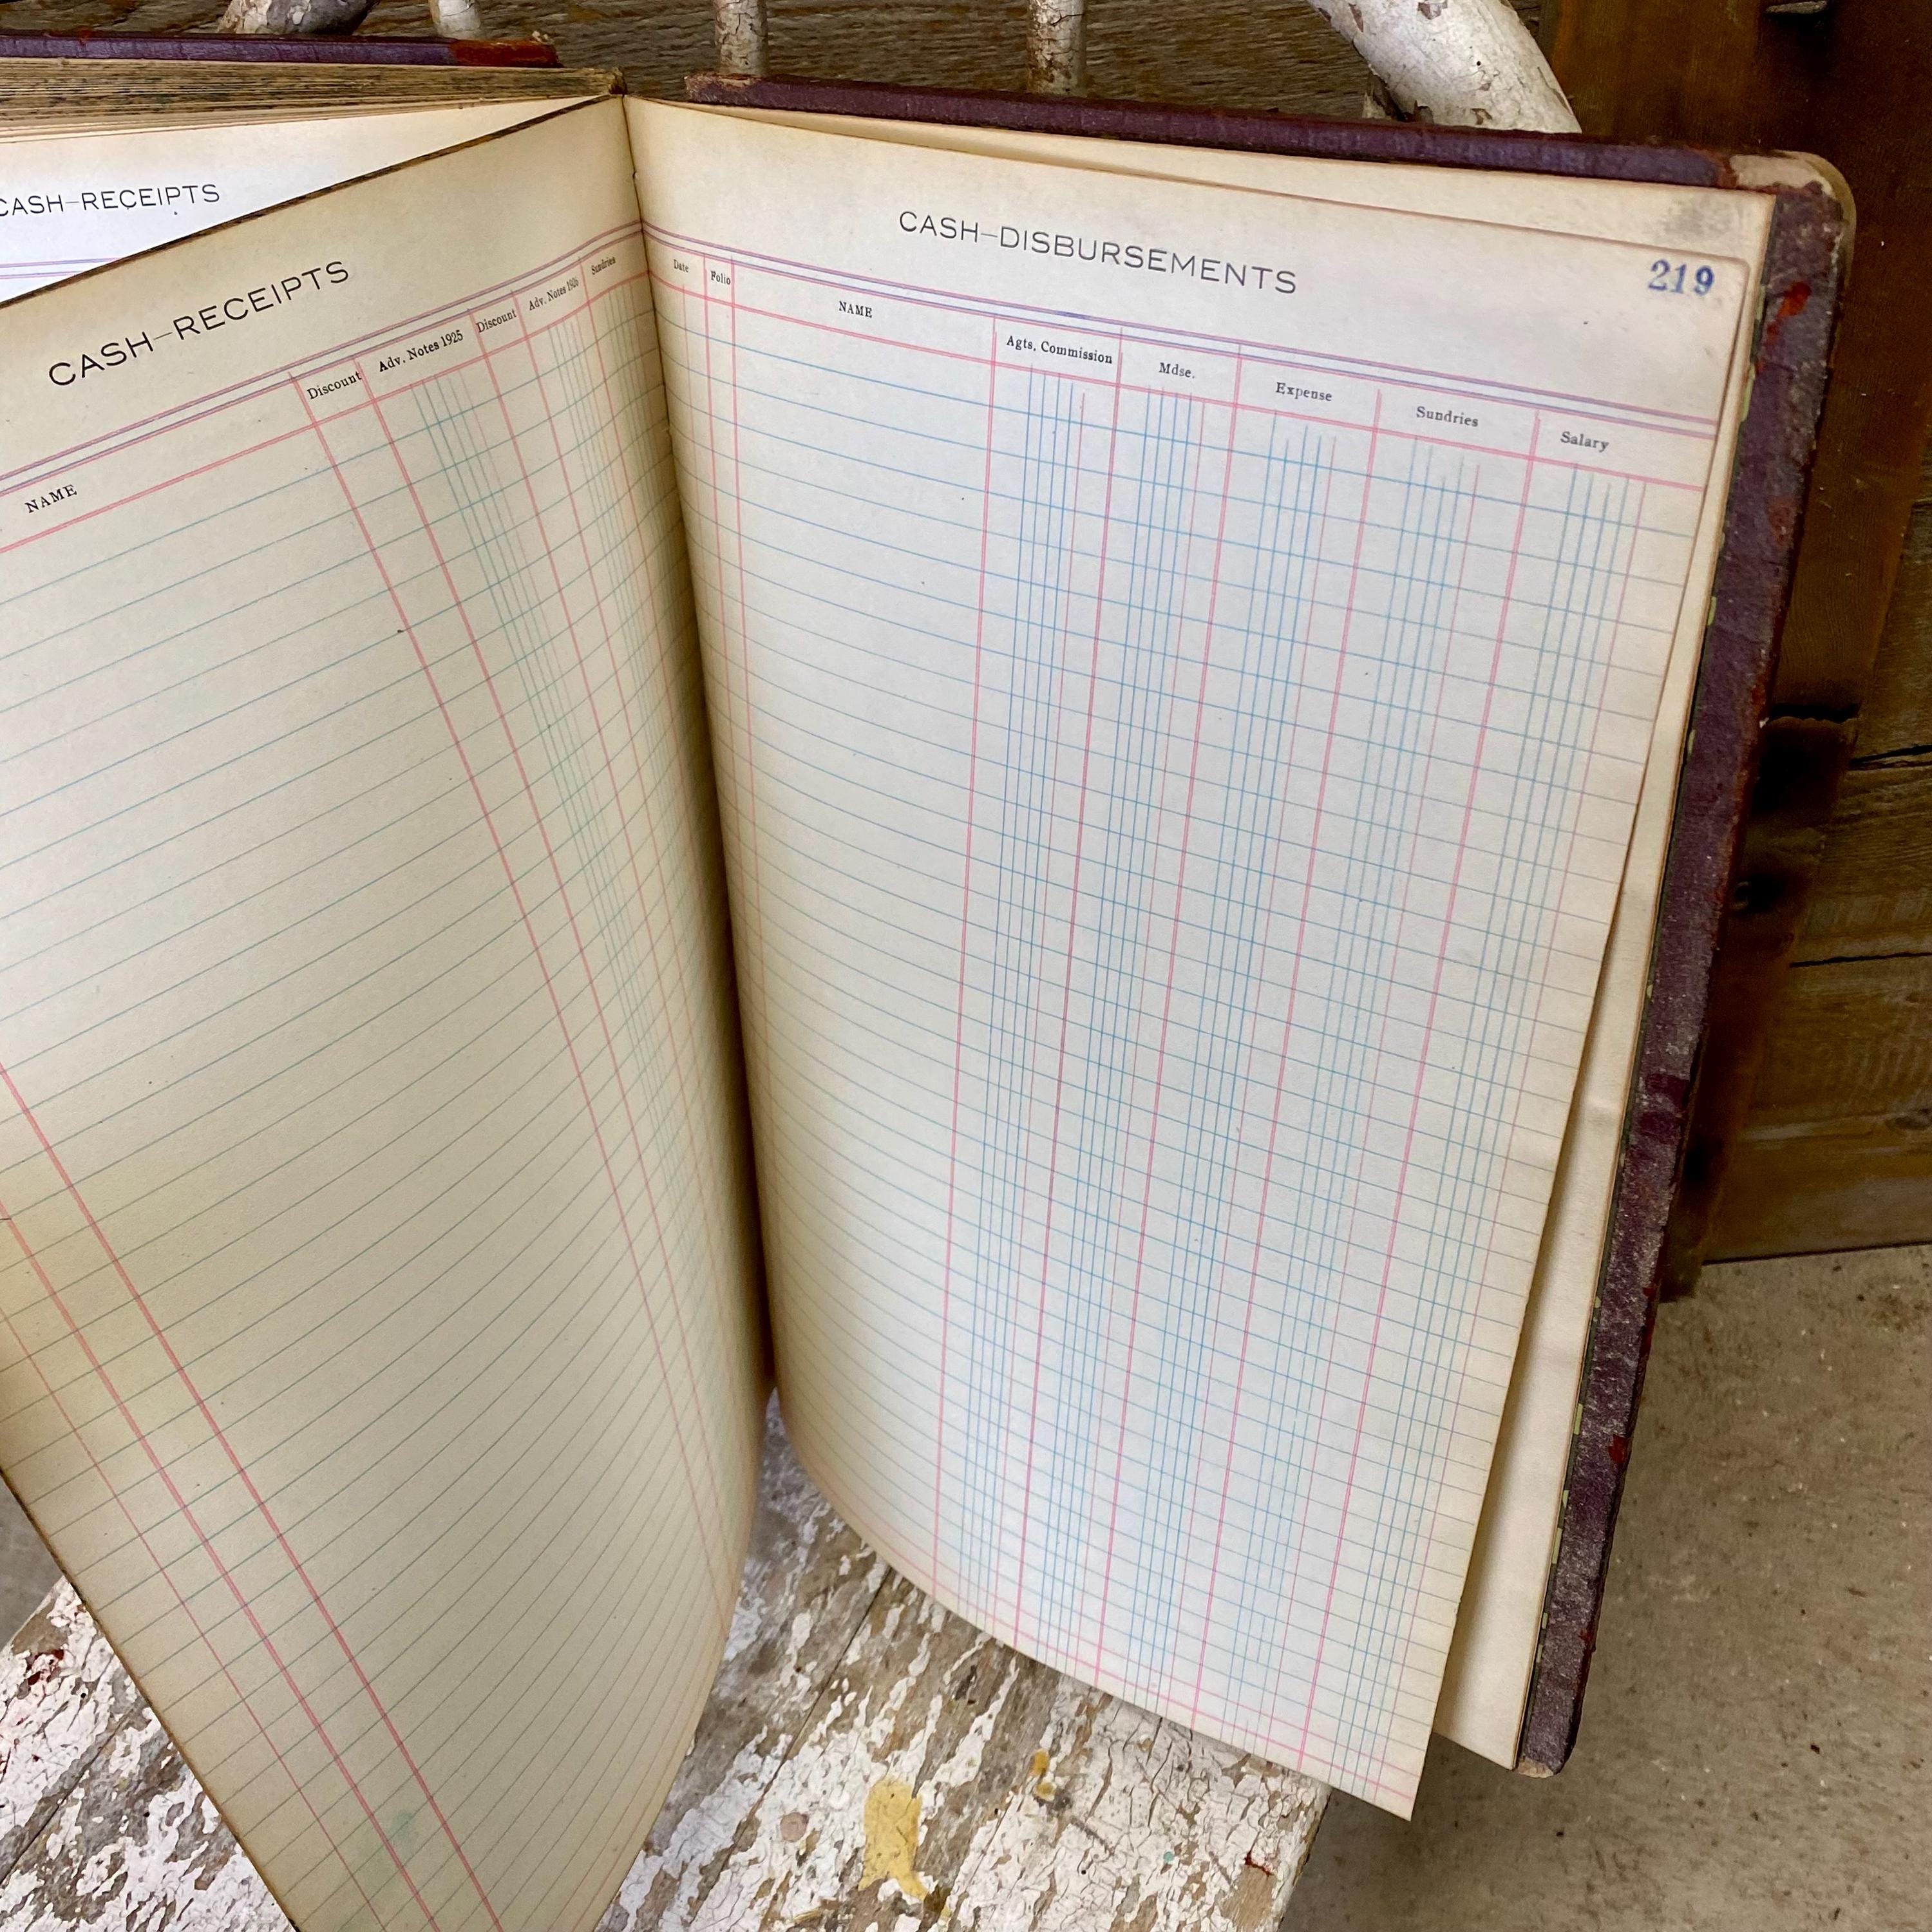
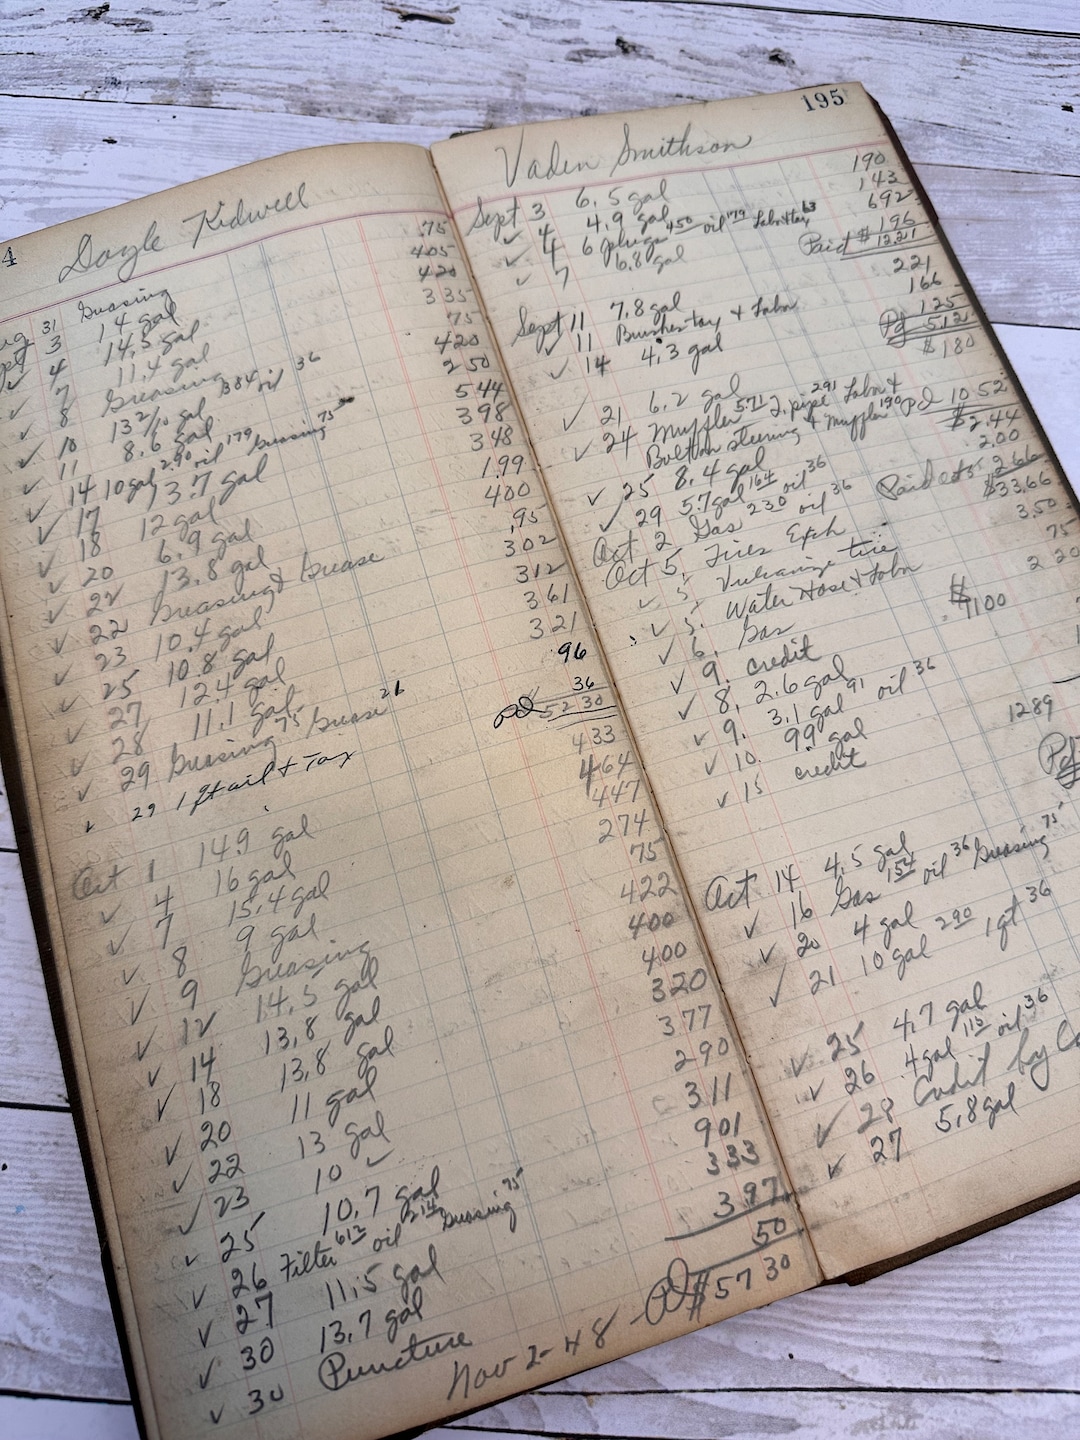
Most people today don't realize how much smoother their financial lives could run if they kept a proper physical logbook. I started using a Finance Logbook Vintage system back when spreadsheets felt like overkill and my bank statements came on paper that actually lasted more than a decade. The approach is simple: every transaction, every note, every weird recurring charge gets written down in a dedicated book by hand. Not in an app. In a book with actual pages. The biggest mistake I see people make is starting with something fancy. They buy a leather-bound book with color-coded sections and abandon it after three weeks because they didn't think through the system first. The one I use now is a plain black notebook with a grid layout. Month on the left page, running entries on the right. Every entry has four fields: date, amount, category, and a memo line for things like "recurring - unsubscribe needed." That's it. Nothing elaborate.
Getting Started With Finance Logbook Vintage
Grab a notebook that lies flat when open. Spiral bound works fine, but a proper stitched binding holds up better long term. I've gone through six books in four years writing in them daily. A pen that doesn't bleed through is non-negotiable; cheap ballpoints leave ghost images on the opposite page and make flipping back through old months a pain. I use a Pilot G2 0.7mm and haven't had an issue yet. Set up the first page with a legend. Assign a letter or short code to each spending category you actually use. Food, transport, subscriptions, utilities, healthcare, miscellaneous. Don't overcomplicate this. When I first started, I used twelve categories. By month three I was skipping the ones I rarely hit and the whole system felt heavier than it needed to be. Four or five categories is enough for most people. You can always expand later. Write every single transaction the same day it happens. Not the next day. Not when you feel like it. This is where the system breaks for most people. A Finance Logbook Vintage approach only works if the habit sticks, and the habit only sticks if the barrier to starting each entry is as close to zero as possible. Keep the pen next to the book at all times. If you have to search for the book and the pen separately, you're already losing.
What Actually Happens When You Do This Right
After about six weeks of consistent entry, something shifts. You start noticing patterns you never would have caught otherwise. That subscription you forgot about, the one charging you every month for three years because you never cancelled it, shows up clearly when you're looking at twelve months of written records instead of scrolling through a bank app. The mental friction of physically writing down each expense also changes your relationship with spending in a way that digital tracking never does. It feels real when you write it down. I also keep a separate section at the back for monthly totals. At the end of each month, I tally up spending by category and write the numbers down. This takes about twelve minutes. Doing it manually rather than letting an app calculate it forces you to actually look at where your money went instead of hiding from it behind a pie chart. The pie chart approach works for some people. For me it just felt like checking a grade I didn't want to see. There is a real limitation here that nobody talks about enough. Physical logbooks are vulnerable to loss, damage, and time. If your house floods or you misplace the book, you lose everything. I solved this by keeping a separate digital backup. Every Sunday night I take a photo of that week's entries and store them in a folder organized by year and month. Takes about eight minutes. It's not elegant but it's effective and it keeps me from panicking when I dropped last year's book in coffee and had to photocopy the relevant pages anyway.
Get the Full Details

Advanced Details Most People Skip
One thing that catches people off guard is how hard it is to track irregular income with a logbook. Salary comes in on a predictable schedule, but freelance payments, side hustle money, tax refunds, gifts, and the occasional random deposit make the system uglier faster than you'd expect. I solved this by using a different colored pen for income entries. Red ink for anything that isn't a regular paycheck. It makes the visual separation instant and stops me from accidentally double-counting or forgetting to include non-regular deposits when I do my monthly totals. Another detail that matters more than it should is the spacing. Leave room. Write small enough that two transactions fit on one line if needed, but not so cramped that you can't read your own handwriting six months later. I learned this the hard way when I tried to save space on a trip and spent twenty minutes one evening trying to figure out whether a $47 charge was a restaurant bill or a taxi fare because I'd written both on the same line with a pencil. Pencil is another thing to avoid. Smudges happen. You will regret it. If you decide this approach isn't for you after a few months, that's fine. The system has a real bottleneck: it doesn't scale well if you have more than thirty transactions per day. I know people who run businesses and keep logbooks and they make it work by consolidating business expenses into a separate book with a much looser categorization system. But for personal finance with a typical household or individual, a single book handles everything without friction.
The cost of a basic logbook and pen is under twenty dollars total. The time investment is roughly ten minutes per day once the habit forms. Most people underestimate how quickly that becomes automatic. After the second month, writing your daily entries takes maybe three minutes. The rest of the time is spent reading and remembering, not deciding what to write.