Working Through Financial Statement Analysis Case Studies
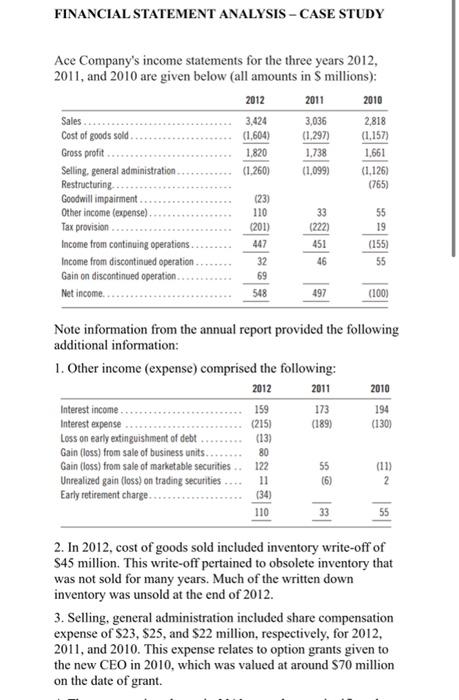
Most people approach these case studies backwards. They look at the numbers first and try to build a story from ratios. That's the wrong starting point. You need to understand the business model before you touch a spreadsheet. I learned that the hard way during my second year when I spent six hours building a detailed five-year DCF model for a manufacturing company case, only to realize the actual problem was a single lease obligation they'd buried in off-balance-sheet arrangements. The financials were fine. The footnote disclosures were where everything fell apart. The actual mechanics of these problems follow a fairly standard pattern, but the execution is where most people lose points or make actual mistakes in practice. Start by pulling the three statements into a single workbook. Income statement, balance sheet, cash flow statement. Don't touch ratios yet. Just get everything in one place with consistent formatting and matching fiscal years. If the case provides comparative periods, lay them out side by side so you can see year-over-year movement at a glance. This alone cuts your analysis time significantly compared to jumping straight into formulas. Next, do the horizontal analysis. Look at every line item across the periods provided. Find what changed significantly and flag it. A 40% increase in accounts receivable while revenue only grew 12% is a signal worth investigating. A 15% drop in cost of goods sold while inventory stayed flat is another. These are your entry points for deeper work.
Common Approaches and What Actually Works
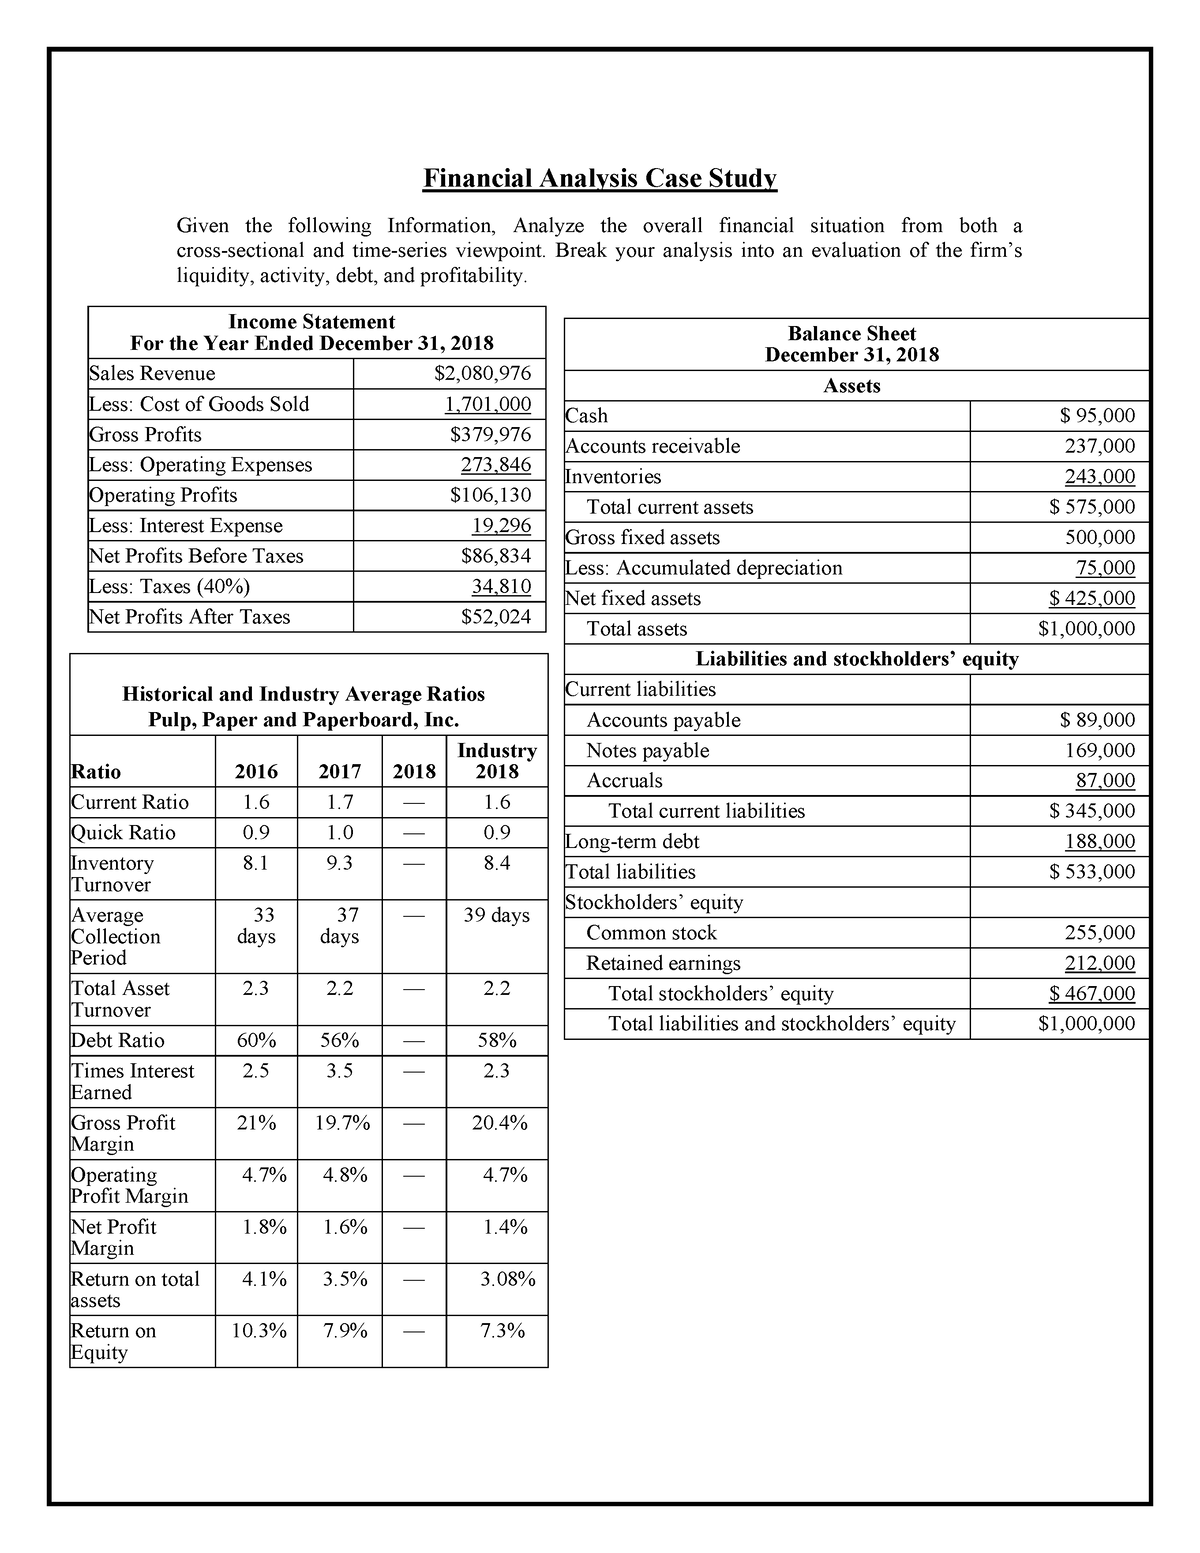
Vertical analysis comes after. Express every line item as a percentage of revenue on the income statement and as a percentage of total assets on the balance sheet. This normalizes everything and lets you compare companies of different sizes. It also reveals structural shifts. If gross margin went from 38% to 31% between two years, that's more meaningful than looking at absolute dollar changes alone. Ratio analysis is where students usually over-index. Yes, you need liquidity ratios, profitability ratios, leverage ratios, and efficiency ratios. But calculating twenty ratios and presenting them in a table without context is worthless. Pick the five or six that matter for the specific industry and question being asked. For a retail case, inventory turnover and gross margin tell you more than debt-to-equity. For a utility company, leverage ratios and interest coverage are far more relevant than days sales outstanding. I always recommend building a small cheat sheet before you start. Write down the key ratios for the industry you're analyzing, along with typical benchmarks. So you know what normal looks like. A current ratio of 2.0 might look healthy in one sector and dangerously low in another. Without benchmarks, you're just naming numbers without interpreting them.
The Parts People Mess Up
Cash flow statement reconstruction is where most people struggle, and it's also where you'll find the real answers. The indirect method starts with net income and walks through adjustments. If a case gives you the balance sheet and income statement but not the cash flow statement, you can reconstruct it. Start with net income, add back non-cash expenses like depreciation and amortization, then adjust for changes in working capital. An increase in accounts receivable is a use of cash. A decrease in accounts payable is also a use. These sign conventions trip people up constantly. One edge case I ran into recently involved a company that had been acquiring other businesses throughout the period. The balance sheet showed a massive jump in goodwill and intangible assets, which looked like poor asset management until I traced it to acquisition activity in the cash flow statement under investing activities. The underlying operations were actually improving. Without looking at the investing section and reading the footnotes about acquisitions, you'd have concluded the company was overpaying for assets and mismanaging its balance sheet. Always cross-reference the cash flow statement with the notes to the financial statements. That's where the accounting choices live. Another common trap is ignoring the quality of earnings. A company can report strong net income while operating cash flow is consistently negative. This usually means revenue is being recognized aggressively or expenses are being deferred. Check the relationship between net income and operating cash flow over multiple years. If net income is growing steadily but operating cash flow is flat or declining, that's a red flag regardless of what the ratios say.
Get the Full Details
Building the Actual Analysis
Once you've done the preliminary work, structure your case around questions. Most academic and professional cases ask you to evaluate financial health, assess creditworthiness, or determine valuation direction. Frame your analysis around those questions rather than presenting a generic overview. Answer the specific thing being asked with evidence from the numbers you've already pulled together. For profitability, look at trends in gross margin, operating margin, and net margin separately. If gross margin is stable but net margin is declining, the problem is in operating expenses or interest, not in the core business. That distinction matters for recommendations. For liquidity, don't just calculate the current ratio. Look at the quick ratio and the cash ratio. A company might have a decent current ratio because it's sitting on unsold inventory that's about to become obsolete. The quick ratio strips that out and gives you a clearer picture. Leverage analysis requires understanding the cost of debt relative to the return on assets. If a company is borrowing at 8% and earning 5% on its assets, adding more debt destroys value even if the leverage ratios look manageable. Return on equity can look impressive under high leverage without indicating actual operational improvement. That's the DuPont framework in practice: break ROE into margin, turnover, and leverage components to see which driver is actually responsible for the result.
When This Method Breaks Down
Financial statement analysis has real limitations that people don't always acknowledge. Historical financials are backward-looking by nature. They tell you what happened, not what will happen. A company can have perfect ratios and still fail because of a regulatory change, a new competitor, or a disrupted supply chain. The numbers don't capture competitive position or management quality directly. Accounting choices also distort comparisons. Different depreciation methods, inventory valuation approaches, and revenue recognition policies can make identical businesses look very different on paper. Two companies in the same industry might report different gross margins simply because one uses FIFO and the other uses LIFO for inventory costing. Adjusting for these differences is possible but time-consuming and often requires assumptions you can't verify. If you're working with a company that has significant off-balance-sheet items, complex derivative positions, or multiple segments with different economics, standalone financial statement analysis becomes less reliable. In those situations, you need supplementary data: segment reporting, management discussion and analysis sections, industry reports, and sometimes primary sources like customer contracts. The financial statements are the starting point, not the destination.
Practical Workflow That Saves Time
Here's how I structure my actual workflow when I get a new case. I spend the first fifteen minutes just reading through all the provided materials without touching any calculations. I skim the income statement, the balance sheet, the cash flow statement, and any notes that seem relevant. I'm looking for anomalies and connections, not building models yet. Then I set up the workbook with the three statements side by side for all available periods. Horizontal and vertical analysis takes about twenty minutes. Ratio calculations take another ten to fifteen depending on complexity. The remaining time goes into writing the interpretation and connecting the numbers back to the actual business situation. This approach usually gets me a complete, defensible analysis in under an hour for a standard case. The alternative is spending three hours calculating ratios and producing something that doesn't actually answer the question being asked. Speed comes from discipline in the ordering, not from cutting corners on the analysis itself. If you want a Financial Statement Analysis Case Study Solution to reference for format and structure, look for examples that show the reasoning process rather than just the final answers. The calculation steps are mechanical. The judgment calls about which ratios matter, how to interpret conflicting signals, and when to dig into the footnotes are what separate competent analysis from adequate work. Practice identifying what each number is actually telling you about the underlying business before you worry about getting the final recommendation exactly right.