Why People Mess This Up
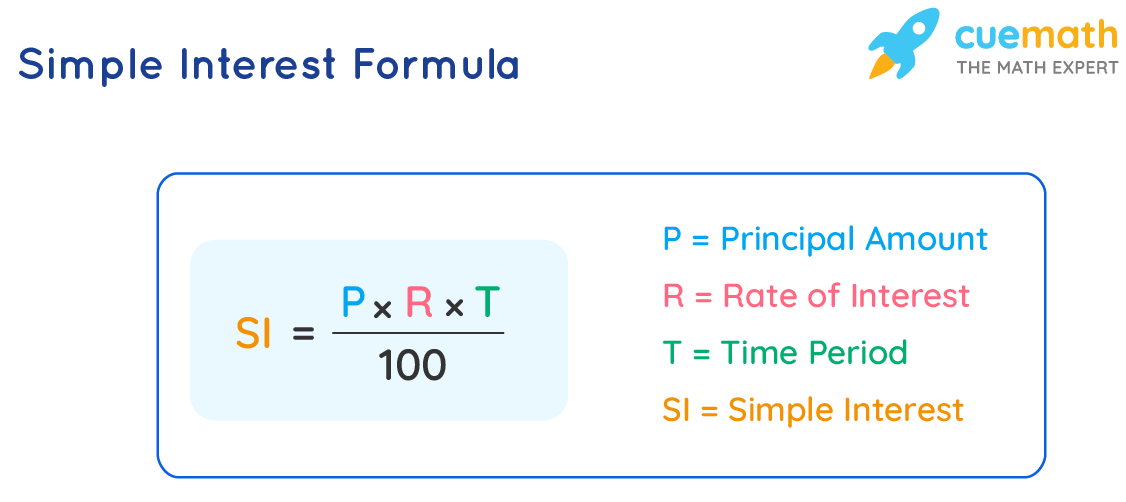
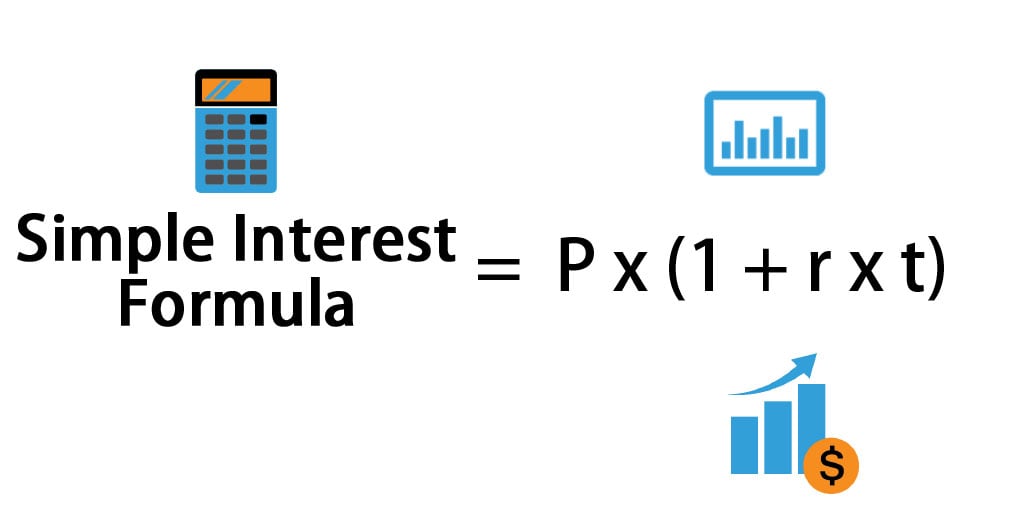
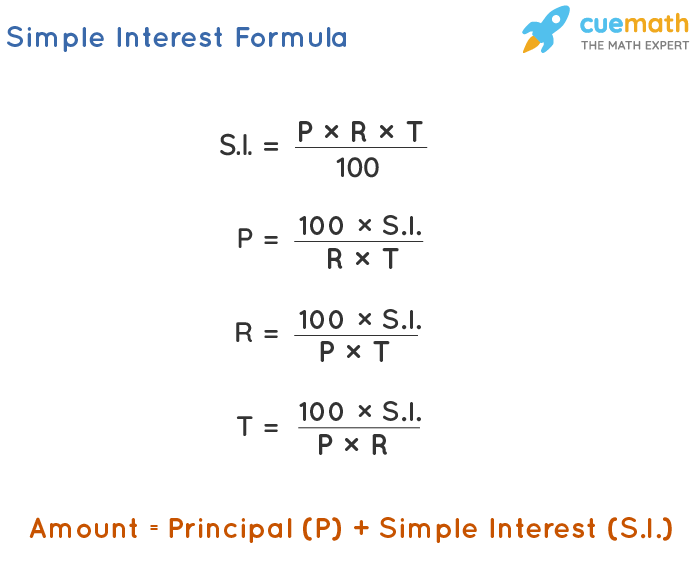
The Formula For Simple Interest is I = P × R × T. That's it. Nobody needs a paragraph of context before that. But every semester I see students lose points because they treat the formula like it's magic instead of arithmetic, so I'll explain what actually goes wrong and how to avoid it. P is the principal, meaning the starting amount of money. R is the rate, but it has to be in decimal form. T is the time in years. Multiply them together and you get the interest only, not the total balance. The rate conversion is where most people fold. If the problem says 5 percent, you write 0.05, not 5. I've graded enough papers to know that putting 5 directly into the formula gives you an answer that's a hundred times too large and nobody catches it because they never check if the number makes sense.
Working Through a Real Example
Say you lend someone $2,000 at 6 percent annual interest for 3 years. Plugging in: I = 2000 × 0.06 × 3. That gives you 360 in interest. Total repayment would be 2,360 if it's a simple loan structure. Straightforward. Now let's make it slightly messier. You're dealing with a rate that comes as 4.75 percent and the time period is 8 months. The rate becomes 0.0475. The time needs to convert to years, so you divide 8 by 12, which gives roughly 0.6667. Plug those in and you're working with decimals on both sides. This is where people second-guess themselves unnecessarily. You just multiply straight through.
When This Formula Breaks Down
Simple interest only applies when interest doesn't compound. That's not a limitation of the math, it's a limitation of when the model fits reality. Most consumer loans, car loans, and credit cards use compound interest. Using the simple interest formula on those will give you the wrong answer and you won't know it until the numbers look suspiciously small compared to what you're being charged. I ran into this with a small business client who was comparing two loan offers. One advertised 7 percent simple interest over 5 years and the other quoted an effective rate that looked close but was actually structured with monthly compounding. The simple interest formula told me the first loan would cost roughly 35 percent of the principal in interest total. The compounded loan, despite appearing similar on the surface, would cost about 41.5 percent. That gap matters when you're talking about real money.
Get the Full Details
A Practical Shortcut That Actually Helps
If you need to calculate interest across multiple different time periods quickly, set up a small table. Principal stays the same row. Rate stays the same row. Time columns change. This cuts the calculation time down from something like 10 minutes of back-and-forth to maybe 2 minutes when you have several scenarios to compare. It also makes it obvious when a number looks wrong because everything sits side by side. First, forgetting that the rate must be annual unless the problem explicitly states otherwise. A quarterly rate requires a different approach entirely. Second, using the wrong time unit. Some problems give days instead of years, and you need to decide whether to use a 360-day or 365-day year depending on the convention being applied. In academic settings, 360 days is still common for simple interest calculations. In actual banking practice, it varies by institution and jurisdiction. Third, adding the interest back to the principal and then calling it done without checking whether the question asks for interest only or total amount. These are different answers and both show up on tests regularly.
Bottom Line
The formula itself is three multiplications. The hard part is always the setup: getting the rate into decimal form, getting time into years, and knowing whether the situation actually calls for simple interest or whether you need a compound formula instead. If you nail those three things, the arithmetic is trivial. If you skip them, you're doing extra work for no reason.