How Home Improvement Loans Actually Work (And Why Your First Estimate Will Be Wrong)
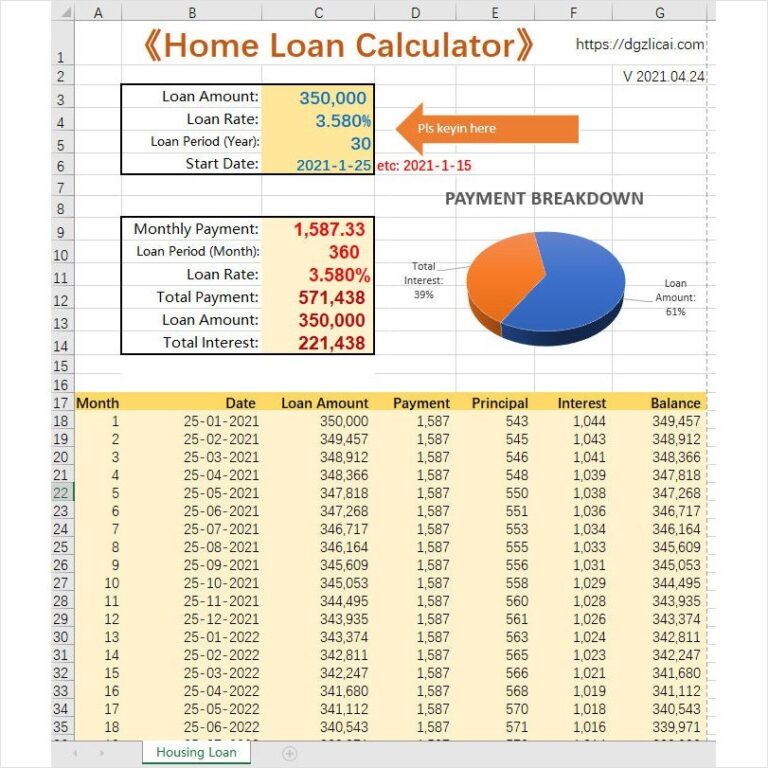
I've watched people fill out these calculators at 11pm on a Tuesday, expecting a clean number. It never works out that way. A Free Home Improvement Loan Calculator gives you a starting point, not an answer. That's the part nobody puts in the marketing copy. The output is a projection based on the numbers you feed it, and if those numbers are rough guesses, the result is useless. Here's how the math actually sits underneath these tools. You need four inputs: the principal amount, the annual interest rate, the loan term in years, and whether payments are monthly. The standard amortization formula compounds interest over the life of the loan. Every payment you make pays off accrued interest first, then chips away at the principal. Early in the term, the split leans heavily toward interest. This is called the front-loaded interest curve, and it's why people who pay extra in year two barely move the needle on their total balance. I learned this the hard way when a homeowner used a calculator to lock in a $45,000 renovation loan at what looked like a solid 6.75% APR for 72 months. The calculator showed roughly $702 per month. He signed. Three months later, the lender disclosed that the 6.75% was a purchase rate, not the APR, and the actual APR was 8.9% once origination fees, points, and mortgage insurance were folded in. The real payment was $789. He was short about $87 a month and had already spent his contingency budget.
Using a Free Home Improvement Loan Calculator Without Wasting Time
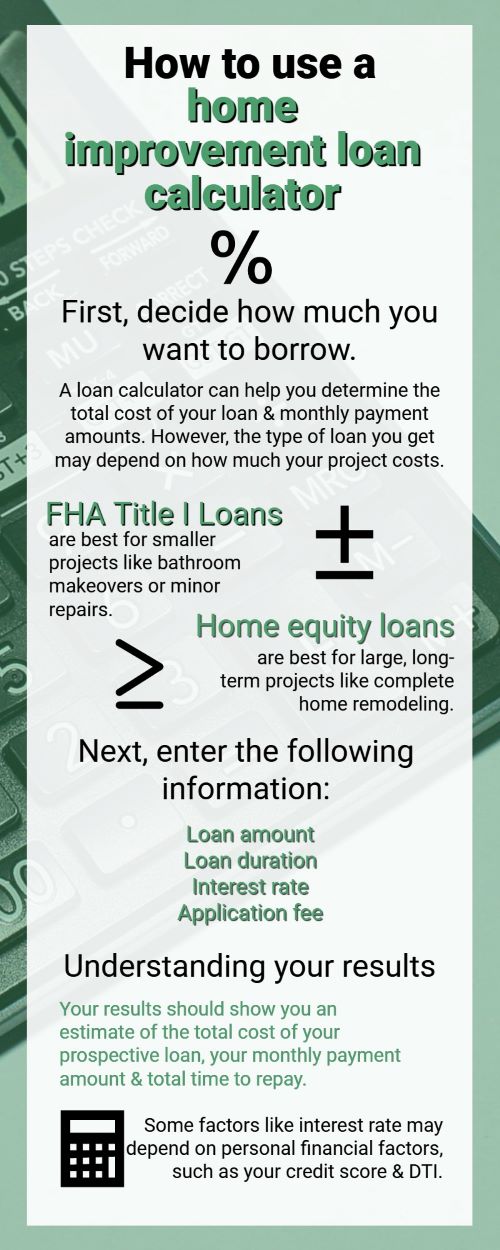
The process itself takes about ten minutes if you have your documents ready. First, pull your credit score range from a free annual report. Lenders tier home improvement loans aggressively across score bands. A 15-point swing between 680 and 695 can shift your offered rate by half a percent or more, which on a $30,000 loan over five years is roughly $120 in extra interest. Not life-changing, but worth knowing before you shop. Next, gather your debt-to-income ratio. Take your total monthly debt payments, divide by your gross monthly income, and round down. Most lenders cap at 43% for conventional home improvement loans, though some portfolio lenders go to 50%. If you're over 43%, the calculator might still spit out a number, but you'll likely get rejected at application. The tool can't simulate lender credit policy. Run the calculation with at least three different rate scenarios. Use the lowest rate you've been pre-qualified for, the average rate shown on comparison sites, and a worst-case rate five percentage points higher. This tells you the range you're working with. Most people only run one scenario and treat that single number as fact. It isn't fact. It's an estimate based on assumptions.
I also keep a spreadsheet alongside any calculator. I list the loan amount, rate, term, monthly payment, total interest paid, and total cost of the loan. Then I add a column for the effective rate after closing costs. Origination fees for home improvement loans typically run 1% to 6% of the loan amount. On a $50,000 loan at 3% origination, you're paying $1,500 just to open the account. That fee rolls into the balance on some products and gets paid upfront on others. Either way, it raises your effective cost of borrowing by roughly 0.3 to 0.8 percentage points depending on the term. A calculator won't show that unless you enter the fee as part of the principal or adjust the rate manually.
Get the Full Details
Counter-Intuitive Details Most Guides Skip
The first thing that trips people up is that home improvement loans come in two fundamentally different shapes, and the calculator output looks nearly identical for both until you read the fine print. A home equity loan is a second mortgage. It's secured by your property. The rate is lower, but defaulting risks foreclosure. A personal renovation loan is unsecured. The rate is higher, but your house isn't collateral. The calculator uses the same formula for both, so the monthly payment will look the same on paper for the same principal and rate. In reality, the unsecured version might carry a rate 2.5 percentage points higher, which changes everything. The second thing people miss is the difference between APR and nominal rate. APR includes certain fees and gives you a more realistic picture of what the loan actually costs. But some lenders advertise the nominal rate to look competitive, then bury the fees in the closing disclosure. If you're comparing two loans side by side, always use APR, not the quoted rate. A $35,000 loan at 7.2% APR with no fees versus one at 6.9% nominal rate with $1,200 in points will have very different total costs over five years, and the cheaper-looking rate is the more expensive loan.
When These Calculators Completely Fail You
There are three situations where an online calculator is essentially decoration. The first is variable-rate loans. If your rate adjusts after two years based on the prime index plus a margin, the calculator's fixed-payment output is wrong from month twenty-five onward. You'd need a separate projection for the reset period, and even then, the new payment depends on where rates land at that future date, which is impossible to know accurately. The second is loans with prepayment penalties. Some fixed-rate home improvement loans charge a penalty if you pay off the balance within the first two to three years. The penalty is usually two to six months of interest. This doesn't show up in any standard calculator. If you plan to refinance or sell the home within that window, the penalty could add $800 to $2,400 to your effective cost, which wipes out the savings from a lower rate. The third is interest-only periods. Some contractors push financing that lets you pay only interest for the first twelve months while the work gets done. The calculator might show you the interest-only payment, which looks affordable. But once the interest-only period ends, the remaining principal gets amortized over a shorter remaining term, and your payment jumps significantly. I worked with a borrower who saw a $395 monthly payment during the interest-only phase, then got hit with a $782 payment afterward. The calculator never warned her about the bump because it assumed a fully amortizing schedule from day one.
A Practical Workaround for the Interest-Only Trap
When I encounter an interest-only or deferred-payment structure, I build a custom table instead of relying on the calculator output. I map out the interest-only months at the stated rate, then recalculate the remaining balance amortized over the remaining term at the new rate. It takes about fifteen minutes in a spreadsheet and saves you from the payment shock I just described. For a concrete example: say you borrow $40,000 at 7.5% interest with twelve months of interest-only payments. Your monthly payment during that period is $250. After twelve months, you still owe $40,000. The remaining term is sixty months. The new monthly payment at 7.5% over sixty months is about $803. The calculator might show you a blended or idealized number, but the real payment you'll face at month thirteen is $803. That's more than triple the initial payment, and it's the number that matters for your budget.
Free Home Improvement Loan Calculator: What to Do With the Number
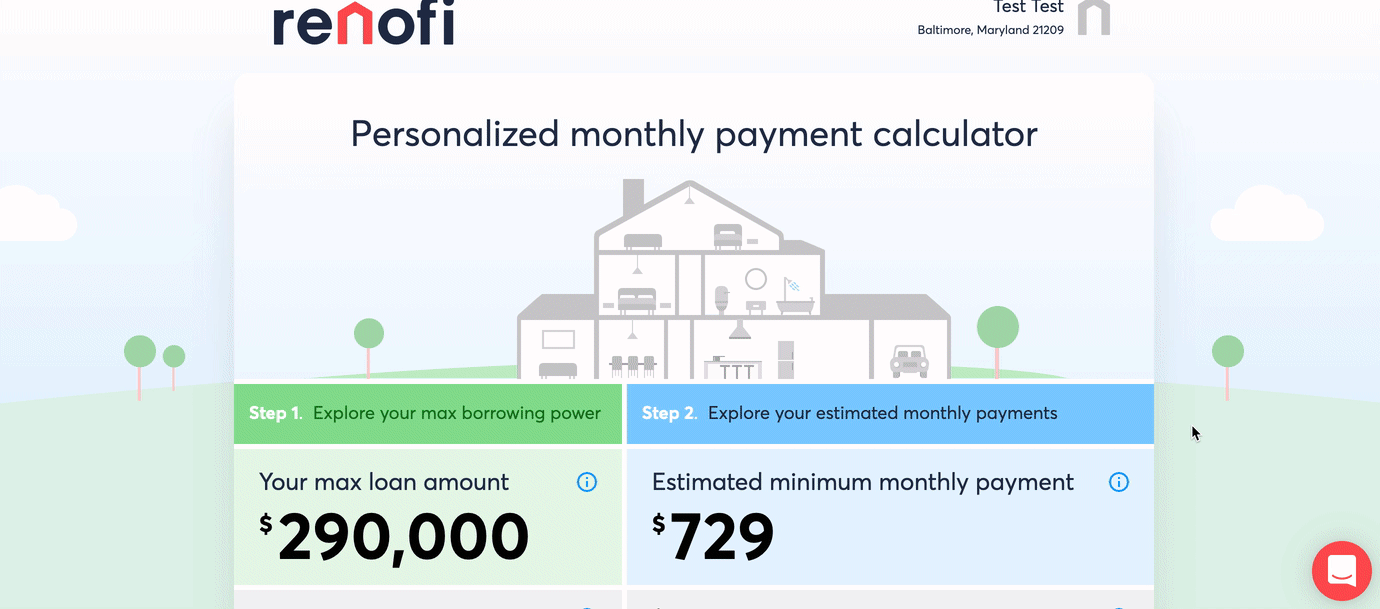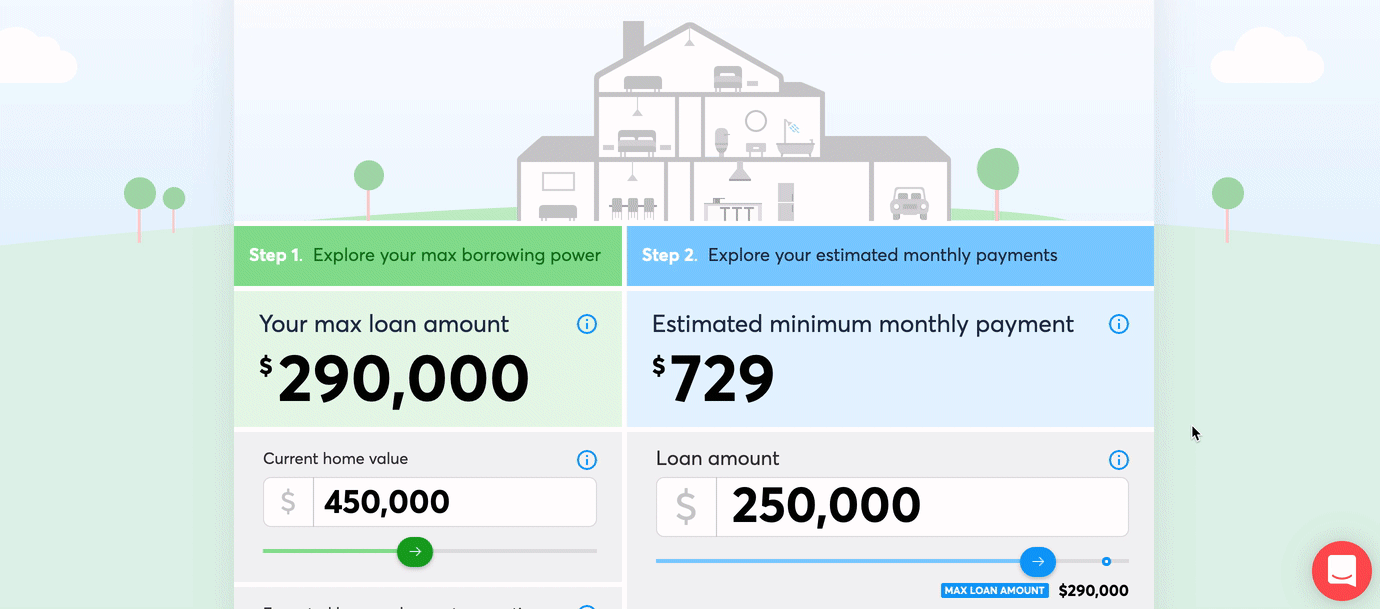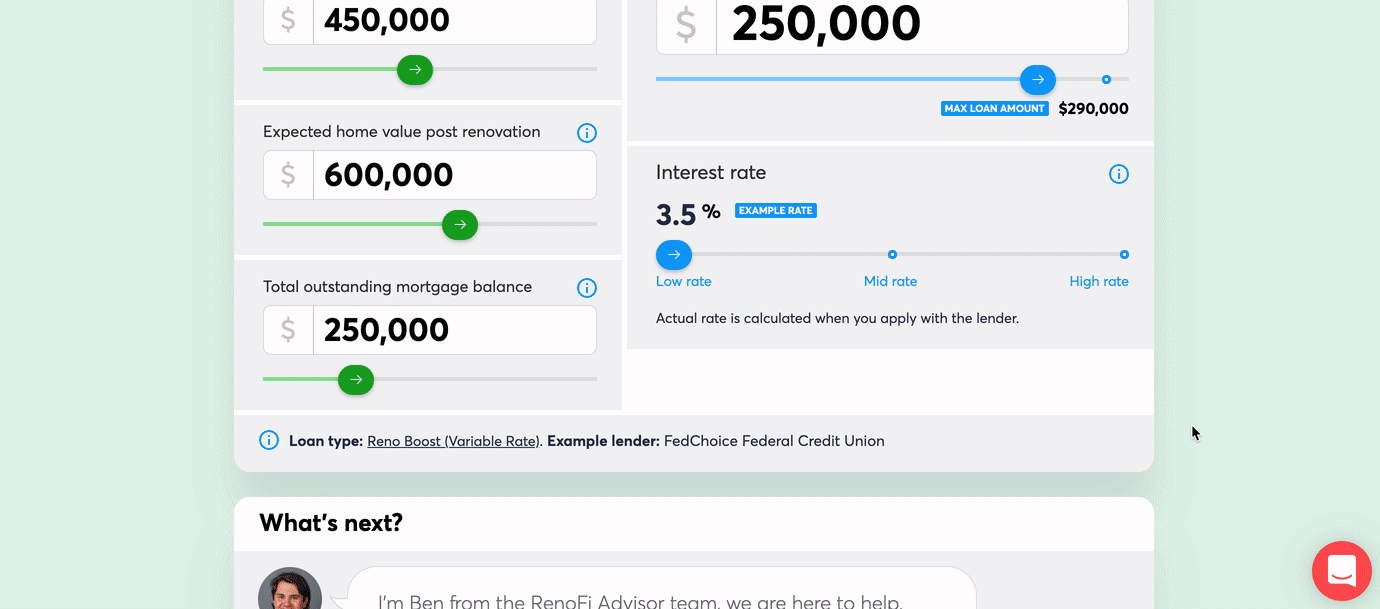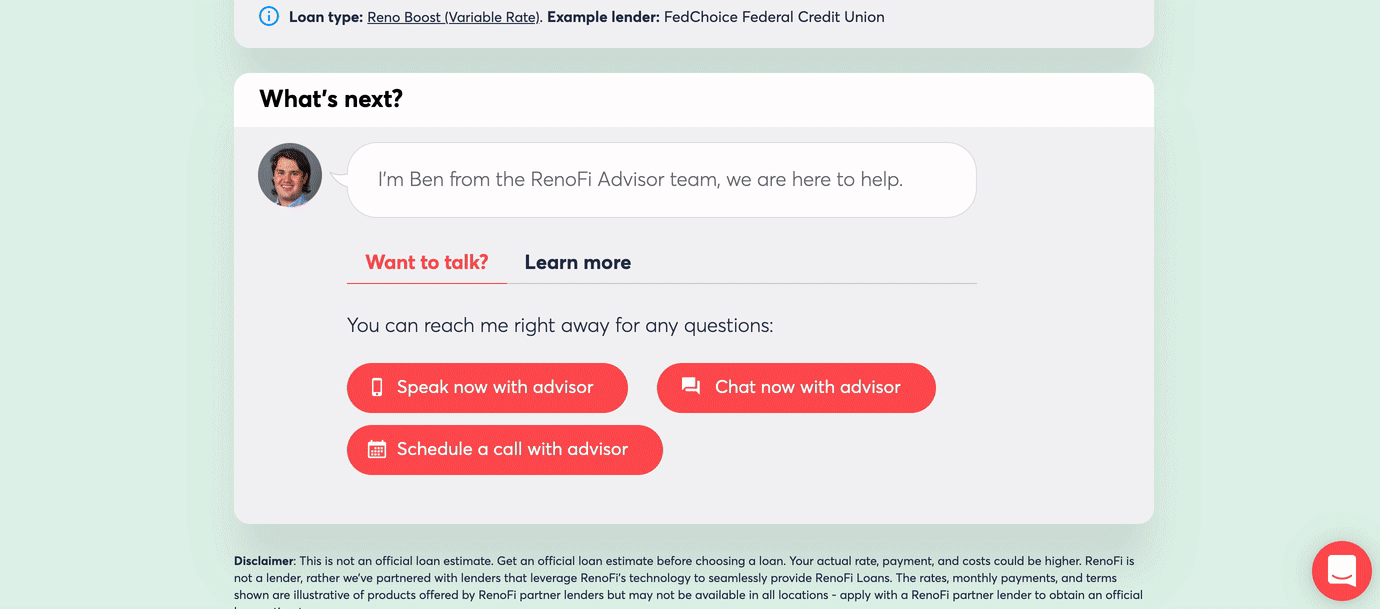
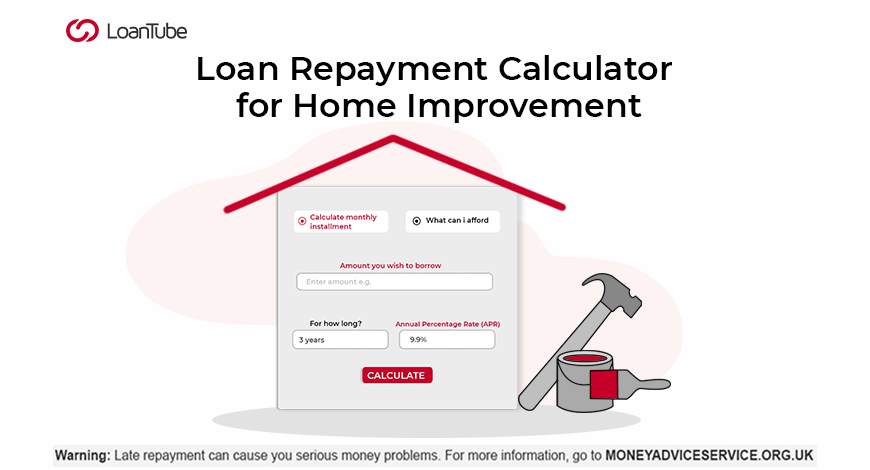
Take the calculator output and cross-check it against at least two lender disclosures before you sign anything. The number from the tool is a reference point. The actual contract may differ due to your specific credit profile, the lender's pricing tiers, or fees that aren't baked into the standard formula. I always tell people to treat the calculator result as a floor, not a ceiling. If the calculator shows $680 per month and the lender quotes $745, you need to ask which fees are creating the gap and whether any of them are negotiable. Origination fees are often negotiable on loans above $25,000. Rate discounts tied to autopay are standard and worth locking in. Some lenders will also reduce points if you're a repeat customer or if you bundle the loan with other products. These adjustments typically shave 0.125% to 0.5% off your rate, which on a $40,000 loan saves you between $250 and $1,000 over the life of the loan. The bottom line is straightforward. Run the numbers. Build your own spreadsheet alongside the calculator. Check the APR, not just the rate. Account for fees that the tool ignores. And never assume the first number you see is the number you'll actually pay. The gap between the two is where people get caught, and it's entirely avoidable if you do a bit of the work yourself instead of trusting a generic output.