Understanding HELOC Calculators in Texas
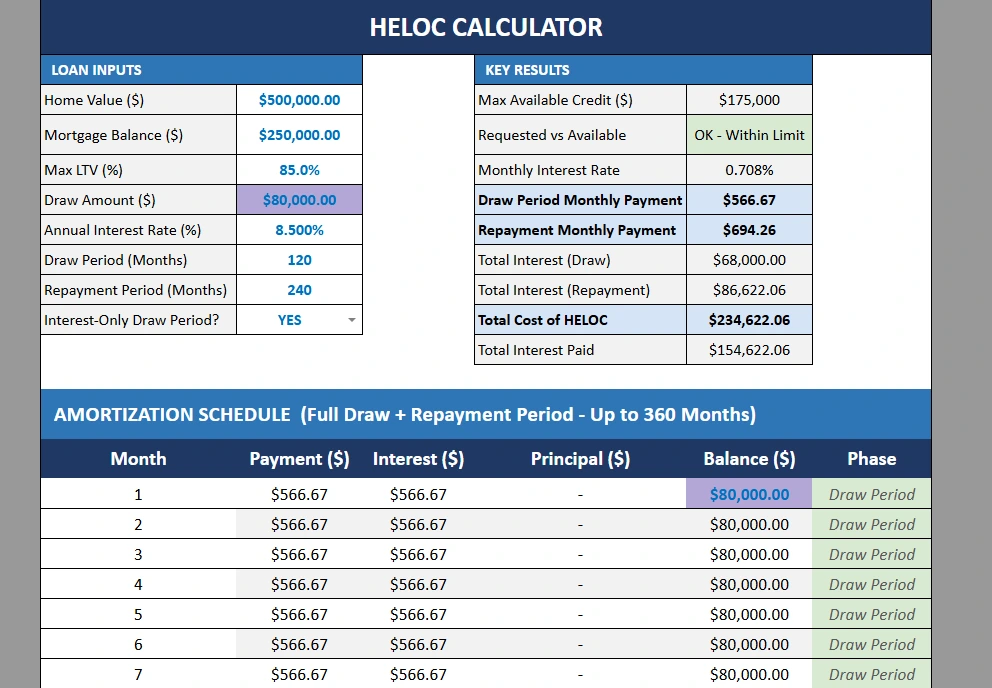
A HELOC calculator is a tool that estimates how much you can borrow against your home's equity and what your payments might look like. In Texas, there are some specifics that matter, mainly around appraisal rules and the state's homestead protections. I've spent years watching people mess this up because they trust a generic calculator without understanding what the numbers actually mean. Most HELOC calculators ask for three things: your home's current value, your outstanding mortgage balance, and the interest rate. That's it on the surface. The LTV ratio comes from the first two numbers. A typical lender wants you to stay under 85% combined loan-to-value. If your house is worth $400,000 and you owe $200,000, you're at 50% LTV. You theoretically have room for roughly $140,000 more in debt before hitting that 85% wall, though lenders may cap it lower. The tricky part nobody talks about is the draw period versus repayment period. Texas lenders commonly structure HELOCs with a 10-year draw period followed by a 20-year repayment phase. During the draw period, you only pay interest on what you've actually borrowed. After that, the whole remaining balance gets amortized. Your payment can triple overnight when that switch flips. I had a client in Houston who thought her $400 monthly interest-only payment was what she'd pay for life. It wasn't. Her payment jumped to over $1,100 once repayment started, and she hadn't budgeted for it at all.
Here's the counter-intuitive thing: a lower rate isn't always better on a HELOC. Some Texas lenders offer teaser rates that reset aggressively after 6 or 12 months. A calculator showing you payments at 5.5% might actually land you at 9% once the adjustment hits. Always ask what the fully indexed rate is, not just the promo number they put on the brochure. I learned this the hard way working with a lender who praised their "low introductory rate" while burying the margin over SOFR in the fine print. The actual rate ended up being nearly double what I'd initially seen. Another detail most people miss is how Texas handles liens. The state has strict constitutional protections around homesteads, which means your HELOC is a first-lien or second-lien position depending on how it's structured. This matters for priority if you ever face foreclosure. It also affects your ability to refinance later. A calculator won't tell you any of this, but your title company will care deeply about it. Let me walk through a real example. Say your home appraised at $350,000, you owe $175,000 on your primary mortgage, and you find a HELOC at 7.25% with a 10-year draw. You borrow the maximum allowed at 85% LTV. That gives you about $22,500 in available credit after accounting for the existing mortgage. Your monthly interest payment during the draw period comes to roughly $136. Sounds manageable until repayment hits. At that point, amortizing $22,500 over 20 years at 7.25% lands you around $178 per month on top of the principal. Combined with your existing mortgage payment, you're looking at a significantly larger monthly obligation than you probably expected.
I found that the most useful workaround when using any HELOC calculator Texas or otherwise is to run three scenarios: best case, expected case, and worst case. The worst case assumes the rate jumps to the fully indexed margin plus the current index value, which in today's environment could mean several percentage points above what the calculator initially shows. This takes about five extra minutes and has saved people from some painful surprises. There are also limitations you need to understand. These calculators assume your home value stays constant, which it rarely does. They don't account for closing costs, which in Texas can run between $1,500 and $3,000 depending on the lender and whether you need a new appraisal. They also ignore the fact that some lenders require a minimum credit score of 680 or higher, and your actual rate will vary based on where you sit relative to that threshold. If you want to actually use this, I'd recommend finding a local Texas lender who can walk you through the real numbers rather than relying solely on an online calculator. The ballpark figures help, but they won't prepare you for the specific underwriting requirements your particular situation will trigger. Most major Texas banks and credit unions have their own internal calculators that factor in state-specific lending guidelines, which generic online tools simply can't replicate accurately.
Get the Full Details
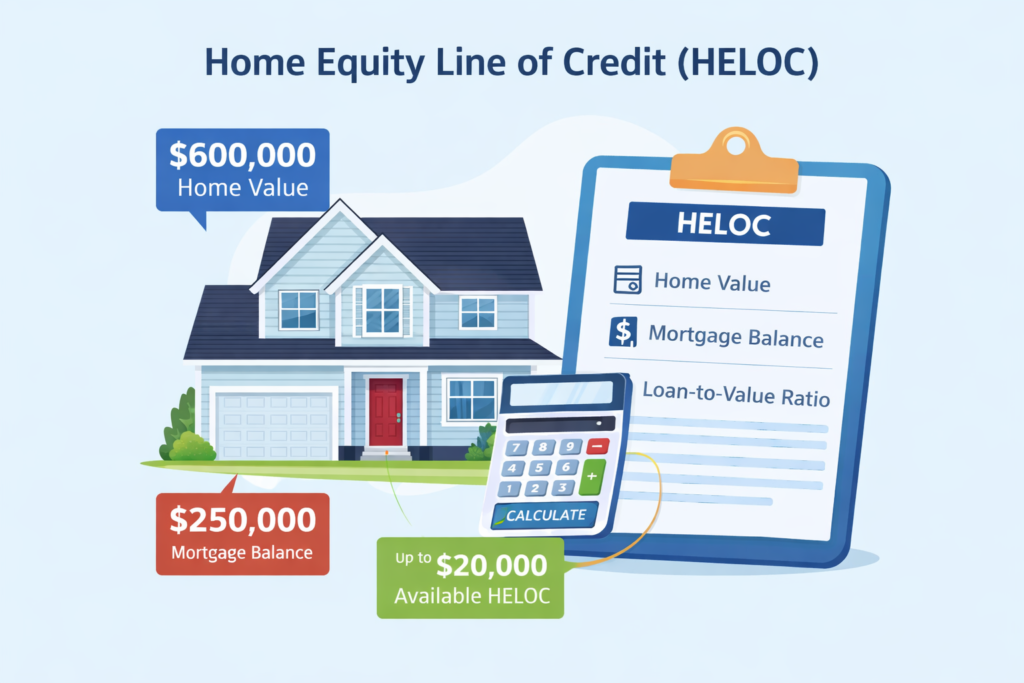
The bottom line is that a HELOC calculator gives you a starting point, not an answer. The numbers it produces are projections based on assumptions that may not hold. Use them to get a sense of scale, then validate everything with actual lender quotes before you sign anything. Your future self will thank you when the payment reminder hits your inbox.