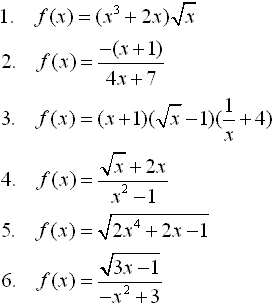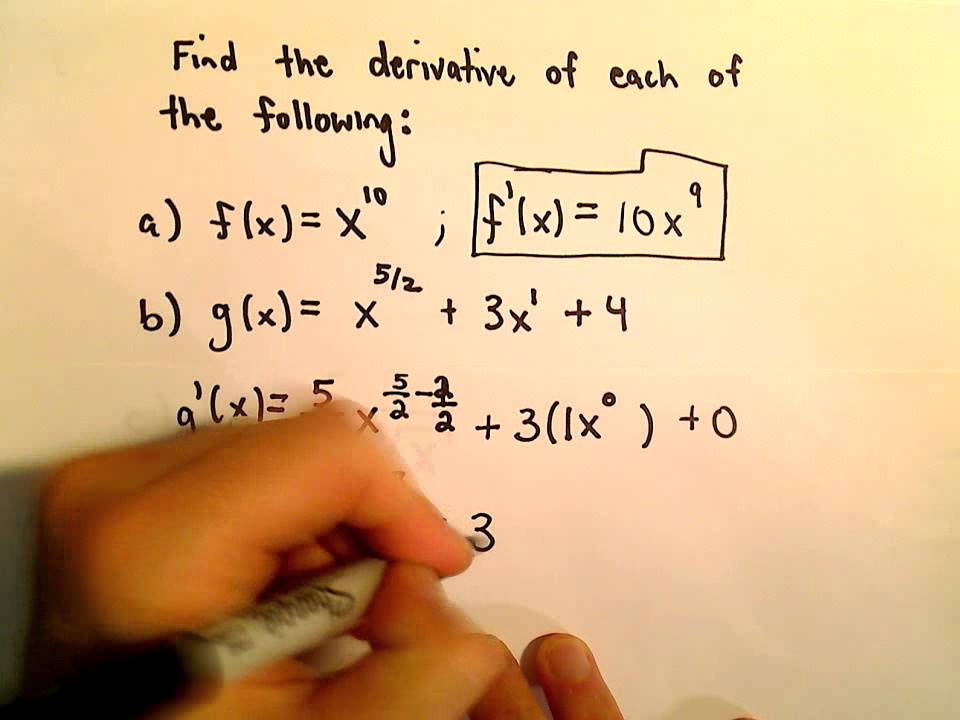
The Actual Work of Finding Derivatives
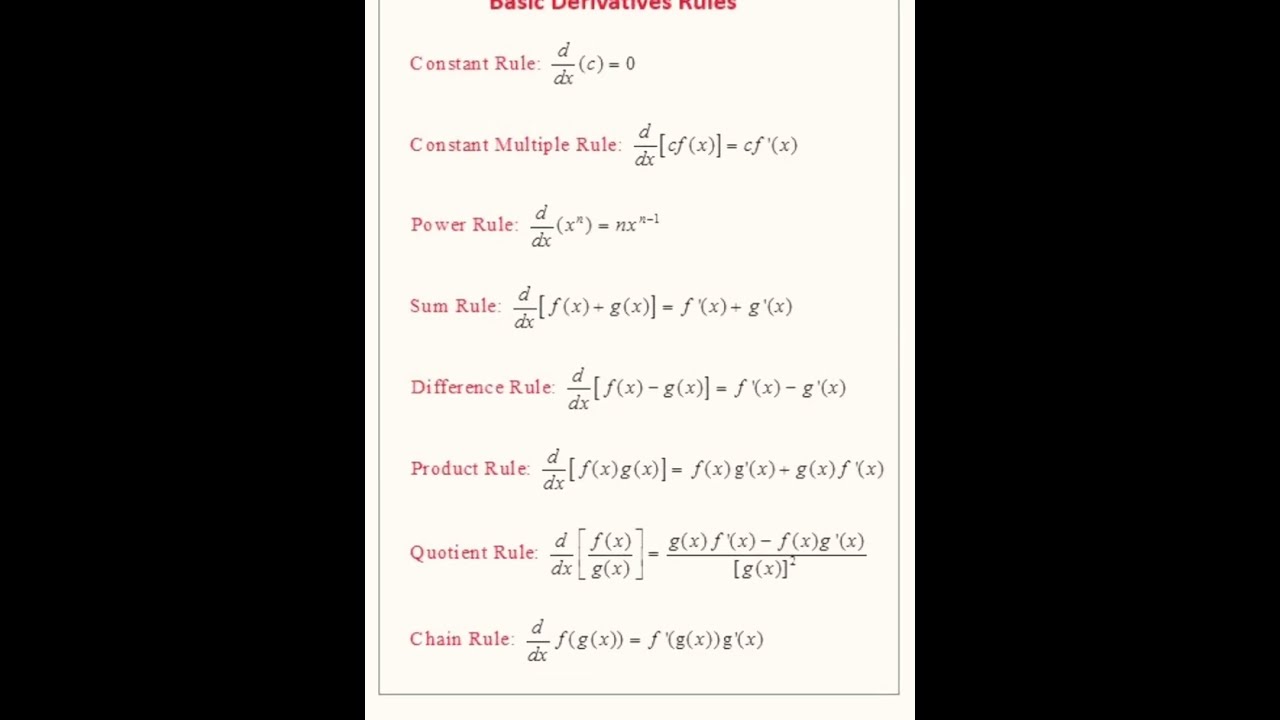
Most people approach derivatives backwards. They memorize the power rule, learn the chain rule, and then try to force every function through those two tools. That works for textbook problems and fails the moment you hit anything that isn't a clean polynomial or trig function. The real skill is knowing which tool applies and when the tools stop working altogether. Start by classifying the function. This is the step nobody teaches properly. Is it a composition of simpler functions? A product? A quotient? Implicitly defined? Piecewise? The classification determines your entire approach, and misclassifying takes you down the wrong path before you've written a single line of calculus. For explicit functions, the standard toolkit covers about 90 percent of practical cases. The power rule handles x^n. The sum and difference rules let you treat each term independently. The product rule handles f(x)g(x), and the quotient rule handles f(x)/g(x). The chain rule handles compositions like sin(x^2) or e^(3x). You learn these in order because the later rules depend on the earlier ones, not because there's some pedagogical virtue to it.
Here's what actually matters: implicit differentiation. Most students encounter it once in a semester and never use it again because their coursework stops at explicitly defined functions. In practice, implicit differentiation shows up constantly when dealing with equations where y isn't isolated. A real example from my work: I was debugging a mechanical simulation where the constraint equation was x^2 + xy + y^2 = 3, and I needed dy/dx at a specific point. Isolating y would have required solving a quadratic and introducing square roots that made the algebra much messier. Instead, I differentiated both sides with respect to x, treated y as a function of x, applied the product rule to the xy term, and solved for dy/dx algebraically. That gave me the derivative in one clean step without ever writing y as an explicit function of x. The formula approach you see in textbooks often presents derivatives as a lookup table. That's functional for exams but insufficient for actual work. You need to understand why the rules exist. The power rule comes from the limit definition. The chain rule exists because when you nest functions, the outer function's rate of change scales the inner function's rate of change. If you can't explain that intuitively, you'll make mistakes on functions that don't fit the standard patterns. Logarithmic differentiation is another technique most courses mention in passing but rarely reinforce. It's valuable for functions like y = x^x or y = (sin x)^(cos x), where neither the power rule nor the exponential rule applies directly. You take the natural log of both sides, simplify using log properties, differentiate implicitly, then exponentiate back. I used this last month on a signal processing problem involving a transfer function raised to a variable power. Standard rules broke down immediately. Logarithmic differentiation reduced it to something manageable in about three lines.
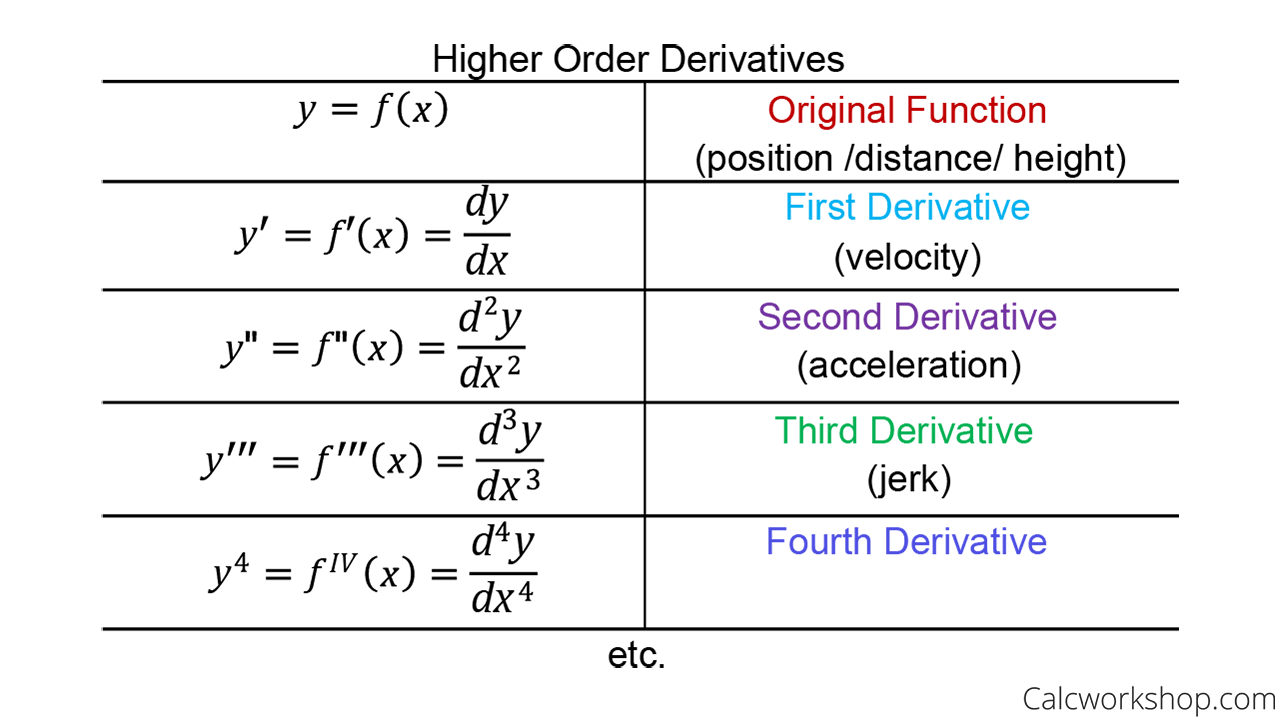
Partial derivatives are a separate category entirely. If your function has more than one independent variable, like f(x,y) = x^2y + sin(xy), you differentiate with respect to one variable while holding the others constant. This isn't a special rule. It's just the regular derivative rules applied to a slice of the function. The confusion comes from notation. You'll see f/x and f/y and wonder if there's deeper machinery involved. There isn't. The notation changes because the context changes, not because the operation changes. Directional derivatives and the gradient vector are where things get technically heavier. The gradient points in the direction of steepest ascent, and its magnitude is the rate of increase in that direction. Directional derivatives generalize this to any direction vector. This matters in optimization, machine learning, and physics simulations. I've seen engineers skip this entirely and rely on numerical approximations instead, which work fine for low-precision applications but introduce significant error when you need accuracy better than a few percent. Here's a counter-intuitive point that most beginners miss: higher-order derivatives aren't just repetition. The second derivative tells you about concavity and acceleration. The third derivative, called jerk, matters in control systems and robotics where smooth motion profiles are required. In structural engineering, fourth derivatives appear in beam deflection equations. Each order carries distinct physical or geometric meaning. Treating them as mechanical repetition wastes the information they contain.
Get the Full Details

Numerical differentiation is the fallback when analytical methods fail or become impractical. You approximate the derivative using finite differences: (f(x+h) - f(x))/h for the forward difference, or the more accurate central difference (f(x+h) - f(x-h))/(2h). The tradeoff is immediate. Choose h too large and truncation error dominates. Choose h too small and floating-point roundoff error dominates. The sweet spot is usually around 10^(-8) for double-precision arithmetic, but it depends on the function's behavior near the point you're evaluating. I spent two days tracking down a bug in a thermal simulation that traced back to h being too small for the scale of the temperature gradient. Switching to a central difference with an adaptive step size fixed it in an afternoon. There are hard limits to analytical differentiation. Some functions don't have closed-form derivatives. The error function, Ei(x), and various special functions defined by integrals require numerical treatment or series expansions. Discontinuous functions present another wall. If a function has a jump discontinuity at a point, the derivative doesn't exist there, and no amount of clever manipulation will change that. Piecewise functions require checking each piece individually and then verifying continuity and differentiability at the boundaries. I once inherited code that computed derivatives of a piecewise pressure model across phase boundaries. The original developer had applied the power rule to each piece separately and never checked whether the derivatives matched at the transition points. The model produced physically impossible results near those boundaries because the first derivative was discontinuous even though the function itself was continuous. Symbolic computation tools like SymPy, Mathematica, or Maple can handle a lot of this automatically. They're fast and accurate for standard functions. But they silently fail on edge cases, and they can't always simplify results to the form you actually need. I've seen engineers trust the output without verifying it on simple test cases, which is how bad derivatives get embedded in production code. Always verify with a known case before trusting the tool on something new.
The underlying principle across all of this is that differentiation is a local operation. You're measuring instantaneous rate of change at a point. Everything else—the rules, the theorems, the computational methods—is just a structured way to compute that local measurement efficiently. When the structure breaks down, you go back to the limit definition and approximate from first principles.