The Setup Phase
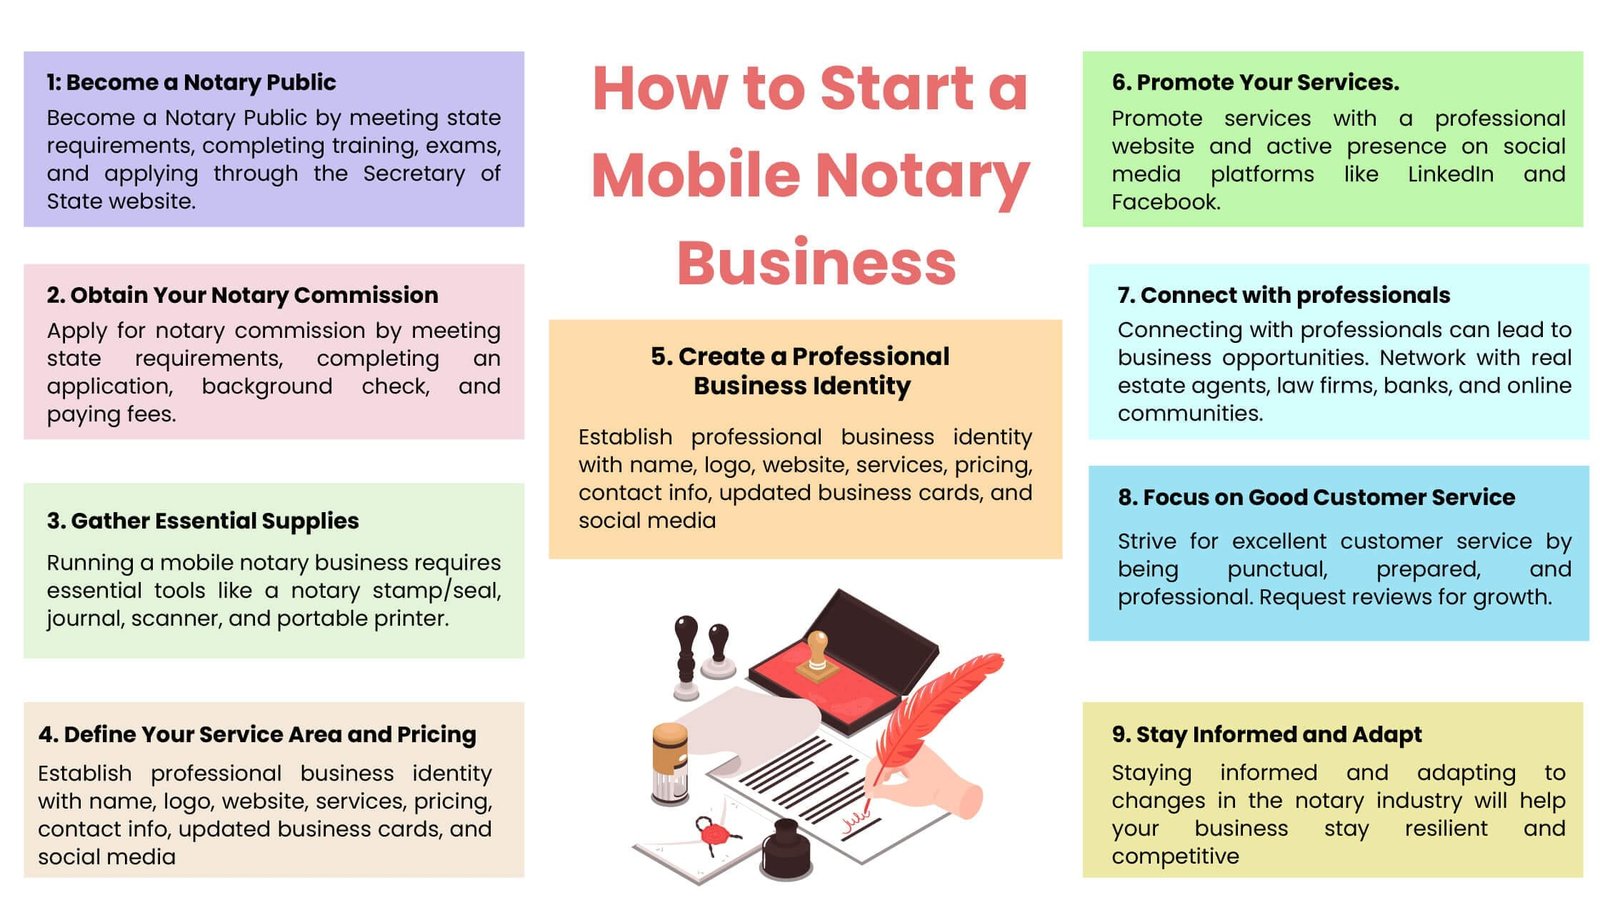
Most people treat a notary commission like a finish line. It is the starting line. The commission from your secretary of state costs between fifty and one hundred thirty dollars depending on the state, and that is the easy part. I have seen people spend more on training courses they did not need. The real cost comes after you get commissioned, when you are figuring out logistics, equipment, and how to actually find clients without going broke in the first six months. Here is what I actually do when someone asks me How To Start A Mobile Notary Business. You skip the expensive courses. The state requirements are the only thing that matters legally. You take the state exam if there is one. You buy your seal, your journal, and a basic mobile notary package if you want to look professional. That is it. Everything else is scale and effort.
How To Start A Mobile Notary Business
The business side is simpler than most people think. You register your DBA or LLC, get an EIN if you are forming an LLC, and then you set up your pricing. A typical mobile notary visit in the United States runs between seventy-five and one hundred fifty dollars for standard documents. Loan signings, which are the bread and butter, run anywhere from one hundred fifty to two hundred fifty dollars each. You can make decent money if you stay booked, but the booking part is where things get complicated. I learned this the hard way in my second year. A title company sent me to a senior living facility for a loan signing. The resident was disoriented. The notary section required an ID check and a verbal acknowledgment. The resident's daughter kept answering questions for her mother. I caught it because I had dealt with a similar situation two years earlier at aVA hospital where the patient was heavily sedated and the nurse kept filling in answers. What worked before was stopping the signing entirely, explaining to the daughter that the notarization would be invalid, and contacting the title officer to reschedule with a different approach. The daughter got upset. I did not care. An invalid notarization costs far more than one awkward phone call.
Equipment and Day-to-Day Reality
You need a few things that people forget until they are already driving around. A portable laptop stand. Most signing agents use their car dashboard as a desk, which is terrible for accuracy. A foldable lap desk costs twelve dollars and solves that. Printers go out of paper at the worst times. Keep a spare ream in your trunk. And a portable stamp pad. Cheap ones bleed through pages and make your journal look like a crime scene. The journal is where most beginners mess up. You need a registered notary journal, preferably one that matches your state's requirements. Some states require specific fields. California is notoriously strict about exact wording. Texas requires a separate bond in many cases. Your journal entries need to include the date, time, document type, signer name, identification method, and your seal impression. This usually takes about four minutes per document if you are organized, maybe eight if you are fumbling through forms you have never seen before. I keep a laminated cheat sheet in my glovebox with the required fields for the three states I work in most. It cuts my preparation time down to under a minute per entry. Insurance is non-negotiable. Errors and omissions coverage runs about two hundred to four hundred dollars a year. It will save you from bankruptcy if a signing goes wrong. You will also want general liability insurance if you are entering private homes or business offices. A lot of signing agents skip this. Do not skip it. I had a client trip over a cord in my car while getting out after a signing. She filed a claim. My general liability covered it. That one incident could have cost me five thousand dollars without coverage.
Get the Full Details
Finding Work
Word of mouth works. Title companies and escrow offices work better. You call them, introduce yourself, and ask to be added to their signer panel. Most have a simple application. Some require proof of insurance and a background check. The process takes about two weeks. You can apply to ten companies in a single weekend. Do it. Attorneys are another source. They need notaries for estate planning documents constantly. They do not care about price as much as reliability. Show up on time, every time, and they will send you work for years. I have had the same estate planning attorney send me twelve to fifteen signings a month for three years running. That is reliable income, roughly two thousand dollars monthly, just from one referral source. The hard part is weekends and holidays. That is when the money is. Title companies need weekend closings. If you are not available then, you are leaving money on the table. I stopped taking weekday appointments after two years. Weekends pay twenty to thirty percent more, and the volume is higher. My weekday availability dropped by sixty percent, but my weekly income stayed flat because weekend bookings compensated fully.
Common Mistakes That Cost Money
Not verifying identity properly is the biggest one. I had a signer bring a workplace ID instead of a government-issued photo ID. The document was a power of attorney. If I had notarized it, the POA would have been challengeable in court. I turned the signer away and asked them to come back with proper ID. They were angry. They found another notary who notarized it anyway. Six months later, the signer's siblings contested the POA in probate court. The court threw out the notarization because the notary had accepted an invalid ID. That notary got sued. The signer lost her brother's inheritance fighting it. All because someone skipped the ID verification step. Another mistake is not reading the document before you arrive. I showed up once for a real estate transaction and the borrower wanted to initial every page. The document had forty-seven pages. The title company expected me to watch every single initial. That changed the timing from fifteen minutes to nearly an hour. If I had read the document beforehand, I would have known to block off extra time or decline the appointment. I declined the appointment, drove back home, and let the title company find someone else. They called me an hour later asking if I was available. I came back the next morning and made the full signing fee plus a waiting fee. Lesson learned. Read the document first. Always. You should also know that not all states allow mobile notaries to perform loan signings. Some states restrict loan officers from using independent signing agents in certain transaction types. Check your state's restrictions before you market yourself as a loan signing specialist. I wasted three weeks trying to get approved by title companies in a state that does not permit independent loan signings. The workaround was partnering with a nearby state's notary network and crossing state lines for those appointments. It added twenty minutes of driving but opened up the market.
The bottom line is that this business is straightforward to enter and difficult to scale well. The commission is easy. Finding steady work takes months. Building a reliable book of business takes years. The people who last are the ones who show up on time, verify IDs correctly, and do not cut corners on documentation. Everything else is noise.