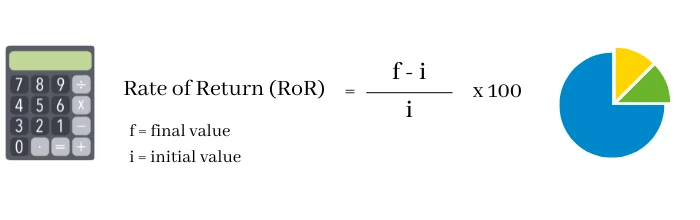
The Basic Math Behind Rate Of Return
Rate of return measures how much money you made or lost on an investment relative to what you put in. The basic formula is subtracting your initial cost from your final value, dividing by the initial cost, then multiplying by 100 to get a percentage. That's it. Most people stop there because introductory articles do too. They don't tell you the formula breaks down the moment you add money to an investment mid-stream, or when returns come in at different times. Here's the formula nobody warns you about: (Final Value minus Initial Cost) divided by Initial Cost times 100. If you put in $10,000 and it's now worth $12,500, that's $2,500 divided by $10,000 times 100, which gives you 25 percent. Simple. The problem isn't the math. The problem is what counts as the initial cost and what counts as the final value when things get complicated. I ran into this with a client who had been dollar-cost averaging into a position over three years. They'd made twelve contributions of varying amounts ranging from $500 to $3,000 each. When they asked me what their return was, just taking the current total and dividing by the sum of contributions gave a number, but it was wrong. It understated their actual gain because some of the money had been invested for much longer than other portions. A simple rate of return conflated the timing. I switched to calculating internal rate of return using a spreadsheet solver function instead. It accounted for each cash flow on its exact date and spit out an annualized figure that was actually meaningful. The simple method gave them about 18 percent. The IRR came in around 22 percent. That gap matters when you're trying to decide whether to hold or sell.
When Simple Rate Of Return Is Good Enough
For a single lump sum investment with no additional deposits or withdrawals, the basic formula works fine. You put money in, it grows, you take it out. There's no ambiguity. I use this for quick back-of-the-envelope checks all the time. If a rental property bought for $320,000 now appraises at $385,000 and you've collected $41,000 in net rent over the holding period, your total gain is $106,000. Divided by $320,000 is about 33.1 percent total return. Not annualized, just total. Sometimes that's exactly what you need to compare two opportunities side by side without getting into complicated calculations. The catch is that 33.1 percent over four years looks very different from 33.1 percent over twelve years. That's why annualizing matters for anything held more than a year or two. The formula for that is less familiar to most people. You take one plus the total return, raise it to the power of one divided by the number of years, then subtract one. So 33.1 percent over four years becomes 1.331 raised to the 0.25 power minus one, which equals roughly 7.7 percent annualized. Over twelve years the same 33.1 percent total drops to about 2.4 percent annualized. Same outcome, completely different story depending on how long it took.
Common Pitfalls That Make Numbers Look Better Than They Are
The biggest mistake I see is ignoring the time component entirely. Someone will say they made 40 percent on an investment without mentioning it took six years. Another person made 35 percent in eighteen months. The 40 percent looks bigger but it's the worse investment by far. Always state the time horizon alongside the percentage. A return without a timeframe is almost useless for comparison purposes. Another trap is counting gross return instead of net return. Brokerage fees, management expenses, tax drag, bid-ask spreads, those all eat into what you actually keep. I had a mutual fund position where the gross return over five years was 62 percent. After accounting for the expense ratio, trading costs from rebalancing, and taxes on distributions, the net return was closer to 44 percent. People tend to cite the gross number because it sounds better. Your broker might even do it intentionally. Always subtract the full cost of participating before you declare a win. There's also the reinvestment assumption problem. Dividends and interest payments that are taken as cash rather than reinvested change the picture significantly. A stock yielding 3 percent in dividends and appreciating 7 percent in price performs very differently depending on whether you pocket the dividends or buy more shares with them. The rate of return calculation changes based on that choice. I always specify whether my returns are total return including reinvested distributions or price return excluding them. The difference can be several percentage points annually over long periods.
Get the Full Details

Advanced Methods for Complex Situations
When you have irregular cash flows, partial exits, or multiple asset classes combined in one portfolio, simple rate of return stops working. That's where time-weighted return and money-weighted return come in. They answer different questions. Time-weighted return strips out the effect of deposits and withdrawals. It tells you how the underlying investments performed regardless of when you added or removed money. Money-weighted return, which is essentially IRR, factors in the timing of your cash flows. It tells you how well you did as an investor making decisions about when to put money in or take it out. I use time-weighted return when evaluating fund managers because you're measuring their skill at picking investments, not your skill at timing the market. Money-weighted return is what you actually care about personally because it reflects your real experience with the money. The gap between the two numbers on any given portfolio is a pretty good indicator of whether market timing helped or hurt you. When the gap is small, you're basically along for the ride. When the gap is large and negative, you've been buying high and selling low, and the math is proving it. One edge case that tripped me up recently involved a cryptocurrency position where I was staking rewards being paid out daily. The rewards themselves varied in value due to price swings. Converting everything to a single currency at the point of receipt, then tracking the consolidated portfolio value, was the only clean way to calculate return. Attempting to separate the staking yield from capital appreciation with daily compounding and volatile pricing made the math nearly impossible to do accurately by hand. I ended up using a database that imported transaction history automatically and computed the return period by period. Took about ten minutes to set up once versus hours of manual calculation that would still have been approximate.
What Rate Of Return Can't Tell You
Return alone is meaningless without context about risk. Two investments might show identical 12 percent annual returns over five years, but one could be a steady compounder while the other rode massive volatility with two years of negative returns offsetting three years of big gains. The raw percentage number hides that difference completely. That's why sharpe ratios, maximum drawdown, and standard deviation of returns exist. They supplement the basic calculation with information about how painful the ride was. Inflation also distorts nominal return figures. A 6 percent return sounds fine until you realize inflation averaged 4 percent that year. Your real purchasing power only grew about 2 percent. For retirement planning or long-term savings goals, real return matters more than nominal return. Adjusting for inflation is straightforward if you have the CPI data. Divide one plus nominal return by one plus inflation rate, then subtract one. The result is usually significantly lower than the headline number investors quote. There's also the problem of look-ahead bias in performance reporting. Some platforms calculate returns using ending values that include information not available at the time of decision making. If you're backtesting a strategy or comparing historical performance, make sure the return calculations only use data that was actually known during each period. Otherwise you're measuring something that couldn't have been achieved in practice. I've caught this in fund prospectuses where the reported returns included rebates or fee waivers that weren't available to earlier investors. The numbers looked great until you read the fine print about which fee schedule applied to which share class.
Practical Steps to Calculate Your Own Returns
Start by gathering your transaction history. Every deposit, withdrawal, purchase, sale, dividend, and distribution. The more complete the record, the more accurate the calculation. Most brokerage platforms let you export this as a CSV file. If you're managing multiple accounts, consolidate them into a single dataset before calculating. Calculating return on each account separately then averaging them is misleading because larger accounts dominate your actual financial outcome. For straightforward investments with no intermediate cash flows, the basic formula is sufficient. For anything with regular contributions or withdrawals, use a spreadsheet with the XIRR function. It handles irregular dates and varying amounts without requiring manual period-by-period calculations. If you don't have access to XIRR, a financial calculator or dedicated portfolio tracking software will do the same job. Free options like Google Sheets include XIRR and it takes maybe five minutes to set up properly if you've done it before. Always document your methodology. If you're reporting returns to someone else or tracking your own progress over years, the calculation method matters for consistency. Switching from simple return to IRR mid-way through your records makes year-over-year comparisons invalid. Pick a method and stick with it unless there's a genuine reason to change. Write down what you're using so you remember later when you're reviewing past performance and wondering why the numbers don't look right.