How the Illinois Small Estate Affidavit Actually Works
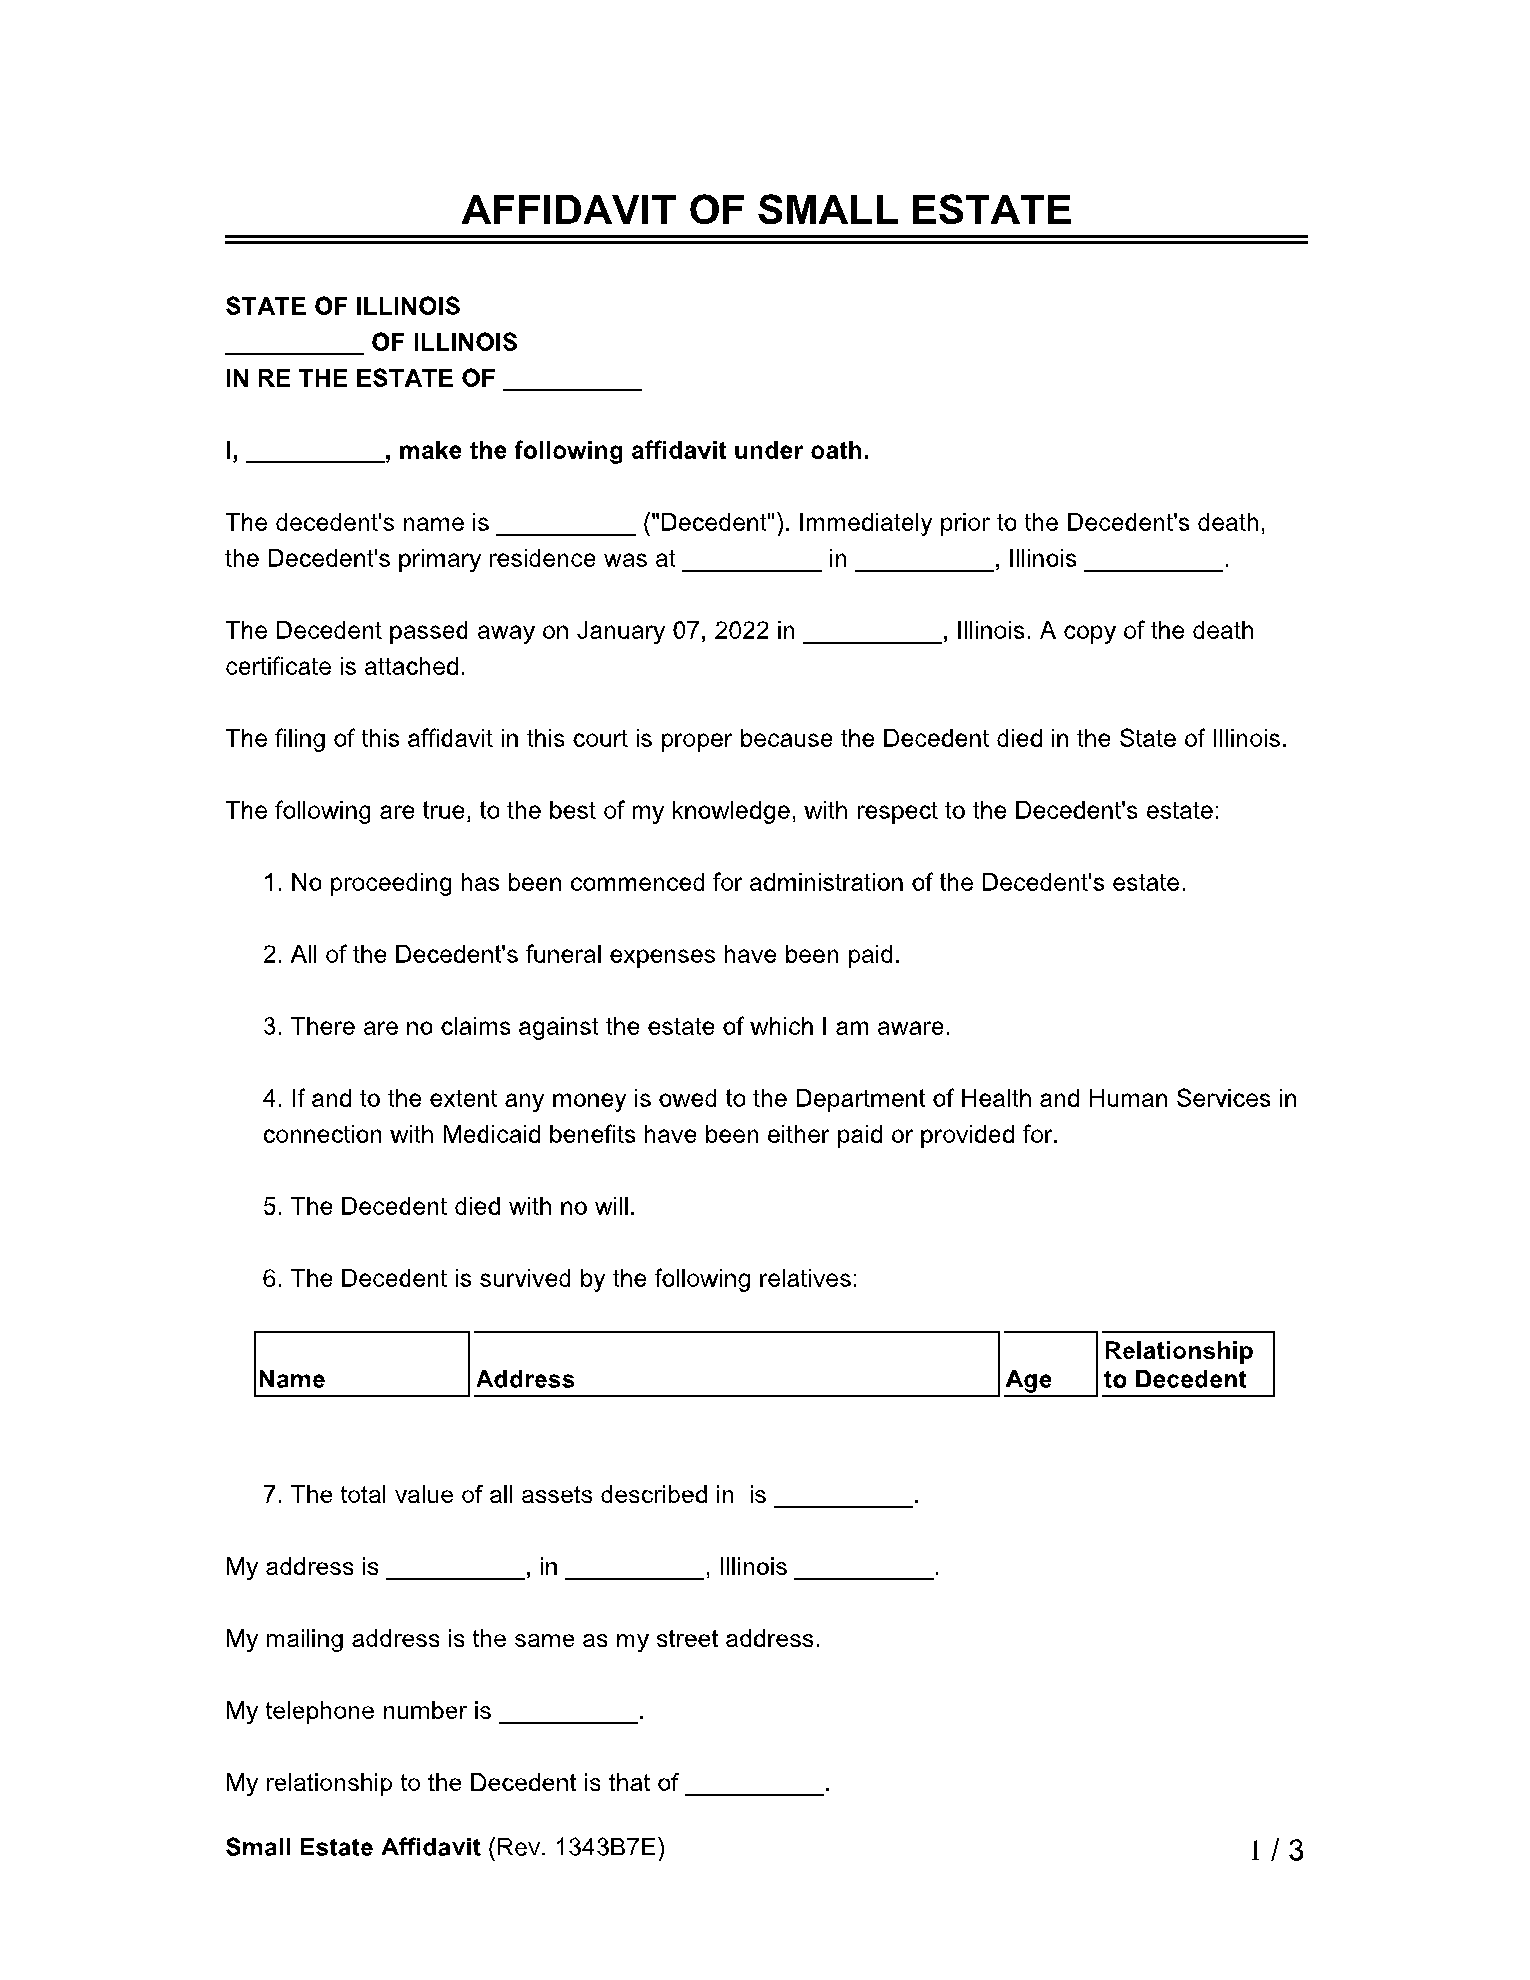
The Illinois Small Estate Affidavit is a statutory shortcut that lets an heir or successor collect a decedent's assets without going through formal probate. It only applies when the total gross value of the estate—meaning the full value before any debts are deducted—stays at or below $100,000 and does not include real estate. The statute is Illinois Compiled Statutes chapter 755, paragraph 211, and the form itself is not something the legislature publishes as a single mandatory template. Courts and institutions just expect the required statutory elements to be present. I have filled out more of these than I care to count, usually at 10 PM on a Tuesday because someone finally found the death certificate and could not figure out why the bank was refusing to release a $12,000 checking account. The process itself is fast. Fill the form, get it notarized, wait 30 days past the date of death, serve a copy on any legal heirs if they are not the person collecting the assets, and then hand it to the institution holding the asset. A typical gathering of documents takes maybe 15 to 25 minutes if your paperwork is organized, and the actual completion of the affidavit is another 10 minutes. The bottleneck is almost never the form.
Understanding the Illinois Small Estate Affidavit Requirements
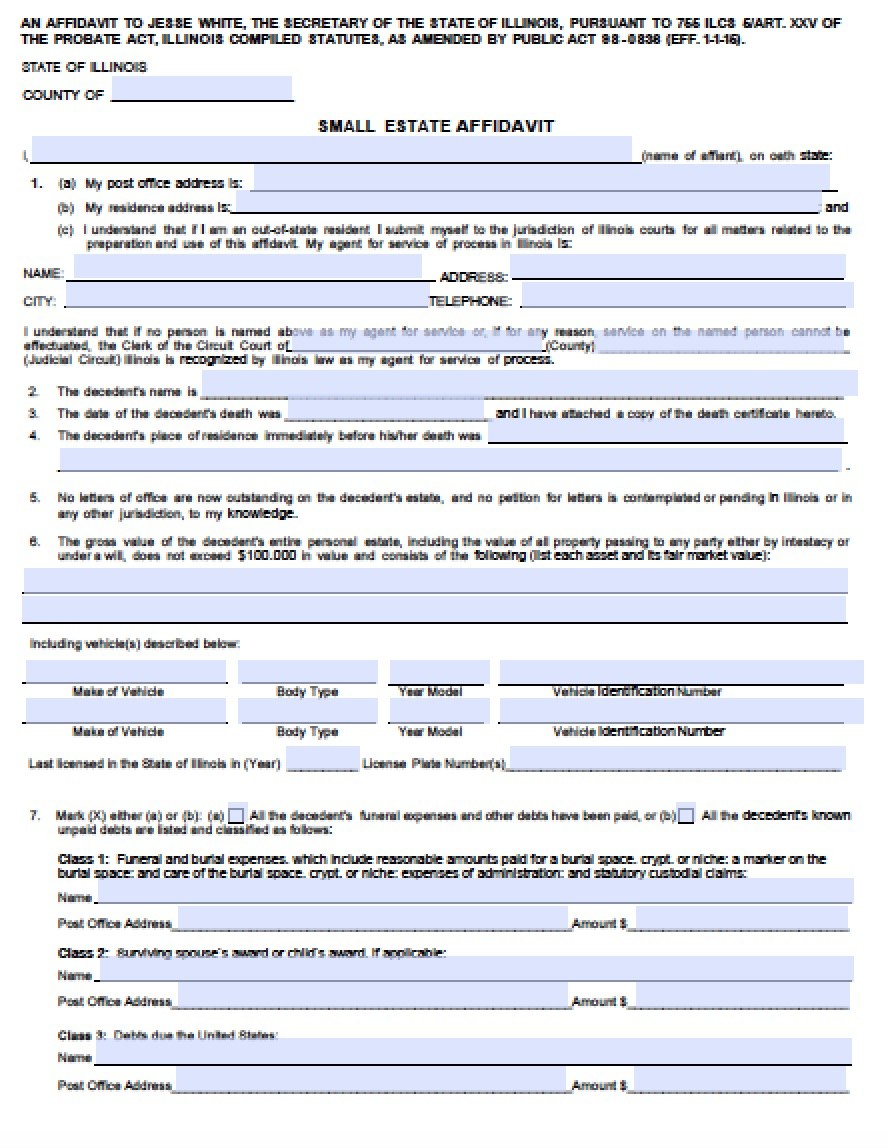
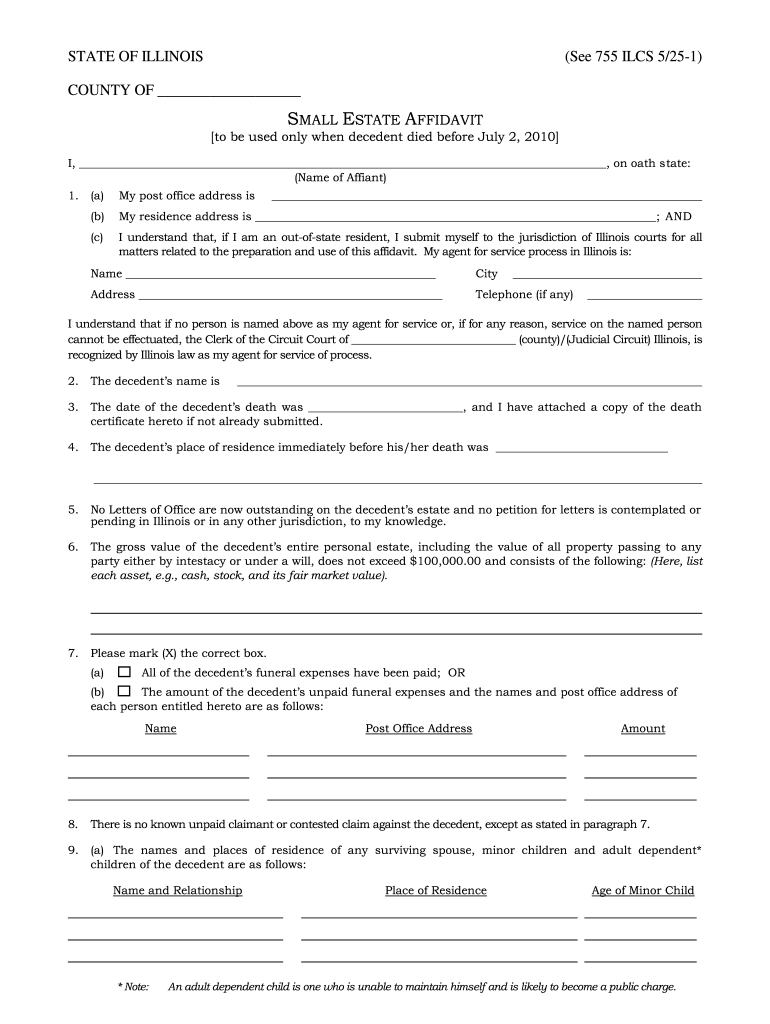
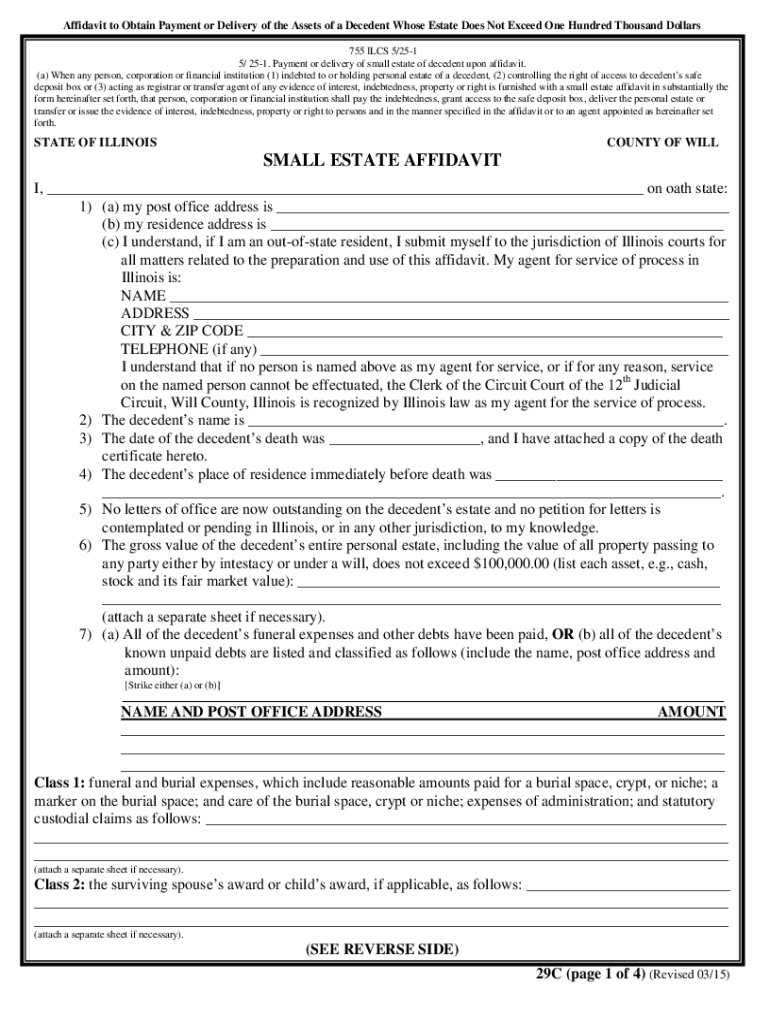
The form needs specific data points, and missing even one will make a skeptical bank teller hand it back. You must list the decedent's full legal name, last address, Social Security number, date of death, and the names and addresses of all legal heirs and beneficiaries. The inventory of assets goes next, with estimated values and a note about whether each asset has a designated beneficiary. You also need a declaration that the gross value does not exceed $100,000, that 30 days have passed since death, that no formal probate proceeding is pending or has been granted, and that the person presenting the affidavit is entitled to the assets. Several institutions also want the presenter's relationship to the decedent spelled out clearly. The gross value cap is where most people misjudge the number. Gross value means the total of everything before subtracting debts. If the decedent had a checking account with $18,000, a retirement account worth $60,000, a car valued at $12,000, and owed $4,000 on a credit card, the gross value is $90,000, not $86,000. The debt is irrelevant to the threshold. That distinction trips people up repeatedly, and it is the reason some estates that look small on paper actually fall outside the small estate procedure. Real estate is disqualifying regardless of value. A house, a timeshare, a condominium, a vacant lot—anything with a recorded deed passes you out of this route and into formal administration, even if the equity is tiny and the mortgage wipes out most of it. Joint tenancy with right of survivorship assets and payable-on-death accounts also do not need this affidavit, but they still count toward the $100,000 gross total unless the institution treating them as non-probate explicitly excludes them from its own calculation. Banks often have their own internal policies that are stricter than the statute, so expect friction there.
Where People Mess This Up
I ran into a case recently where a brother used the affidavit to collect his mother's accounts. The gross value was roughly $71,000, comfortably under the limit. The problem was that one of the accounts was a broker account registered as transfer-on-death to his sister. The brokerage company refused to honor the affidavit for that specific account because their internal compliance policy required a formal court order for any account with a registered beneficiary, even though the statute does not forbid it. We ended up using the affidavit only for the non-beneficiary-designated accounts, which took about three weeks instead of one. The workaround was straightforward once I realized what the issue was: separate the assets into two buckets, use the affidavit for the clean ones, and let the beneficiary designations handle the rest on their own timeline. No one gained anything by forcing a single document to do both jobs. Another edge case that keeps coming up involves blended families. If the decedent left a surviving spouse and also children from a prior relationship, the statute requires you to serve a copy of the affidavit on all legal heirs, not just the person collecting. A few institutions will accept the affidavit without proof of service if the collector is the sole heir, but many will not. The safest move is to serve everyone, keep a signed acknowledgment of service or a certificate of mailing, and attach it to the affidavit when you present it. It adds maybe five minutes to the process and prevents a second trip to the bank.
Get the Full Details
Common Pitfalls and How to Avoid Them
The 30-day waiting period is mandatory. Presenting the affidavit on day 29 is a quick way to get rejected, and some institutions will ask to see the death certificate to verify the date themselves. Estimates of value should be conservative. Overstating an asset and crossing the $100,000 line invalidates the entire affidavit. If you are close to the limit, assume the lower end of any range and leave room for the item you forgot to account for. Notarization is required, and the notary should witness the signature of the affiant, not just stamp a printed form that was signed elsewhere. Institutions sometimes check the notary stamp date against the death certificate date, so make sure the timeline makes sense. Also, the form should be original. Photocopies are routinely rejected by banks and title companies that handle motor vehicles. If the estate includes a vehicle titled in the decedent's name alone, the Illinois Secretary of State will accept an affidavit in lieu of probate, but only if the gross value test is met and no formal probate is pending. They have their own checklist, and it differs slightly from what banks require. Bring the certificate of title, the death certificate, the notarized affidavit, and a completed application for replacement title. Processing usually takes two to three weeks by mail.
What the Procedure Cannot Handle
The small estate affidavit is not a universal key. It fails completely if the gross value exceeds $100,000. It fails if there is real estate. It fails if a formal probate proceeding is already open. It also provides limited protection to the person presenting it. If you distribute assets based on the affidavit and later discover the gross value was actually higher than you estimated, you can be held personally liable for the overdistribution. The affidavit shifts risk onto the collector, not away from it. Institutions may also request additional documentation beyond the statute requires. A credit union might ask for a family tree. A brokerage firm might want a copy of the will even if the affidavit says no probate is pending. There is no legal remedy that forces an institution to accept the affidavit if they refuse, short of filing a petition with the court. That defeats the purpose of using the procedure in the first place, so negotiation is usually the only practical path. Come prepared with the statute citation, be polite, and ask to speak with a manager who has authority to override the frontline staff decision. When the estate is larger than the threshold or includes real property, the alternative is a formal probate administration. In Illinois, a simplified estate proceeding exists for estates over $100,000 that meet certain other criteria, but it still requires court involvement and an appointed representative. It is more expensive and takes longer, typically several months from filing to closing, compared to the few weeks required for an affidavit-based collection. The trade-off is that a court order carries more weight with reluctant institutions and provides broader legal protection for the personal representative.
For most modest estates under $100,000 without real estate, the Illinois Small Estate Affidavit remains the most practical tool available. It is not elegant, it does not protect against every mistake, and it will frustrate you at least once if you underestimate the gross value or overlook a beneficiary designation. But when the numbers fit and the paperwork is in order, it does what it promises without the cost and delay of full probate.