Why Most Insurance Agent Training Programs Are Wasted Money
I spent eight years running training programs for independent agents across three states before stepping back from the industry. The thing nobody wants to admit is that about 40% of what gets sold as Insurance Sales Agent Training is rehashed material dressed up with flashy slides and expensive facilitators. The agents who actually move the needle are the ones who treat training like a toolkit, not a curriculum. Here is what actually works, based on thousands of hours in the field watching agents succeed and fail at the same time.
The Reality of Insurance Sales Agent Training
Effective insurance sales agent training is built around three components that most programs miss or handle poorly: product knowledge under real time pressure, objection handling with actual prospects, and compliance awareness that does not get buried under legal jargon. That is it. Everything else is decoration. When I ran a cohort of new agents in 2019, I gave them a simple diagnostic test on day one. Not a fun icebreaker. A timed product quiz covering term life, whole life, annuities, and the basic health insurance categories. Forty-five percent of them failed. They had licenses. They had passed the state exam. They could not explain the difference between a guaranteed issue and a simplified issue policy without reading from notes. The training that followed was brutally practical. We cut the lecture time in half and replaced it with role-play scenarios using real call recordings from experienced agents. The recordings were not polished samples. They were actual calls where agents struggled, got rejected, and recovered. Agents took notes on the recovery techniques, not the opening pitch.
What Most Training Programs Get Wrong
The biggest mistake in Insurance Sales Agent Training is assuming that product knowledge transfer equals sales competence. These are two completely different skill sets. An agent can memorize every rider on a universal life policy and still freeze when a prospect says, "I need to think about it." Product knowledge gets you licensed. Tactical selling ability gets you paid. I saw this repeatedly. A training company in Florida charged agents $2,500 for a three-day workshop that focused heavily on scripting and closing techniques but barely touched actual policy comprehension. Six months later, those agents had higher activity metrics but also higher complaint rates. Compliance violations spiked because they were selling products they could not adequately explain. The program produced loud agents, not competent ones. Another common failure is the one-size-fits-all approach. A fresh agent who just passed their exam needs something entirely different from a crossover agent coming from banking or from an agent who has been selling for twelve years but never formalized their process. Good training groups agents by experience level and adjusts the pace accordingly. Most programs do not. They run the same material for everyone and wonder why the results are mediocre across the board.
Get the Full Details
How to Structure Training That Actually Produces Revenue-Generating Agents
Start with a needs assessment. Before you design or select any training module, find out where your agents are failing. Pull their sales data. Look at conversion rates by product type. Identify which prospects drop off and at what stage. If your agents are getting appointments but not closing, the problem is objection handling. If they are not getting appointments, the problem is lead generation and outreach, and no amount of product training will fix that. Module one should always be compliance and ethical selling. This is not a suggestion. It is the foundation. Agents who skip proper disclosure training later become liability problems. I once had an agent who missed a single suitability disclosure during a training exercise because the instructor rushed through that section. He repeated the same omission in his first real client meeting three months later. The client filed a complaint. The agent's license was suspended for forty-five days. The training company blamed the agent. The agent blamed the trainer. Nobody learned anything because the system was designed to produce closings, not professionals. After compliance, move into product mastery, but teach it differently than most programs do. Do not present product features as a list. Present them as solutions to specific client problems. Annuities are not a product category. They are the solution for a sixty-two-year-old who is worried about outliving their savings and has low risk tolerance. Term life is not a policy type. It is the solution for a thirty-four-year-old parent who needs income replacement for the next twenty years while the mortgage is being paid down.
This framing changes how agents remember and communicate the material. It also makes it significantly harder to confuse similar products during a client conversation, which reduces errors and complaints.
The Role-Play Component: Where Training Actually Happens
Role-play is where most programs cut corners. They set up a couple of practice conversations and call it done. Real role-play requires structured scenarios with specific objectives, timed runs, and detailed feedback using a standardized rubric. Without a rubric, feedback becomes vague and useless. "You did good" tells the agent nothing. "You handled the price objection correctly but jumped to closing before confirming the prospect understood the coverage limit" tells the agent exactly what to adjust. I developed a simple scoring system for role-play that tracked four variables: disclosure completeness, objection handling quality, product accuracy, and active listening indicators. Each variable scored one to five. Agents needed a minimum average of three point five across all four to pass. Anything below that triggered a mandatory re-run with a different scenario. It was strict. It produced better agents. One specific edge case that required a workaround involved agents training on cold calls who had never made a cold call before. The standard role-play setup used warm leads where the prospect already expressed interest. These agents passed every practice round comfortably. The first time they picked up the phone for an actual cold call, they could not function. Their training had not prepared them for the silence that follows the initial pitch when there is no existing relationship to fall back on.

The workaround was straightforward. I inserted a ten-minute silent pause in the role-play after the opening pitch and required the agent to continue without prompting from their training partner. The silence felt uncomfortable. It was supposed to. This built the tolerance for real cold-call dynamics that the standard scenarios completely missed. Agents who completed this modified training had a twenty-three percent higher conversion rate on their first actual cold-call week compared to agents who went through the standard role-play only.
Follow-Up and Reinforcement
Training does not end when the workshop closes. The learning retention curve for new insurance agents drops sharply after fourteen days without reinforcement. I recommend a structured follow-up schedule: a check-in call at seven days, a recorded call review at fourteen days, and a live group session at thirty days. This costs time and money, but the alternative is watching agents repeat the same mistakes in front of real clients. Recorded call reviews are the single most effective follow-up tool available. Agents hear themselves. They notice gaps that their trainers never caught. A typical review takes about twelve minutes per call, and I found that reviewing three to five calls per agent per month was the sweet spot for improvement without turning the process into an administrative burden.
Common Pitfalls to Avoid
Over-reliance on scripts. Scripts are useful for new agents who need structure, but agents who depend on them become brittle. When a prospect says something outside the script, the agent freezes. Train agents to understand the principles behind the script, not just to recite it. The principle for a needs analysis is different from the script line that follows it. The principle is uncovering the client's actual situation. The script line is just one way to get there. Ignoring the digital channel. Many training programs still focus almost exclusively on phone and in-person interactions. That is an outdated approach. A significant portion of insurance sales conversations now begin through email, chat, or social media. Training that does not cover digital prospect communication is incomplete. Agents need to know how to build rapport through text-based channels, how to schedule calls efficiently, and how to handle objections that come through written communication where tone and timing are different from voice-to-voice interaction. Not addressing agent burnout. Insurance sales is a high-rejection profession. Training programs almost never prepare agents for the psychological toll of repeated rejection. I included a brief module on resilience and realistic expectation setting in my programs because agents who burned out in their first six months were typically the ones who had been sold an unrealistic picture of easy success. They were unprepared for the actual day-to-day rhythm of the work.
What to Look for When Selecting or Building a Program
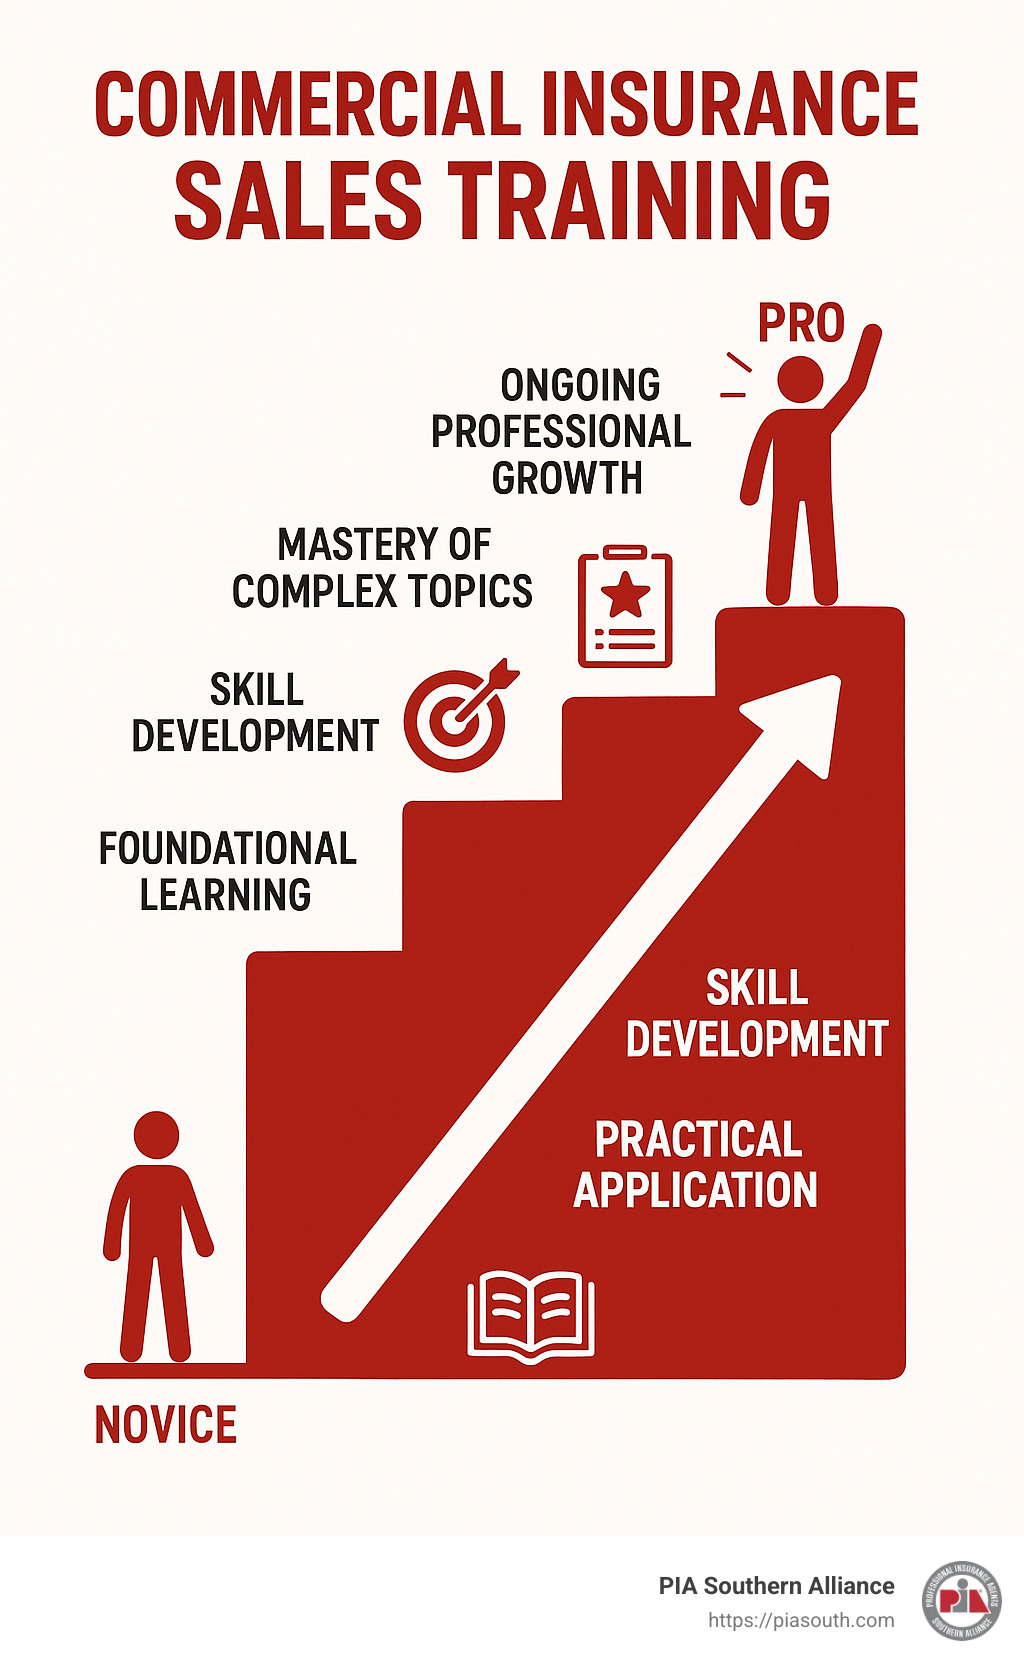
If you are choosing an existing Insurance Sales Agent Training program, evaluate it against these criteria: does it include compliance training that is current with recent regulatory changes, does it use real recorded calls rather than scripted demonstrations, does it provide follow-up support beyond the initial training period, and does it segment agents by experience level rather than running everyone through the same material? If you are building your own program internally, start with a skills gap analysis of your current team. The data from that analysis will tell you where to invest time and money and where you can skip training altogether. Agents who already demonstrate strong performance in a particular area do not need to sit through basic training on that topic. They need advanced modules or mentoring roles. Forcing high performers through remedial content creates resentment and wastes everyone's time. The market for training providers is large and poorly regulated. Some of the best training comes from experienced agents who have no marketing department and no slick website. They share what they learned the hard way, usually for free or at a modest fee. The content is often rougher but more honest than polished commercial programs. I have found that the most effective training combines structured commercial programs for foundational knowledge with informal mentorship from top-performing agents for practical application.
A Note on Measuring Results
Most training programs measure success by completion rates and satisfaction scores. These metrics are almost entirely meaningless. Completion rates tell you that agents showed up. Satisfaction scores tell you that the food was decent. Neither metric predicts whether an agent will sell more insurance after the training. Measure training effectiveness by comparing pre-training and post-training performance data over a ninety-day window. Track new policies sold, average premium per policy, complaint rates, and conversion rates at each stage of the sales process. If the numbers do not improve, the training did not work, regardless of how well agents rated the experience. Adjust the program based on the data and retrain. This cycle of measurement, adjustment, and retraining is what separates programs that produce results from programs that exist primarily as revenue streams for training companies. The agents who get the most out of any Insurance Sales Agent Training are the ones who come in with specific problems they want to solve, who ask uncomfortable questions during role-play, and who insist on hearing about failures as often as they hear about successes. The rest just absorb information and hope it sticks. Hope is not a training strategy.