Building a Functional Loan Tracker in Excel
Most free templates you find online are poorly structured, use broken formulas, or lack the basic components needed for real loan management. I've spent years fixing these for people who downloaded them and then realized they couldn't track delinquencies, calculate accurate amortization schedules, or even filter by loan officer without the whole sheet falling apart. The core problem is that template authors rarely have actual lending operations experience. They build what looks good visually and call it done. A proper loan management system needs at minimum five sheets working together: a Loan Master register, a Payment Schedule calculator, a Borrower Directory, an Amortization Engine, and an Aging/Delinquency Tracker. If any one of those pieces is missing or superficial, the template stops being useful the moment you move past your first three loans.
Loan Management System Excel Template Free Download
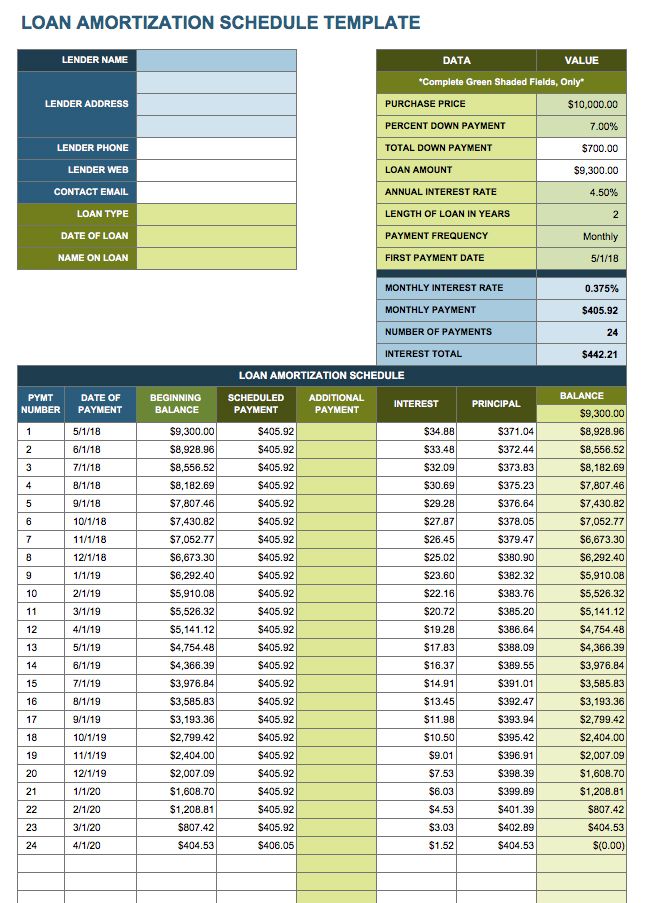
When you're looking for a Loan Management System Excel Template Free Download, you need to know what to evaluate before opening the file. Check whether the amortization formula uses the actual PMT function with correct rate and period inputs. Many templates substitute a simplified interest calculation that rounds aggressively and drifts from the true balance over time. On my end, I once had a template where the monthly payment was calculated correctly for the first six months, then the running balance jumped by $43 because the author used cell references that pointed to hardcoded values instead of dynamic cells. The fix was replacing those references with absolute row anchors using structured table references so the formula recalculated properly when rows were inserted. Here's what a working structure actually looks like. The Loan Master sheet should contain: Loan ID, Borrower Name, Principal Amount, Annual Interest Rate, Loan Start Date, Term in Months, Monthly Payment (calculated via PMT), Remaining Balance, Status, and Next Payment Date. The Payment Schedule sheet auto-generates a month-by-month breakdown using INDEX-MATCH or SEQUENCE functions, showing how each payment splits between principal and interest. The Amortization Engine recalculates based on any changes to the principal or rate. The Delinquency Tracker flags payments more than 30, 60, or 90 days past due using simple DATE calculations comparing Next Payment Date against TODAY().
The Specific Edge Cases That Break Free Templates
I work with small credit unions and independent lenders, and the gap between what a free template handles and what actually happens in a lending operation is where most people get burned. Here are the ones that come up constantly. Partial payments and application order: Most templates assume a borrower pays the full monthly amount on time or not at all. Real life involves $200 partial payments, late fees that get waived, and payments applied to different loan products. When I built a system for a community development lender, they processed about 18% of payments as partial during the first quarter. The template had no logic for that. I added a Payment Allocation section with a priority order: late fees first, then current period interest, then current period principal, then prior period interest, then prior period principal. Without that order, your delinquency aging is wrong. Varying compounding frequencies: Some loans compound monthly, others daily, some use simple interest. Free templates almost universally assume monthly compounding. If you're managing loans with different compounding structures, you need separate columns or a lookup table that maps each loan to its compounding method. I ended up building a small lookup matrix using XLOOKUP against a separate sheet that defined the compounding convention for each loan type, then feeding that into the interest calculation.
Get the Full Details

Balloon payments and irregular terms: A balloon payment at the end of a term changes the final payment amount entirely. Free templates calculate equal monthly payments across the full term and break when the last payment doesn't match. I handle this by adding a flag column for balloon loans and a conditional formula that sets the final payment to Remaining Balance plus that period's interest instead of the standard PMT output. Grace periods: Some loans have a 30-day grace period before interest starts accruing. The standard amortization formula doesn't account for this. You need to offset the payment schedule start date by the grace period length and adjust the first interest calculation accordingly. I use a helper column that subtracts the Grace Days from the Loan Start Date to get the Accrual Start Date, then references that in the interest computation.
What Free Templates Usually Get Wrong
The most common structural flaw I see is the use of merged cells for formatting. Merged cells break sorting, filtering, and any formula that references the range. A template that looks clean because the headers are merged across columns is a template you'll spend two hours unmerging and restructuring. Unmerge everything and use center-across-selection instead. It produces the same visual result without the functional damage. Another issue is hardcoded ranges in formulas. =SUM(A2:A100) assumes you'll never have more than 98 loans. When you do, the formula silently stops including new entries. Use Excel Tables instead. They expand automatically and your formulas reference the table structure, which means the calculation range grows with your data. Color coding based on manual cell fills rather than conditional formatting is the third major problem. If someone colors a cell yellow to indicate a payment is due soon, that color means nothing unless you click into the cell. Conditional formatting rules that check the actual date value are self-documenting and update dynamically.
My Practical Approach to Building One
When I build or audit a loan management template, I start with the data requirements before writing a single formula. I list out every piece of information that must exist for each loan, every calculation that needs to happen, and every report someone in the operation would ask for. Then I build backward from the reports. If a lender wants a delinquency report by loan officer, the underlying data model needs to support that aggregation. Too many templates are built top-down from a desired layout rather than bottom-up from the data relationships. For the Payment Schedule sheet specifically, I use a recursive calculation approach where each row's remaining balance equals the previous row's balance minus that row's principal portion. The principal portion is calculated as the Payment minus the Interest, where Interest equals Previous Balance times the Monthly Rate. This mirrors how actual loan servicers compute balances and produces results that match lender documentation within a cent or two. I also add a Validation Rules sheet that checks for common data entry errors: negative principal amounts, interest rates above 50%, payment dates before the loan start date, and monthly payments lower than the accrued interest for that period. When a payment is lower than the accrued interest, the balance increases instead of decreases, which is called negative amortization and most free templates don't handle it. Adding that check prevents silent data corruption.

Where Free Templates Completely Fail
Here's what I won't pretend a free Excel template can do: it cannot replace a dedicated loan servicing platform if you're managing more than roughly 50 active loans simultaneously. The template breaks down at that scale because Excel is not a database. Concurrent access becomes a problem, audit trails don't exist, and error correction requires manual intervention on every change. If your operation processes more than 200 loans per year with multiple staff entering data, you're better off using actual loan management software. Templates also fail at regulatory compliance requirements. If you're subject to TILA disclosure rules, RESPA requirements, or state-specific lending regulations, an Excel template provides no mechanism for generating compliant documents or maintaining the audit trail those regulations require. That's a software problem, not a spreadsheet problem. For single lenders, credit union members departments, or small community lenders under 50 loans outstanding, a well-built template works fine. The key is building it right from the start rather than downloading something and hoping it fits your situation. Start with the structure I outlined above, use Excel Tables everywhere, avoid merged cells entirely, implement the negative amortization check, and make sure your amortization formulas match industry-standard calculations before you put any real loan data into it.