Building a Payment Schedule That Actually Matches Your Loan Documents
Most people download a spreadsheet and immediately run into the same problem: the calculated interest doesn't match what their bank statement says. I spent three weeks reconciling a client's amortization table against their lender's actual schedule before I figured out what was going wrong. The issue usually comes down to how the compounding frequency interacts with the payment timing. Here is what I learned doing this kind of work. A Loan Payment Schedule Template needs to handle more than just basic principal and interest calculations. Real loan documents contain quirks like grace period handling, partial month first payments, and varying day-count conventions that most generic templates ignore entirely.
Using a Loan Payment Schedule Template for Real Loans
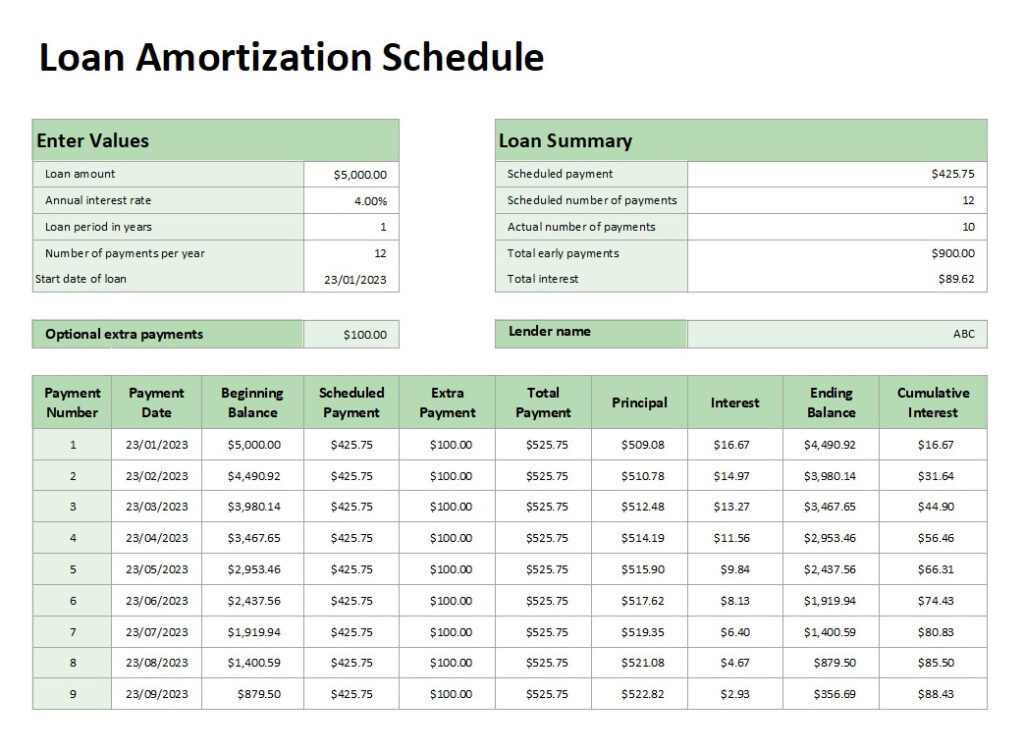
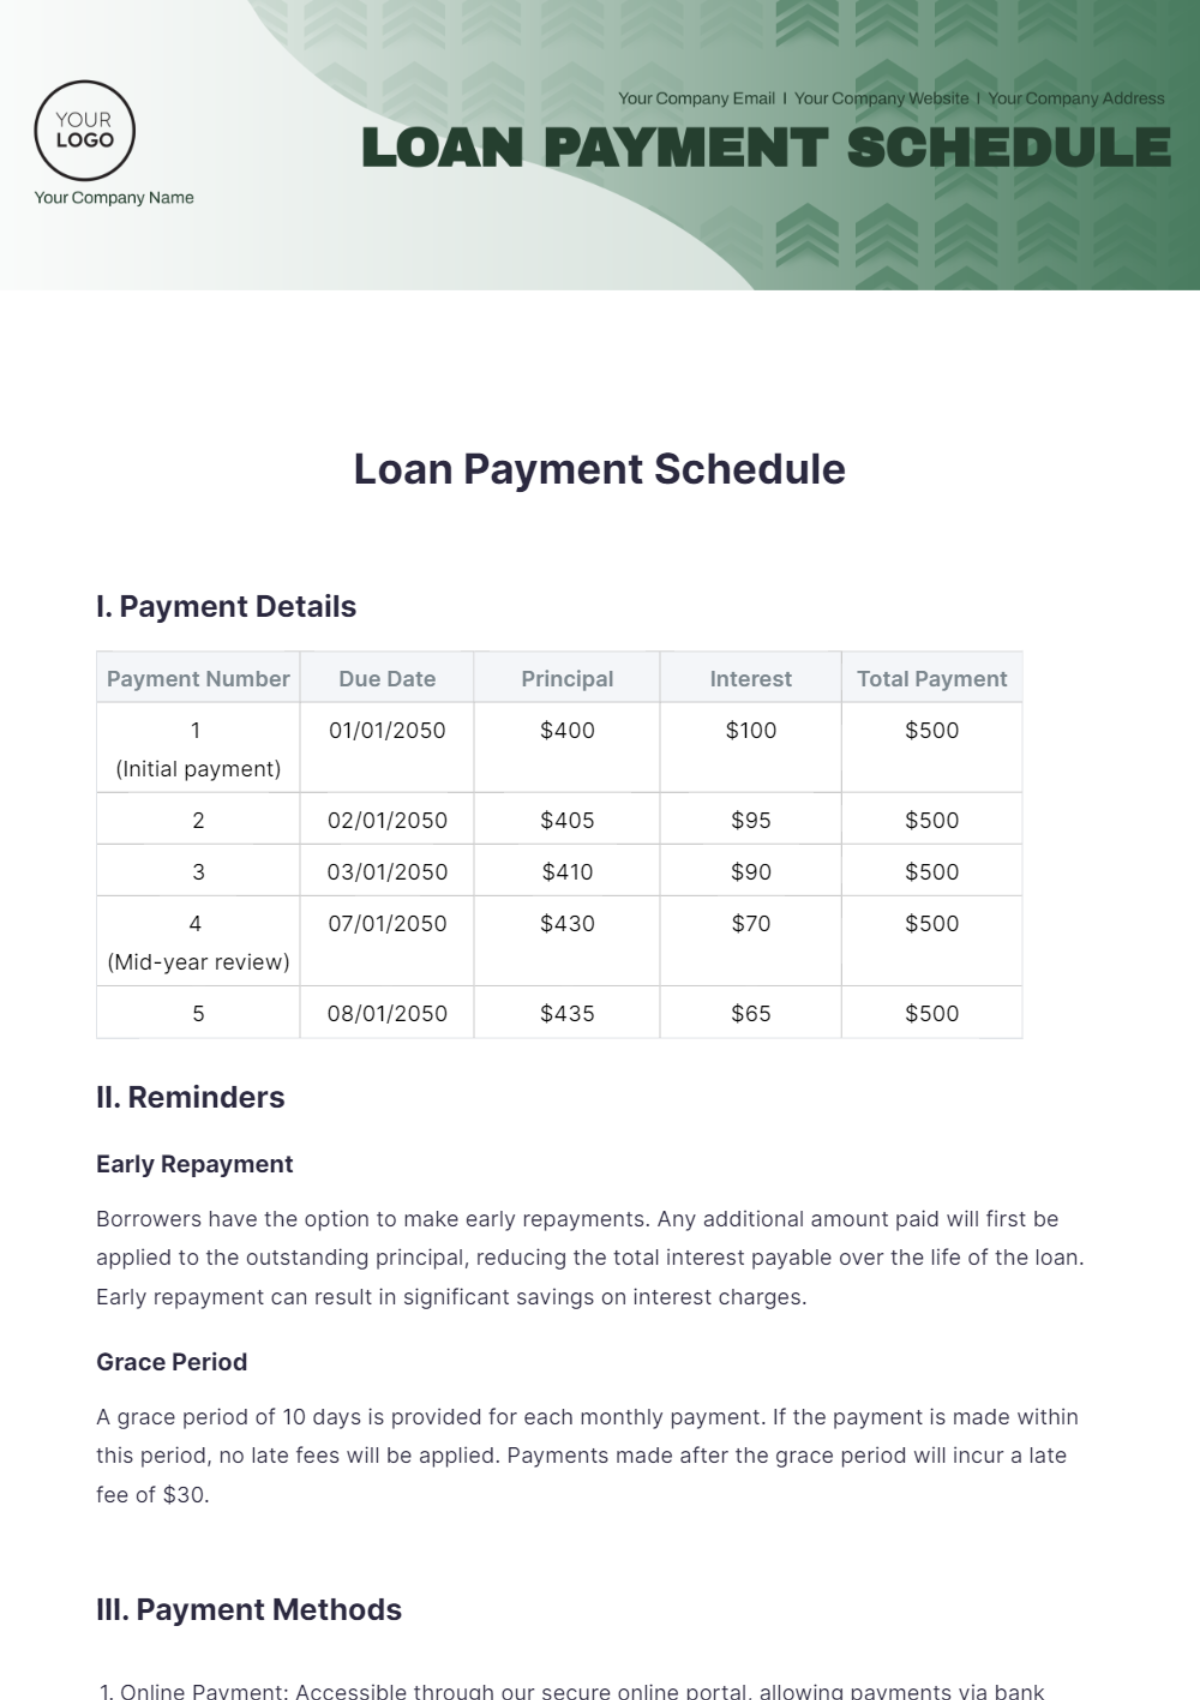
Start by laying out the core columns you actually need. The essential ones are payment number, payment date, beginning balance, total payment amount, principal portion, interest portion, and ending balance. Some people add columns for cumulative principal paid, cumulative interest paid, and remaining term, but those are nice-to-haves rather than must-haves. The formula for the regular payment amount uses the standard annuity calculation. You divide the annual interest rate by the number of payments per year to get your periodic rate. Then apply the formula: payment equals the loan amount multiplied by the periodic rate, all divided by one minus one over one plus the periodic rate raised to the power of total number of payments. In Excel or Google Sheets, this is the PMT function with a negative sign if you want the payment to display as a positive number. I ran into a specific edge case with a commercial real estate loan last year. The loan had a 364-day year convention instead of the more common 360 or 365. My template was calculating slightly higher interest each period because it assumed a standard 365-day year. The workaround was straightforward: I added a manual day-count adjustment column that divided the actual days in each period by 364 instead of 365. This took the variance down from about twelve dollars per payment to zero. Without that adjustment, the schedule diverged from the lender's by roughly one hundred eighty dollars over the full term.
The Math Behind Each Payment
Understanding how each payment breaks down between principal and interest saves you from accepting a schedule at face value. The interest portion of any given payment equals the beginning balance for that period multiplied by the periodic rate. The principal portion is whatever remains after you subtract the interest from the total payment amount. This means early payments are heavily weighted toward interest, which is why refinancing decisions in the first few years of a loan rarely make financial sense. One counter-intuitive thing most people miss: the order in which you apply extra payments matters significantly. If you make an additional principal-only payment and your loan document specifies that extra payments go toward future interest first, you are not actually reducing your principal faster than scheduled. You should verify whether the lender applies prepayments to principal or interest before sending extra money. I found this out the hard way when a borrower complained their balance had not dropped as much as expected after making several extra payments. Another common pitfall involves the first payment date. Some loans have a partial first period where the first payment is due less than a full cycle after closing. The interest calculation for that first period is proportionally smaller, but the payment amount stays the same. This creates a slightly larger principal reduction in period one, which then cascades through the rest of the schedule. Most templates handle this correctly by calculating interest for the actual number of days in the first period rather than assuming a full period. If your template assumes a full period from day one, expect the early balances to drift from the actual loan documents.
Get the Full Details

Setting Up the Template Structure
Open a blank spreadsheet and create your column headers in row one. Put payment number in column A, payment date in column B, beginning balance in column C, total payment in column D, principal portion in column E, interest portion in column F, and ending balance in column G. Format the date column to display in whatever format your local conventions require. For the payment number column, start with one in cell A2 and drag down to however many payments your loan has. A standard thirty-year mortgage has three hundred sixty payments. If you are working with a fifteen-year loan, that is one hundred eighty rows. Keep the column simple; do not try to make it calculate automatically unless your template needs to handle multiple loan types. The payment date column needs careful attention. Start with the actual first payment date from your loan documents. For subsequent rows, add the payment frequency to the previous date. Monthly payments mean adding one month. Biweekly payments mean adding fourteen days. The tricky part is handling end-of-month dates. If your first payment is due on January 31st and you add one month, February does not have a 31st. Use a date function that rolls to the last valid day of the month rather than simply adding a fixed number of days.
For the beginning balance column, put the original loan amount in the first row. For subsequent rows, reference the ending balance from the row above. This creates the chain that drives the entire calculation forward. The total payment column is where most people make mistakes. If your loan has a fixed payment, you can use a single absolute reference to the payment amount throughout the entire column. Use a dollar sign reference like $D$1 so that when you drag the formula down, it always points back to the same cell containing the payment amount. Do not hardcode the payment value into each row; that approach breaks when you need to adjust the payment later. The interest portion formula multiplies the beginning balance by the periodic rate. Get the periodic rate by dividing the annual rate by the number of payments per year. Store the annual rate in a single cell near the top of your spreadsheet and reference that cell throughout your formulas. This makes adjustments trivial when you are comparing different loan scenarios.
The principal portion formula subtracts the interest portion from the total payment. Keep this simple: total payment minus interest equals principal. No special handling needed unless you are dealing with an adjustable-rate loan where the payment changes periodically.
Common Problems and How to Fix Them
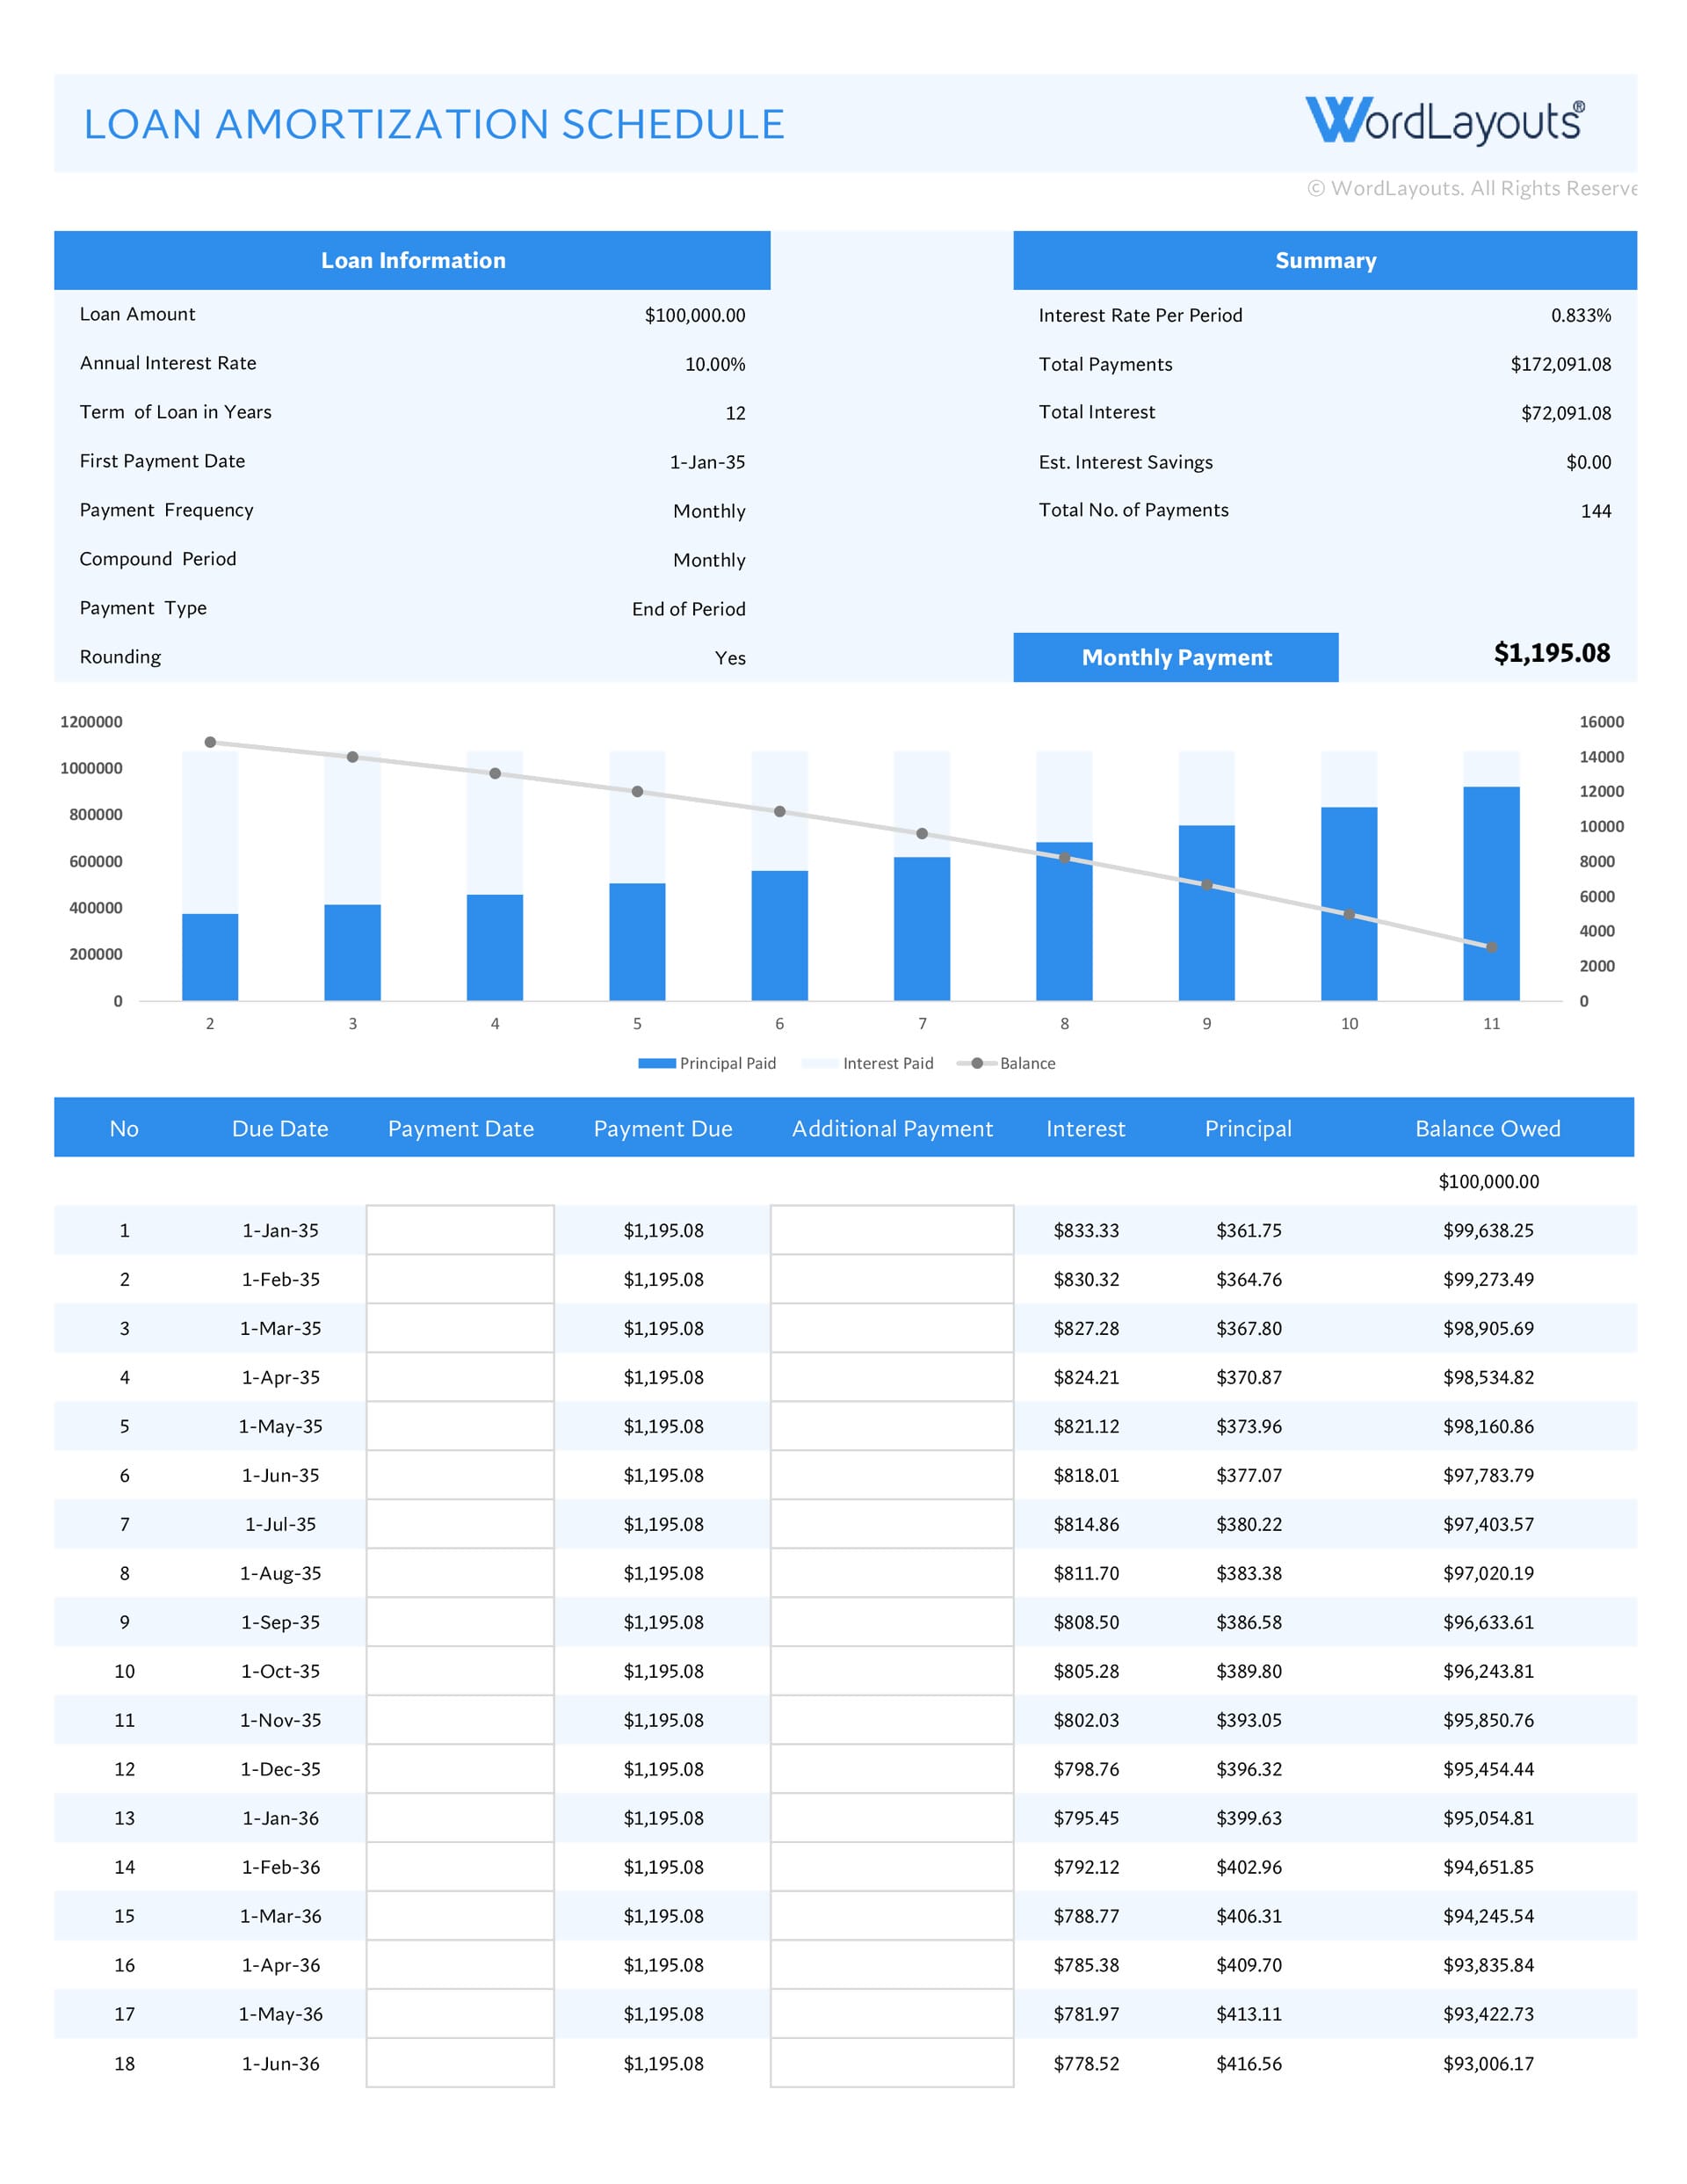
Round-off error is a persistent issue in amortization schedules. Each payment calculation produces decimals that get rounded to cents for display purposes. Those rounding differences accumulate over hundreds of payments. A well-built template rounds each interest and principal calculation to two decimal places immediately, rather than letting rounding errors propagate through the entire schedule. The final payment will typically show a small adjustment to account for accumulated rounding. Another problem involves loans with prepaid interest. When you close on a loan, the first payment might not be due for forty-five days instead of thirty. During those extra fifteen days, interest accrues but no payment is made. Some lenders collect this as prepaid interest at closing rather than building it into the payment schedule. If your template does not account for this gap, the payment dates will be misaligned with the actual loan terms. Add a note in the schedule indicating which payment covers the extended first period, or split the first period into two rows: one for the accrual period and one for the actual payment. I encountered a situation with a student loan refinancing where the lender used a 30/360 day-count convention instead of actual/365. The difference seemed minor at first, but over the life of the loan it produced a variance of about forty dollars in total interest. Verify which day-count convention your loan uses before building your schedule. If the lender provides an amortization table, compare your template output against theirs period by period to catch convention mismatches early.
Adjustable-rate loans introduce additional complexity. The payment amount changes at each adjustment period based on the index value plus the margin. A basic template with a single fixed payment formula will not handle this correctly. You need to either create separate sections in your spreadsheet for each rate period or use conditional logic that changes the payment amount when the adjustment date arrives. This usually means adding columns for the new rate, the new payment amount, and the recalculation date.
Validating Your Schedule Against Loan Documents
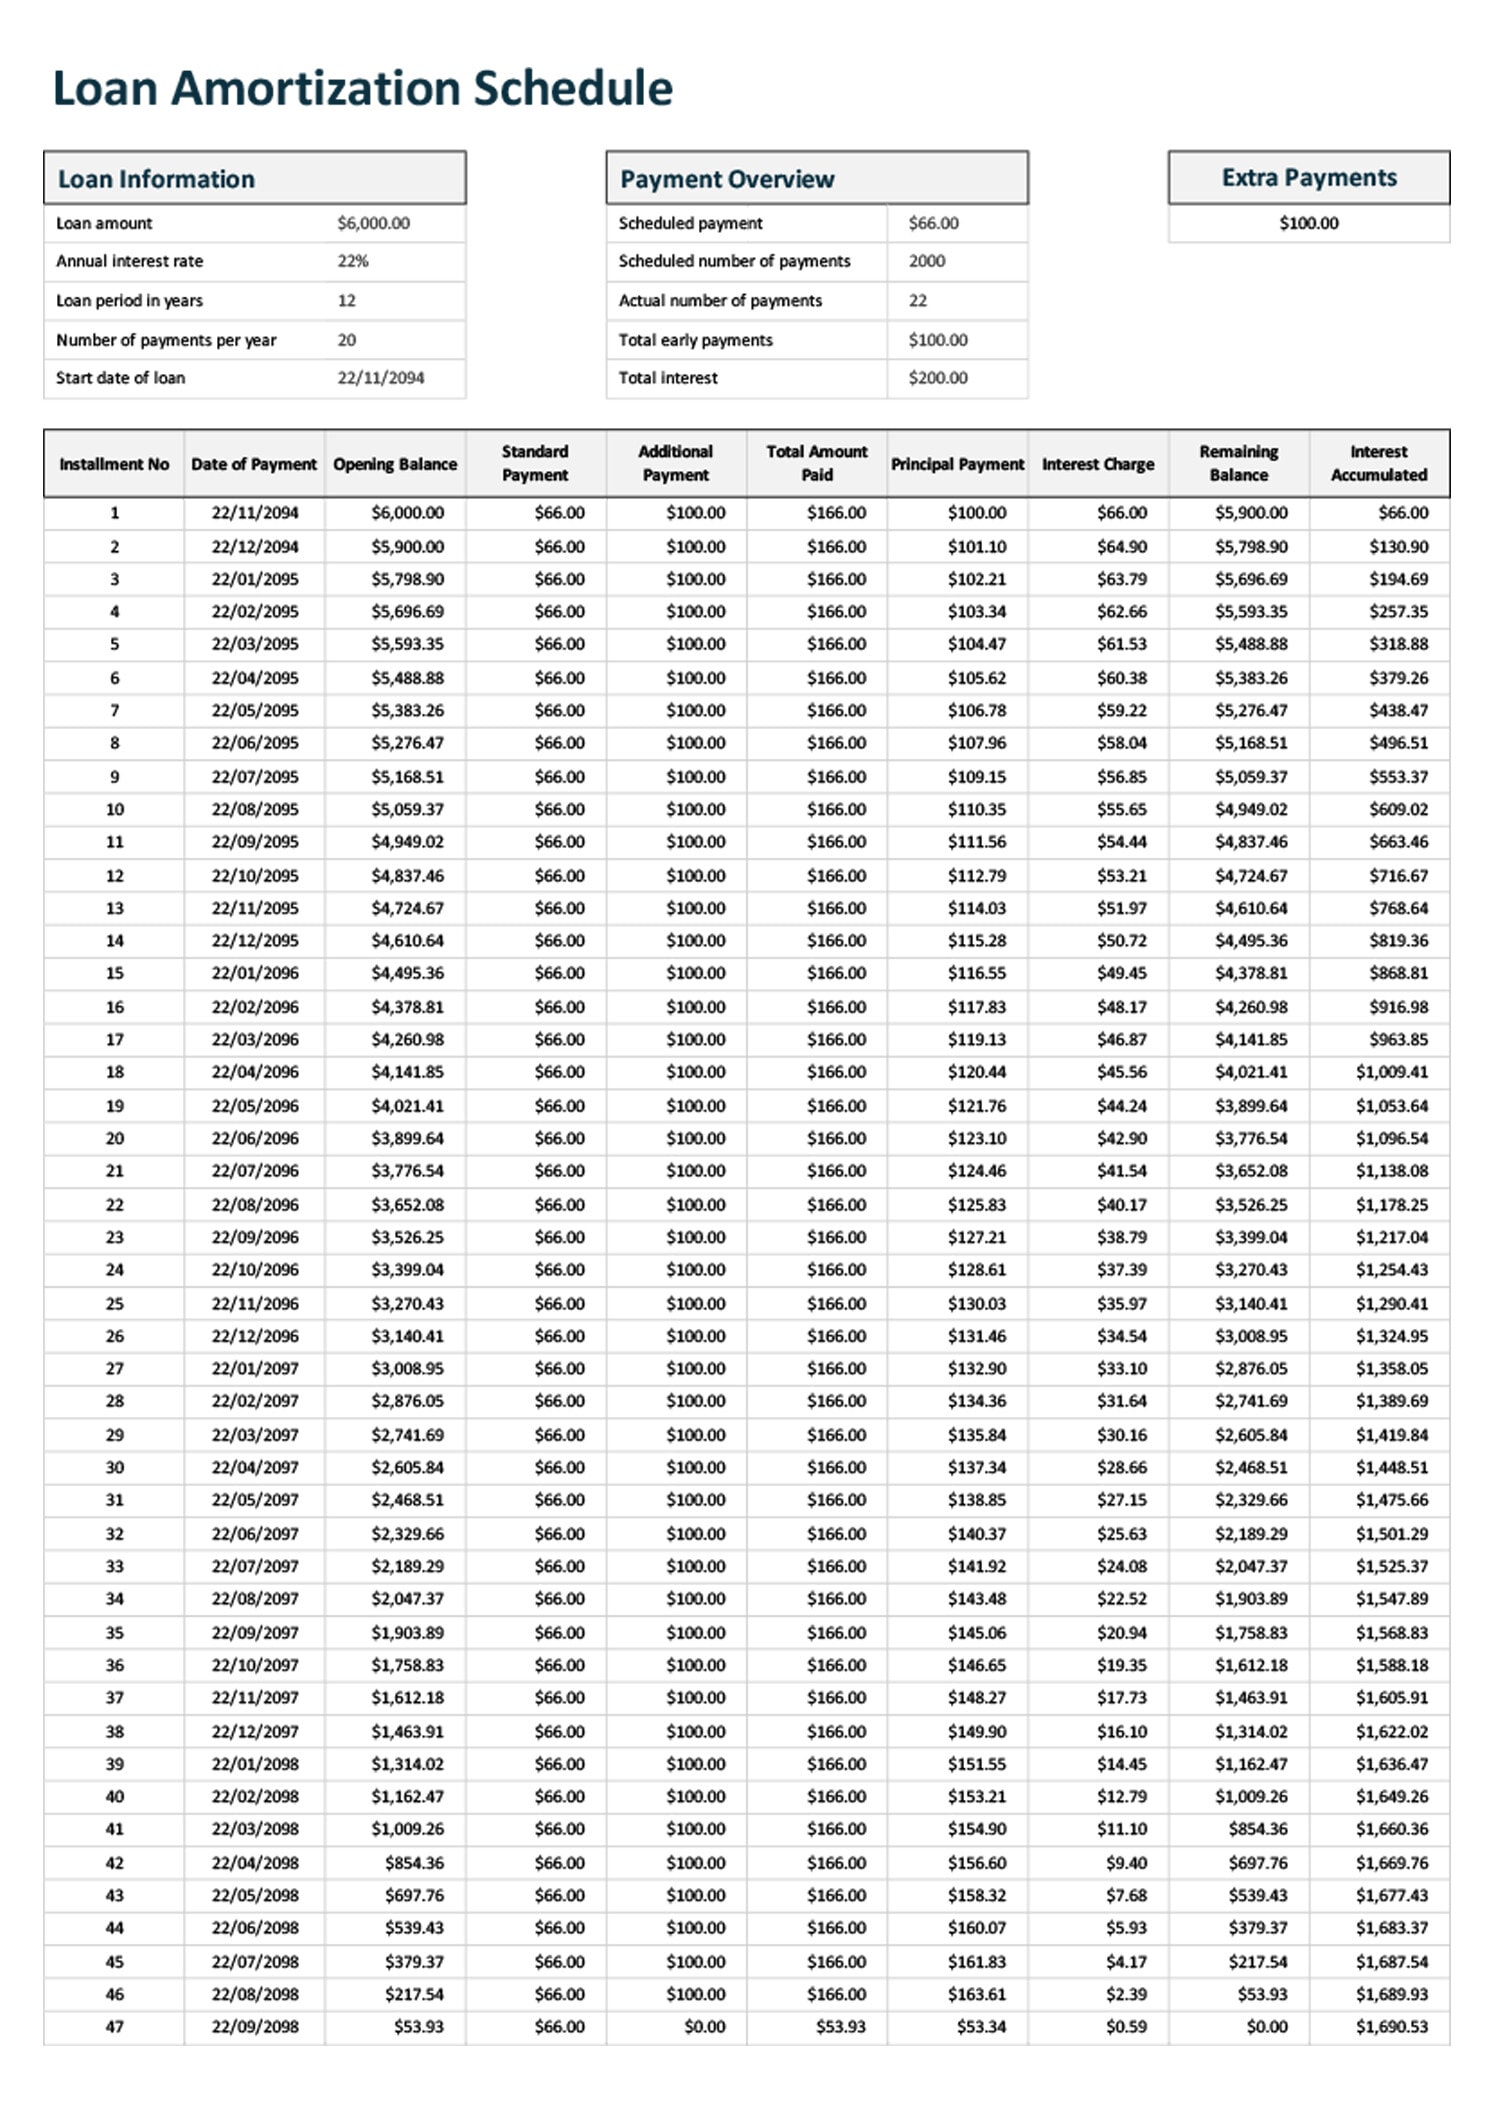
Once you have built the template, cross-check it against the actual loan documents. Start with the first five payments and verify that the beginning balance, payment date, and ending balance all match. Then jump ahead to the middle of the schedule and verify a few payments there. Finally, check the last payment to ensure the ending balance reaches zero or the expected balloon amount. If your schedule shows a non-zero balance at the end, investigate the discrepancy. The most common causes are incorrect payment frequency assumptions, missing fees rolled into the balance, or rounding differences. A variance of one or two dollars at the end is normal and usually resolved by adjusting the final payment amount. A variance larger than five dollars indicates a structural error in the template that needs correction. For loans with points or origination fees, verify whether the lender amortizes those costs separately or incorporates them into the payment calculation. Some loan estimates show the interest rate including points, while others display a discount rate separately. Mixing these up produces a schedule that looks correct but calculates the wrong numbers.
When a Template Is Not Enough
A spreadsheet template works well for fixed-rate loans with standard terms. It breaks down quickly with complex loan structures like interest-only periods, graduated payment plans, or loans with multiple adjustment caps. If you are dealing with an investment property loan that has a five-year interest-only period followed by a fully amortizing remainder, the template needs significant customization to handle the two-phase structure correctly. For high-volume situations where you need to generate schedules for dozens of loans, consider using dedicated loan servicing software rather than maintaining individual spreadsheets. The setup time for proper software usually pays for itself within a few weeks of regular use. Spreadsheet templates are fine for one-off calculations or small-scale personal use, but they do not scale well beyond that. Some lenders provide their own amortization calculators online. These are often sufficient for basic verification purposes, but they rarely export data in a format that integrates cleanly with your accounting system. If you need to import payment schedules into accounting software, building your own template gives you control over the output format and data structure.