How I Actually Run a Materiality Assessment Example Without Losing My Mind
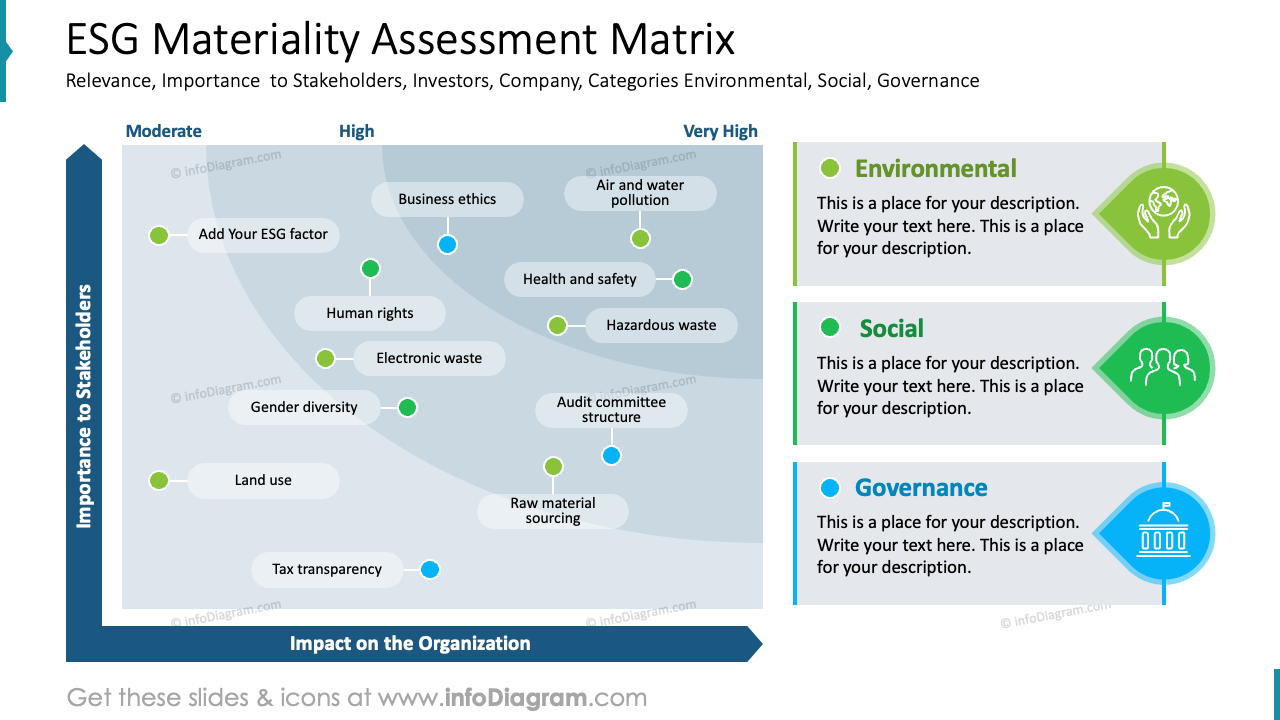
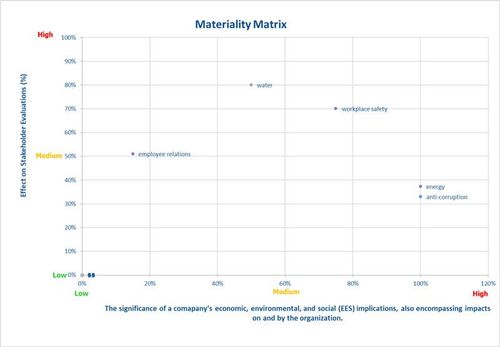
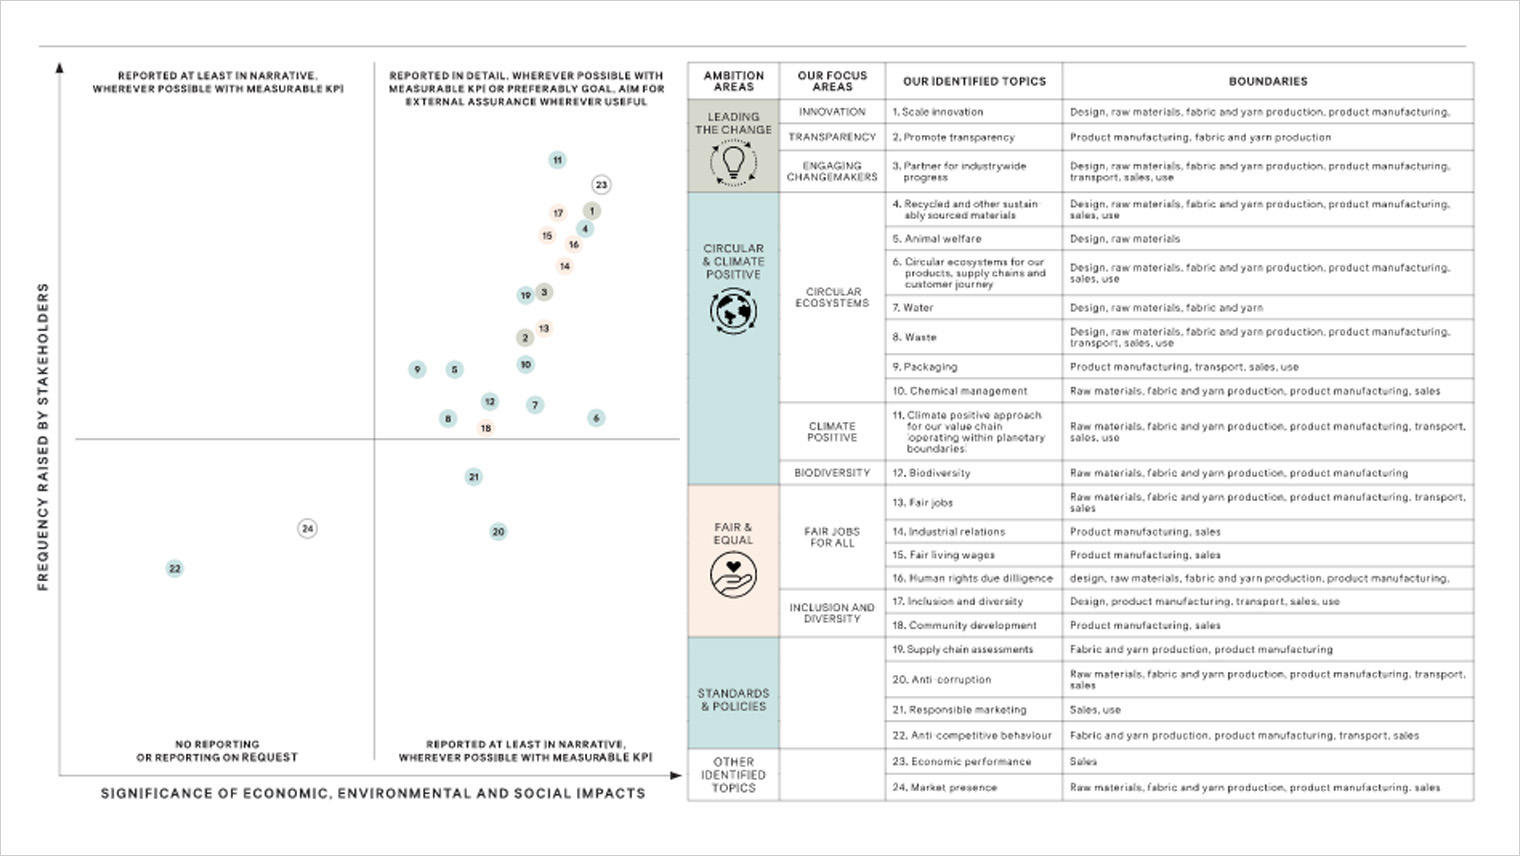
I spent three years doing these for mid-cap manufacturers before I figured out that the standard methodology consultants sell doesn't work in practice. The gap between theory and execution is where most people get stuck. A Materiality Assessment Example that looks clean on paper usually falls apart the moment you try to apply it to a company with actual operational complexity. Let me walk through what actually happens when you run one of these, starting with the part nobody talks about: the stakeholder interview phase.
Common Materiality Assessment Example Pitfalls
Here is the thing that catches everyone off guard. Most teams treat the scoring matrix as if it is a mathematical exercise. It is not. It is a political instrument dressed up in statistics. I watched a perfectly structured assessment get torpedoed because the CFO and the Head of Supply Chain had fundamentally different definitions of what "significant" meant, and nobody had resolved that before the scoring started. The workaround I use now is to separate the definitional phase from the scoring phase entirely. I spend two full days just getting people to agree on what the criteria mean before any numbers get assigned. This usually adds about a week to the timeline but cuts the revision cycles down from four rounds to one. The initial friction feels uncomfortable, but it saves approximately 40 hours of back-and-forth later. You need to establish clear scoring dimensions upfront. Impact magnitude, likelihood, stakeholder concern level, regulatory exposure, reputational risk, and financial materiality. Each dimension needs a five-point scale with explicit anchors. "High impact" means something different to a compliance officer than it does to a investor relations team member. Write the anchors so explicitly that a new hire could score the same way as a veteran.
Running the Assessment: The Practical Steps
Start with desk research that actually matters. Most people skip this or do it half-heartedly. Pull the GRI standards, SASB industry metrics, and the latest EU CSRD technical screening criteria. Map them against your company's actual operations line by line. This usually takes about six to eight hours for a mid-size operation, but it prevents the embarrassment of missing a material topic that a regulator already flagged elsewhere in the industry. Then move to stakeholder mapping. Identify internal and external stakeholders who have genuine information about each potential topic. Not the obvious ones. Not just the C-suite. The procurement manager who deals with forced labor audits weekly knows more about supply chain human rights risk than most sustainability directors. The facility engineer who handles chemical storage knows more about environmental impact than the ESG report writer. I learned this the hard way during a materials assessment for a textiles manufacturer. We had mapped "water usage" as medium priority based on industry benchmarks. Then we interviewed the wastewater treatment operator, and he showed us data proving that local regulatory thresholds were being approached in two of our three facilities. We bumped water to high materiality and had to revise the entire assessment. That conversation took forty-five minutes. Without it, we would have published a materially deficient report.
Get the Full Details
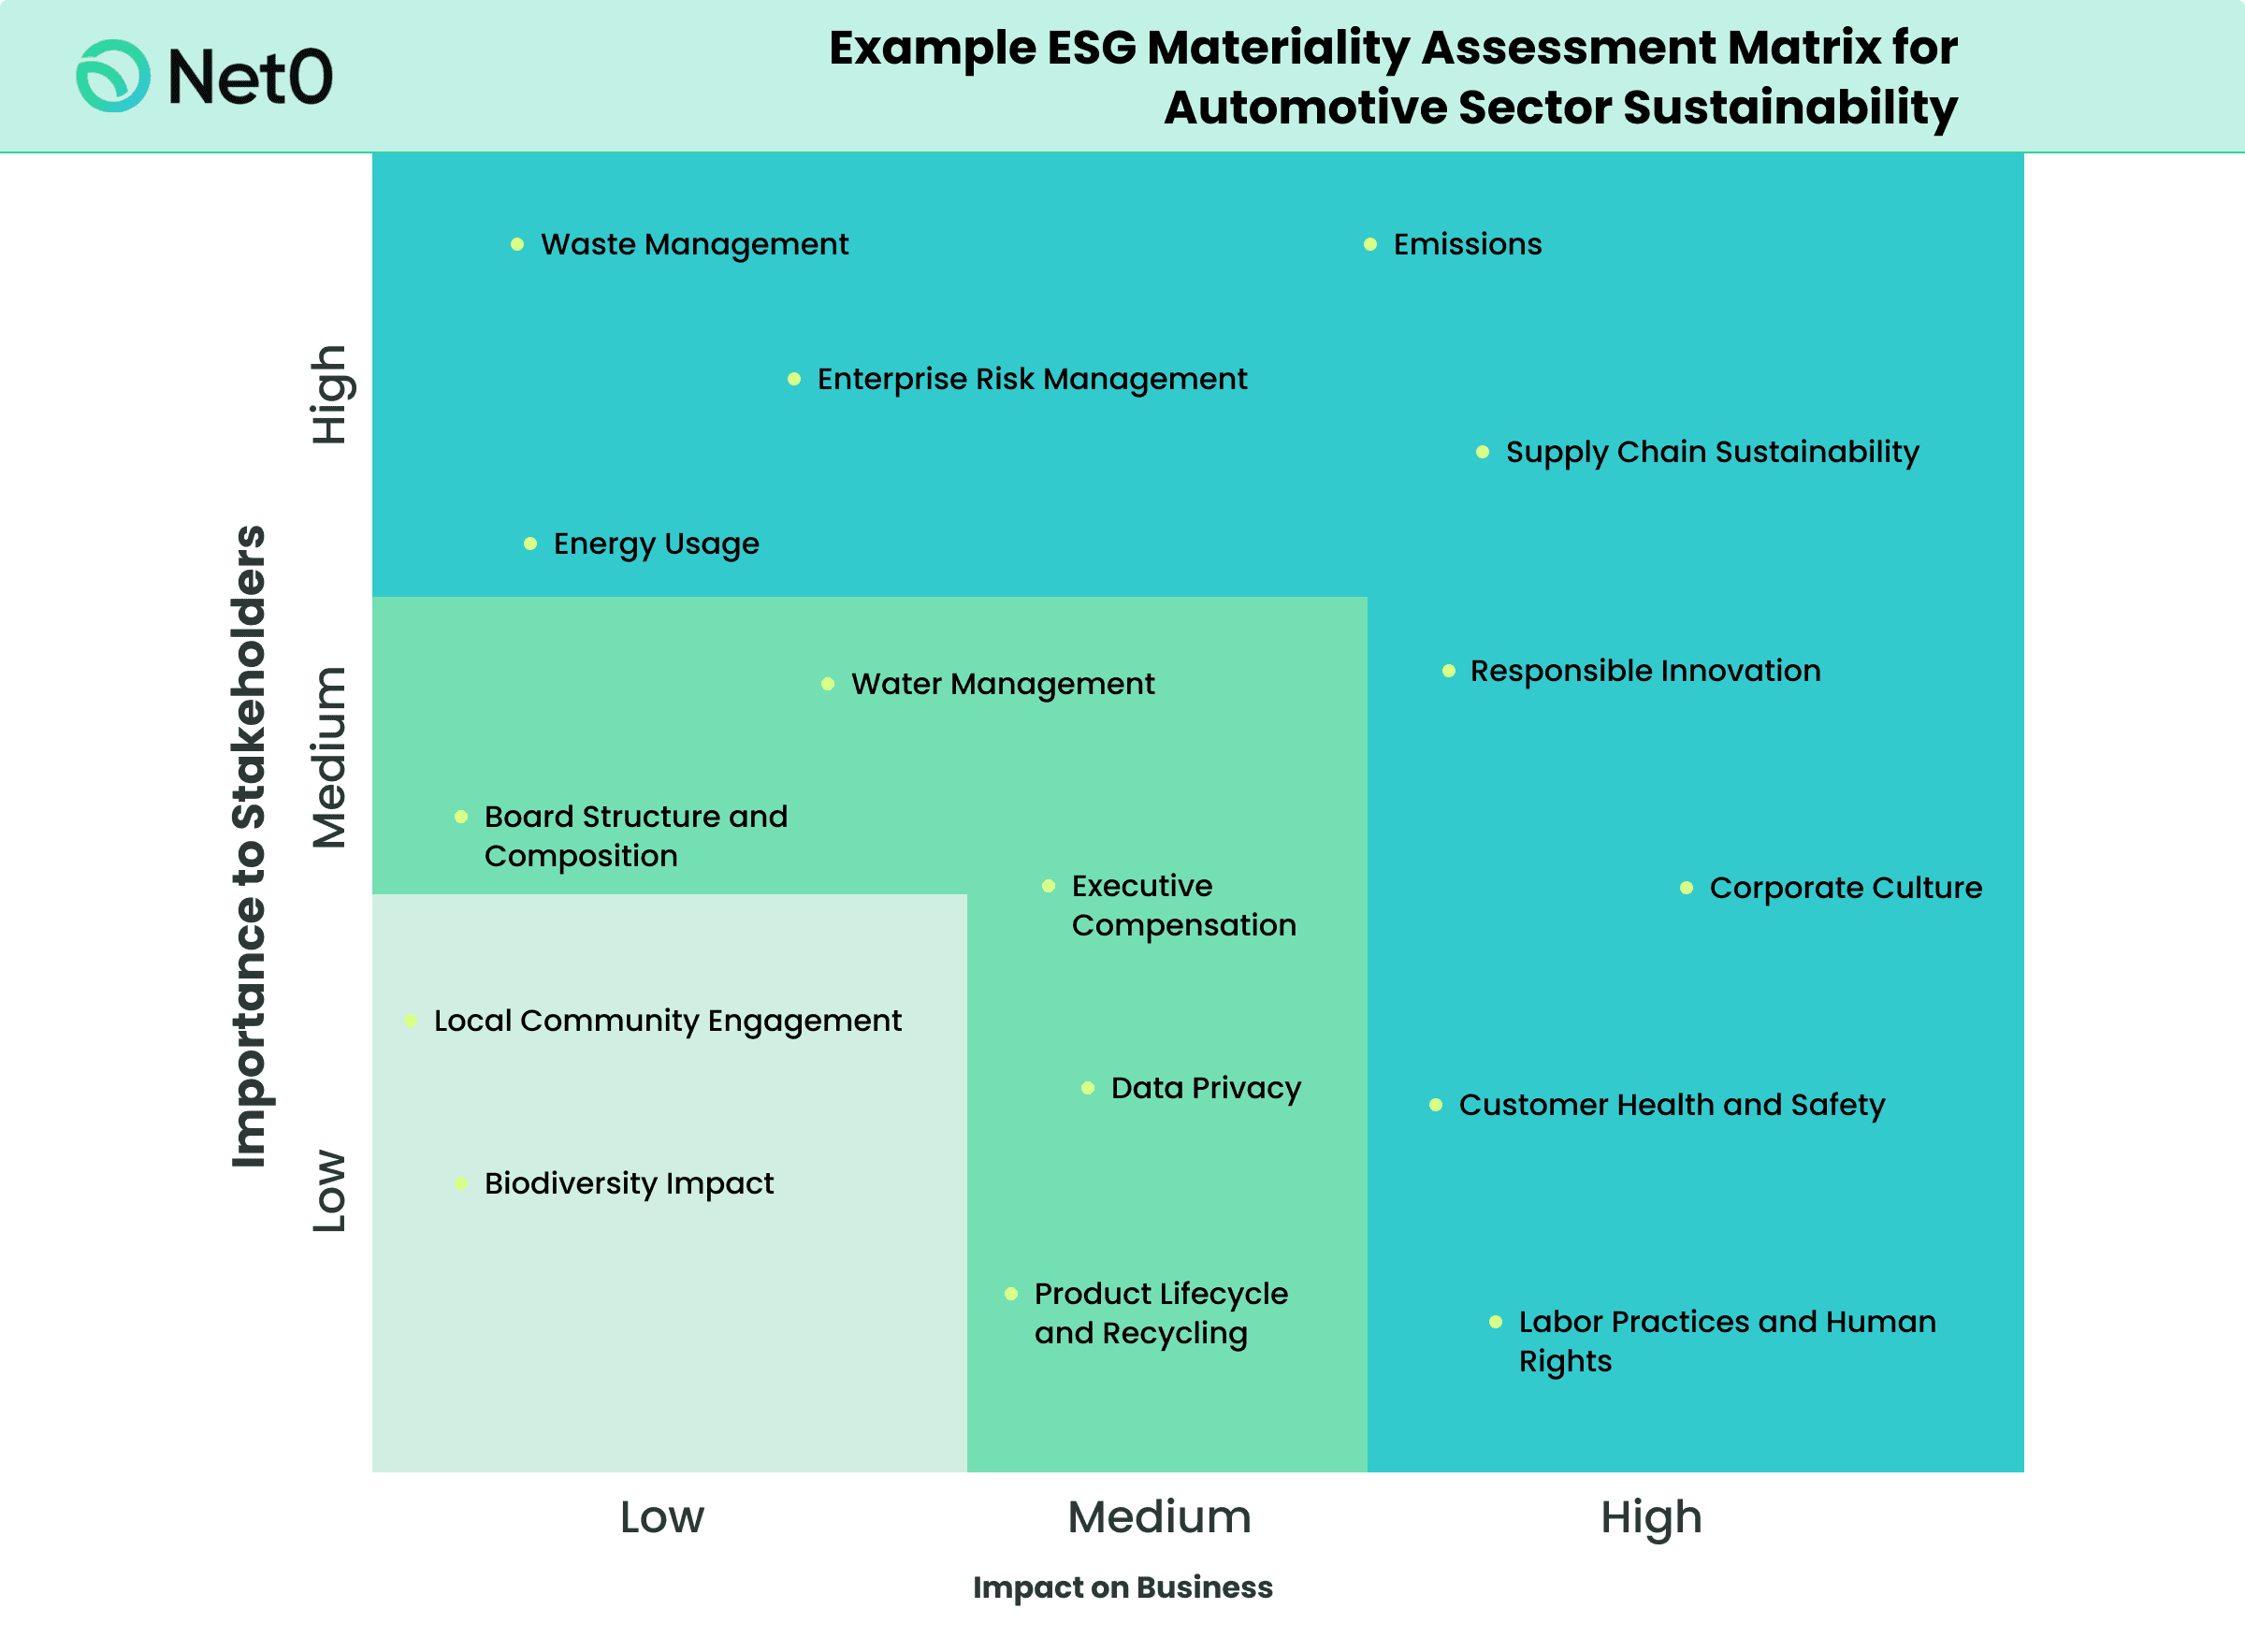
Design the scoring workshop with real constraints. Time-box each topic discussion to fifteen minutes. If people cannot reach consensus in that window, escalate to a defined arbitration process rather than letting it drag on. I use a simple rule: if two senior stakeholders disagree, the third senior stakeholder breaks the tie, and their reasoning must be documented. This prevents analysis paralysis and keeps the workshop moving.
Scoring and Validation: Where Most People Mess Up
The scoring phase is where assumptions hide. Most teams average the scores across stakeholders without checking for divergence. High divergence is information, not noise. If operations scores a topic as high impact but finance scores it as low financial relevance, that gap tells you something important about organizational blind spots. Run a sensitivity analysis on your scoring weights. Change the weight of "regulatory exposure" from 20 percent to 30 percent and see how the results shift. If the ranking changes dramatically, your assessment is more sensitive to that assumption than you realized. Document this explicitly in your methodology section. It shows rigor and protects you when someone questions the results later. Validate the output against actual company data, not just theoretical frameworks. Cross-reference your scored topics with incident reports, audit findings, litigation exposure, and customer complaints. I once found that a topic scored as low materiality by the workshop team had generated seventeen safety incidents in the previous fiscal year. The disconnect was staggering. The scoring had been based on projected risk, not realized harm.
This cross-referencing step usually takes about three to four hours for a company of moderate complexity. It prevents the publication of assessments that look theoretically sound but ignore operational reality. The effort pays for itself the first time a regulator or activist investor cites your assessment and finds the discrepancy.
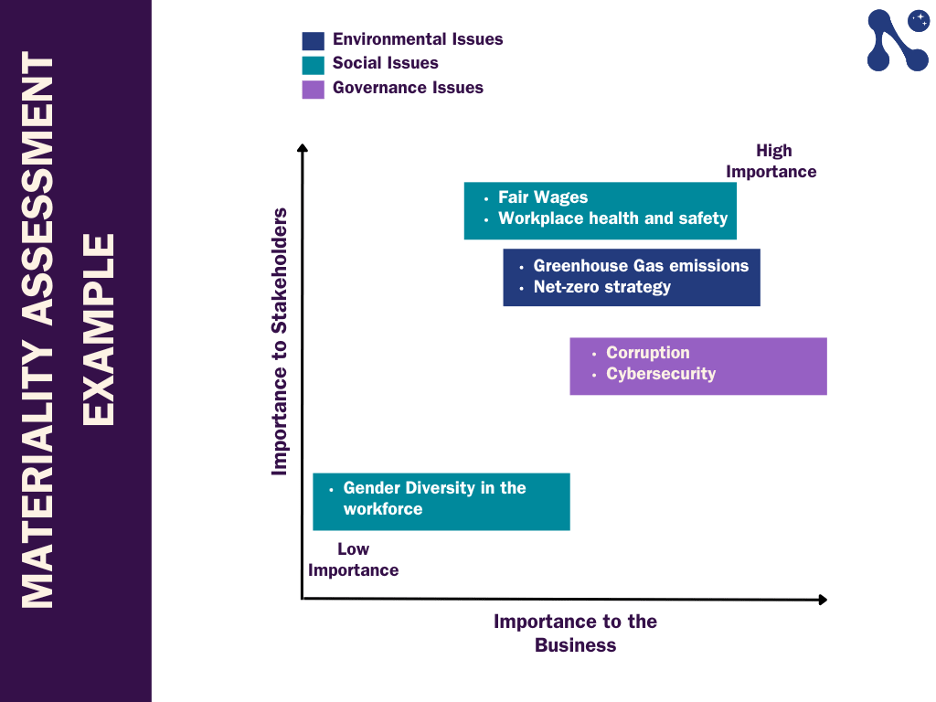
Documentation and Publication: The Uncomfortable Parts
Write the methodology section with enough detail that a competitor could replicate your process. This sounds counter-intuitive, but it is the strongest defense against credibility challenges. When someone questions your results, you can point to transparent methods rather than vague authority. The methodology should cover stakeholder selection criteria, scoring scale definitions, weight justification, and validation procedures. Include the limitations section honestly. Materiality assessments are snapshots in time, not permanent truths. Stakeholder perceptions shift. Regulatory landscapes change. New risks emerge. State these constraints explicitly. A Materiality Assessment Example that acknowledges its own limitations carries more weight than one that pretends to be comprehensive. Plan for periodic updates. Most assessments become obsolete within eighteen to twenty-four months without revision. Build the update cycle into your governance process from the start. Don't treat it as an optional add-on. Schedule it alongside your annual reporting calendar with defined resource allocation.
When This Approach Fails: Being Honest About Boundaries
Materiality assessments do not work well in organizations with severely fragmented decision-making. If there is no clear authority to resolve scoring disputes, the process stalls. I have seen assessments dragged out for six months because no single stakeholder group had the mandate to make final calls. In these situations, recommend a different approach: engage external facilitation or simplify the scope to focus only on the most uncontroversial topics. The method also struggles when stakeholder access is genuinely limited. Remote operations, classified supply chains, or politically sensitive contexts can prevent meaningful consultation. Do not pretend to have done a thorough assessment if you could not reach the people who matter. Document the access constraints and their implications for result reliability. Finally, recognize that materiality assessments are interpretive exercises, not scientific measurements. The numbers you produce are not facts. They are structured opinions backed by documented reasoning. Treat them accordingly. This honesty usually serves you better than false precision in the long run.
Practical Resources for Your Materiality Assessment Example
The GRI Standards website provides free access to all current reporting standards, including the materiality guidance document (GRI 1). The SASB Standards Initiative offers industry-specific materiality maps that can serve as useful starting points, though they should not replace your own analysis. The EU's ESRS standards provide detailed materiality assessment requirements for companies subject to CSRD reporting obligations. For a straightforward Materiality Assessment Example template, I recommend starting with the AA1000APS materiality principle standard, which provides a clear framework for identifying, prioritizing, and responding to material topics. It is freely available and has been tested across thousands of organizations worldwide. Adapt it to your context rather than adopting it wholesale. Download links for these resources are straightforward to find through the respective organization websites. GRI offers free downloads of all standards. SASB materials are available through the IFRS Foundation portal. AA1000APS can be purchased from the AccountAbility website or accessed through institutional subscriptions.

The real value is not in the templates but in the disciplined application. A poorly executed standard produces worse results than a tailored approach built from first principles. Use the frameworks as starting points, not as substitutes for thinking. Build your assessment process iteratively. Start simple, validate against reality, refine the methodology, then expand scope. This usually produces more reliable results than attempting comprehensive coverage in a single pass. The best assessments I have seen were the ones that admitted their own incompleteness and planned for continuous improvement. Your organization will develop its own way of handling these processes over time. The methodologies described here are starting points, not destinations. Track what works, document what fails, and adjust accordingly. The assessment itself is less important than the organizational learning it generates.
The Bottom Line on Materiality Assessment Example Execution
Run the definitional phase separately from scoring. Spend the time getting criteria agreement before assigning numbers. Cross-reference workshop outputs against operational data. Document limitations explicitly. Plan for periodic revision. These steps are not glamorous, but they produce assessments that survive scrutiny rather than collapsing under it. The process usually takes six to eight weeks for a mid-size company with moderate operational complexity. Smaller organizations can compress this to three to four weeks with focused stakeholder engagement. Larger multinationals typically need ten to twelve weeks to cover the scope adequately. Adjust timelines based on your actual constraints rather than borrowing someone else's schedule. Expect revision cycles. The first draft of any materiality assessment will have gaps. Plan for at least one round of internal review and one round of stakeholder feedback before finalizing. This usually adds about two weeks to the timeline but significantly improves result quality and organizational buy-in.
The assessment is a tool, not an endpoint. Use it to guide resource allocation, reporting focus, and risk management priorities. Do not treat publication as the finish line. The real work begins after the document is released, when you act on the materiality findings rather than simply documenting them.