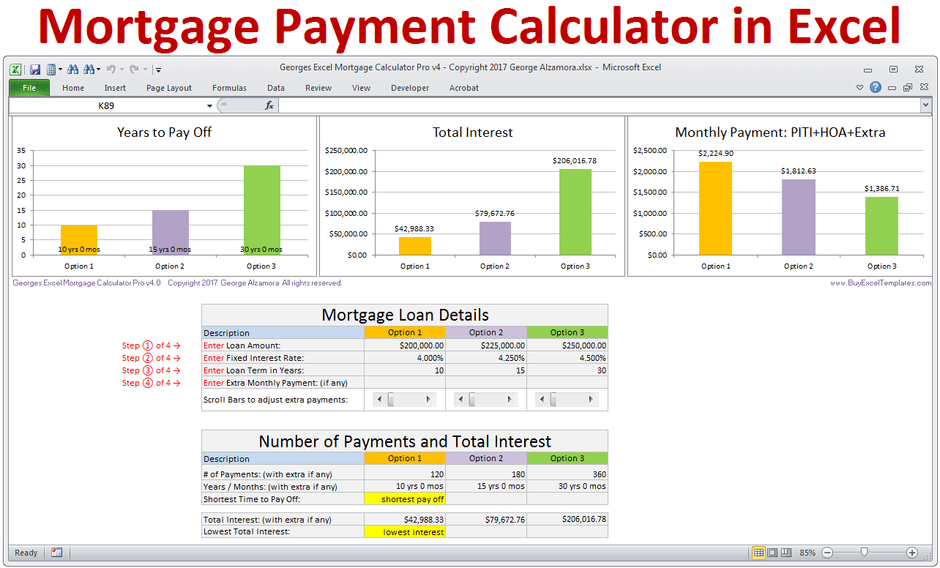
Building a Mortgage Loan Calculator in Excel Without Losing Your Mind
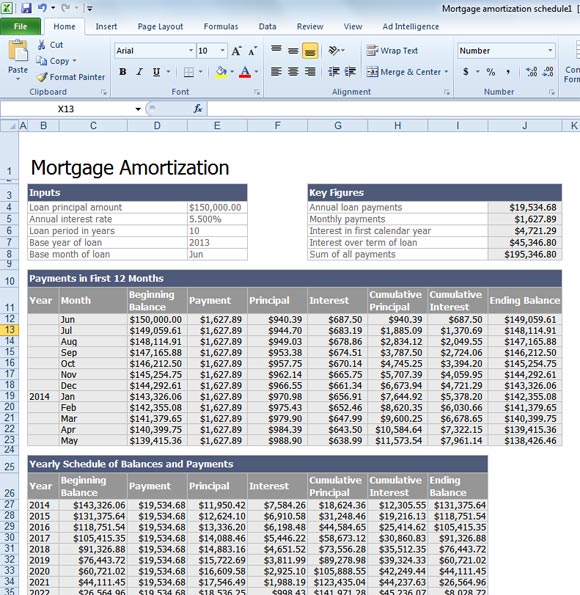
Most people download a mortgage calculator template and immediately run into problems they didn't expect. The monthly payment comes out wrong, the amortization schedule breaks after year three, and scrolling back up to check an earlier payment turns into a search party. I built about a dozen of these across the years for clients, and the ones that survive actual use share a few structural habits that most free templates skip entirely. A working template needs five input cells and three output sections. The inputs are loan amount, annual interest rate, loan term in years, start date, and payment frequency. Everything else derives from those. The outputs are the monthly payment, the full amortization schedule, and a summary showing total interest paid over the life of the loan. That's it. Anything beyond that is decoration that invites breakage. The payment formula uses Excel's PMT function. It looks like this: =PMT(rate/12, nper*12, -loan_amount). The negative sign on the loan amount flips the result so the payment displays as a positive number. Without it, every cell below it shows a negative value and you spend twenty minutes wondering if you entered something wrong. I learned that one the hard way on a template for a client in 2019. They told me the calculator was "giving negative payments" and sent me a screenshot. One negative sign was the entire problem.
The Amortization Schedule
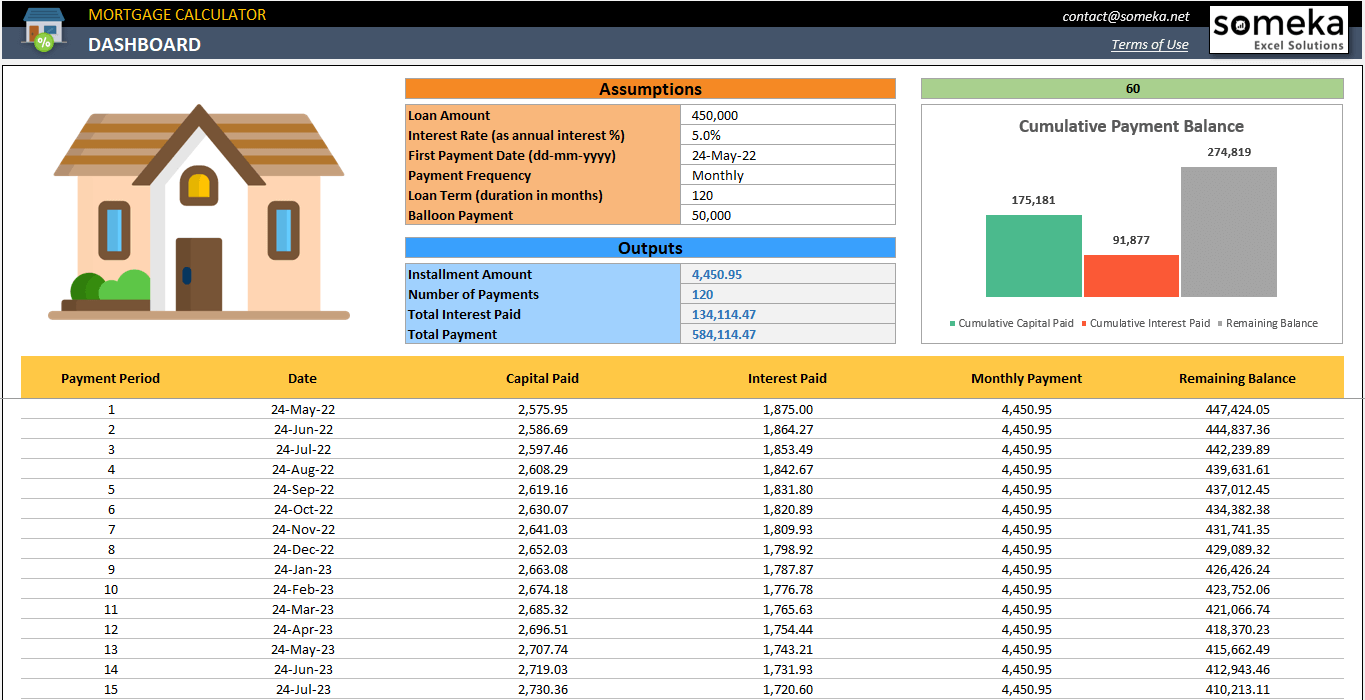
This is where most templates fail. The schedule needs to calculate the remaining balance after each payment, not just list payments. Each row should show the payment number, the date, the total payment amount, the principal portion, the interest portion, and the remaining balance. The interest portion for any given period is =Remaining_Balance_Previous_Period * (rate/12). The principal portion is =Payment - Interest_Portions. The new remaining balance is =Previous_Balance - Principal_Portions. Set up the first row manually with the loan amount as the starting balance. Then copy the formula down. Excel handles the rest. For a 30-year loan at 6.5 percent on a $350,000 balance, the first payment splits roughly $1,891 into $1,891.67, with about $316.67 going to principal and $1,575 to interest. By payment 180, that principal portion has grown to roughly $938. By payment 360, you're pushing nearly the entire payment toward principal. That's how compound interest works in reverse over time.
Common Pitfalls That Will Waste Your Afternoon
One issue that comes up constantly is rounding. If you round the monthly payment to the nearest cent and then build the amortization schedule on unrounded values, the final payment won't clear the balance. You'll have a remaining balance of a few cents after the last payment. Fix this by calculating the schedule on full precision and rounding only the displayed values. In Excel, set the cell format to two decimal places without actually rounding the underlying value. The last payment will then adjust naturally to zero out the loan. Another thing: loan start dates matter more than people think. If your template assumes payments start on the first of the month but the actual loan closes on the 15th, the first payment is a partial period. Some calculators ignore this and show the first full payment two months out. That's wrong. The first payment should reflect the actual days between closing and the first due date. I had a client who used a template that defaulted the first payment to exactly one month after closing. It created a scheduling conflict with their payroll cycle and threw off their cash flow model by about $200 a month. Not catastrophic, but noticeable.
Get the Full Details
Building It Step by Step
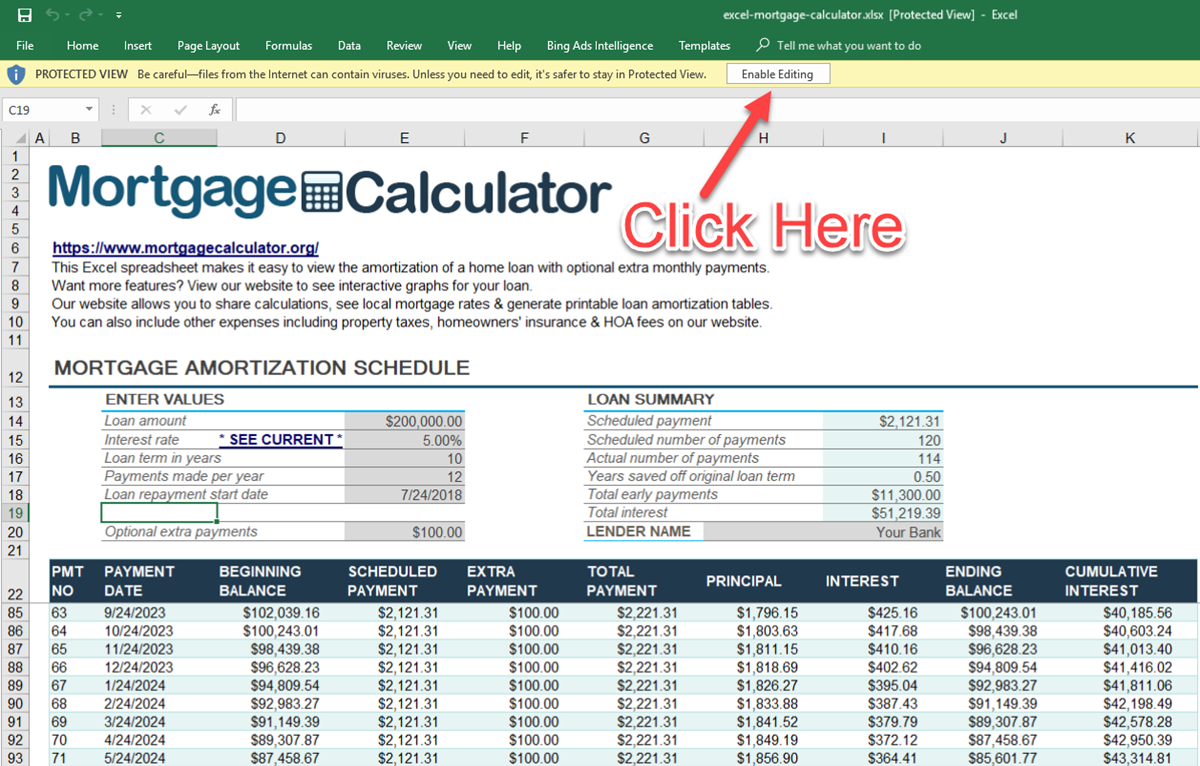
Open a blank workbook. In cell B1, label it "Loan Amount" and put the value in C1. In B2, "Annual Interest Rate" with the decimal value in C2. In B3, "Loan Term (Years)" and the number in C3. In B4, "Loan Start Date" and the date in C4. In B5, "Payment Frequency" with "Monthly" in C5. In C7, enter the PMT formula: =PMT(C2/12, C3*12, -C1). Format this cell as currency. In C8, label it "Total Interest" and use the formula: =C7*C3*12-C1. This subtracts the original principal from total payments to get total interest cost. For the amortization schedule, set up column headers in row 11: Payment Number, Date, Payment, Principal, Interest, Remaining Balance. In D12, enter the start date from C4. In E12, enter =C7. In F12, enter =C1*C2/12 for the first interest portion. In G12, enter =E12-F12 for principal. In H12, enter =C1-G12 for the remaining balance.
For row 13 and below, the payment number is =Previous_Number+1. The date is =Previous_Date+30 (or use EDATE for calendar months). The payment stays the same. The interest is =Previous_Remaining_Balance*C2/12. The principal is =Payment-Interest. The remaining balance is =Previous_Balance-Principal. Copy these formulas down 360 rows for a 30-year loan.
Edge Cases That Break Simple Templates
Fixed-rate mortgages are straightforward. Adjustable-rate mortgages are not. If your template needs to handle an ARM, you'll need a section for rate adjustment periods, caps, and index margins. A standard PMT formula won't work across adjustment periods because the payment changes. You'd need to recalculate the remaining balance at each adjustment and rebuild the payment. Most free templates don't do this. They assume a single rate for the entire term. Another edge case: points and closing costs. If the borrower pays discount points, the loan amount in the PMT formula should reflect the actual amount financed, not the purchase price. A $400,000 home with a 20 percent down payment and two points means the loan amount is $320,000 but the amount financed is $313,600 after points. The payment should be calculated on $313,600, not $320,000. I've seen templates use the wrong base figure and overstate the monthly payment by about $25. Over 30 years, that's a meaningful difference.
When to Use Something Other Than Excel
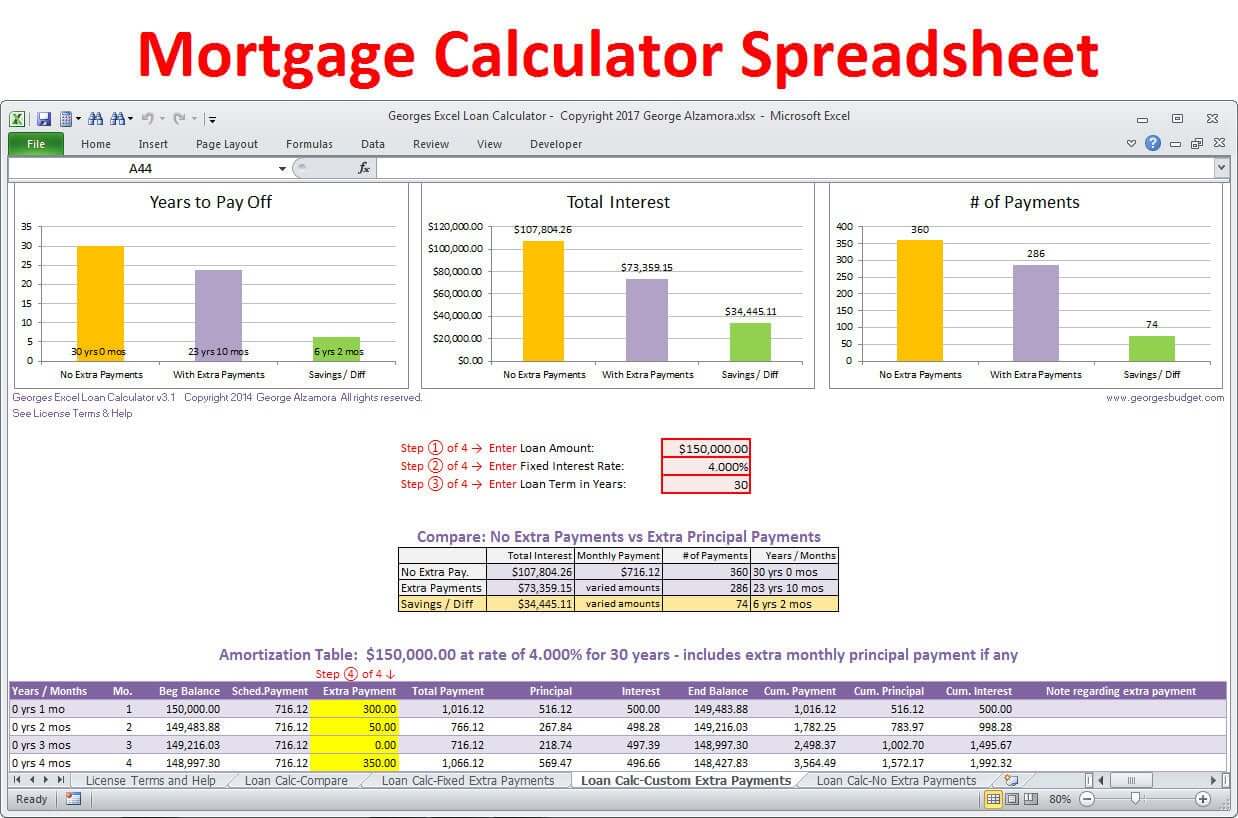
If you're evaluating multiple loan scenarios side by side, Excel works fine. If you need to model early paydowns, extra principal payments, or biweekly payment schedules, the template gets messy fast. The formulas multiply and the cells break. In those cases, a dedicated mortgage calculator tool or a simple Python script handles the iteration more cleanly. I switched a few clients to a lightweight script when their needs grew beyond basic amortization. It took me about 45 minutes to write, and it saved them hours of manual recalculation over the following months. The Mortgage Loan Calculator Excel Template remains useful for quick estimates and basic comparisons. Just be aware of where it falls short. Round your displayed values but not your calculations. Watch the first payment date. And if someone sends you a broken template at 4 PM on a Friday, check the negative signs first.