Building a Mortgage Calculator That Actually Works
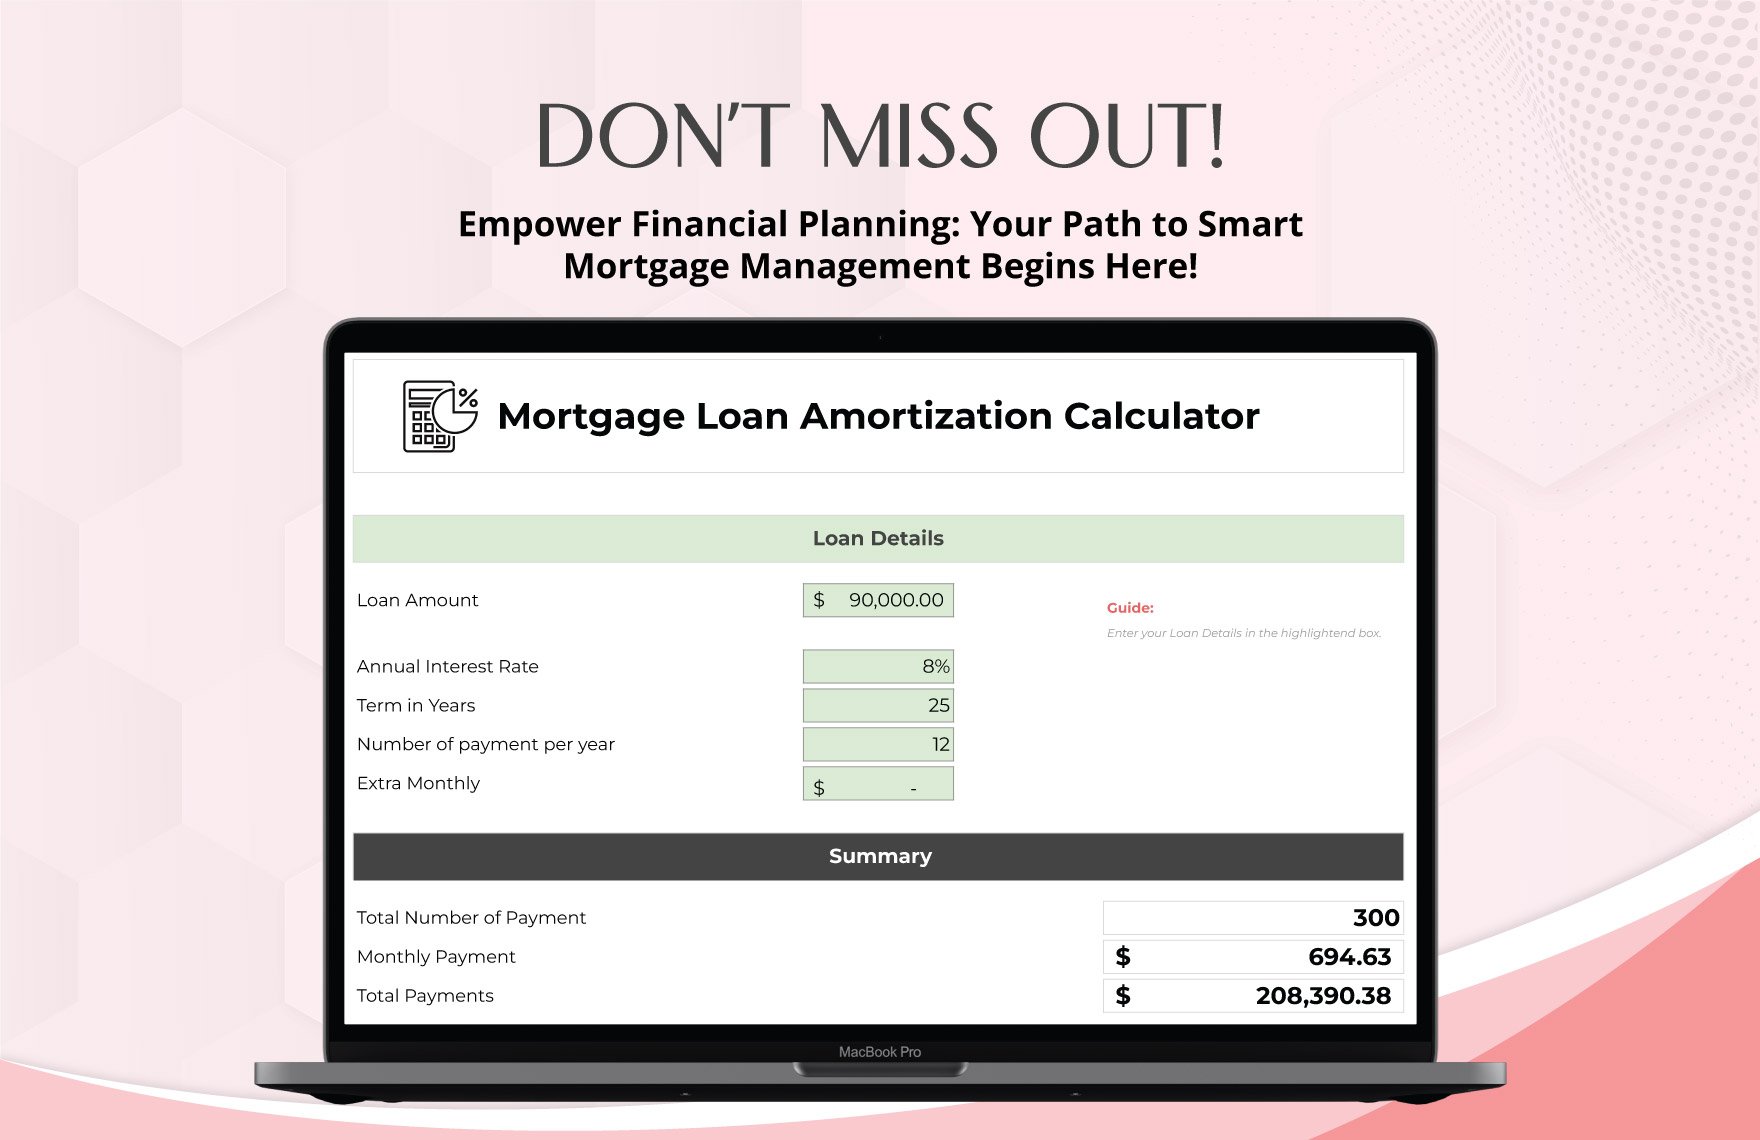
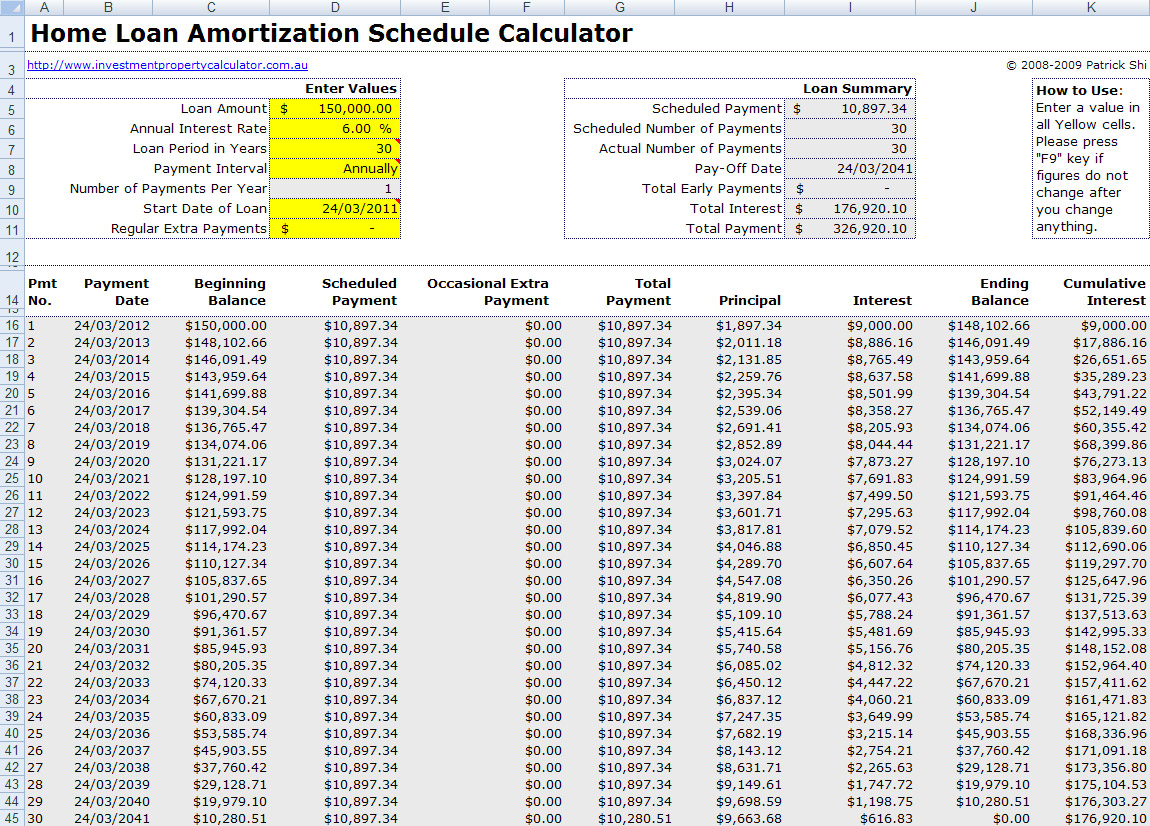
The basic amortization formula is standard, but building something useful requires understanding where people get tripped up. Most online calculators give you a number. They don't explain what that number means or when it becomes irrelevant. At its core, the monthly payment calculation uses the standard annuity formula. You divide the annual rate by twelve, multiply the loan amount by that monthly rate, then divide by one minus the discount factor. The result is your fixed payment. What changes every month is how that payment splits between interest and principal. In the first month of a typical 30-year loan at six percent, about two-thirds of your payment goes toward interest. By month eighteen hundred, that flips. Around the midpoint, you've paid roughly 60 to 65 percent of your total interest over the life of the loan. The last half of the loan term accounts for less than half the total interest cost. That's the shape of amortization, and it's counter-intuitive to most people who think they're building equity evenly over time.
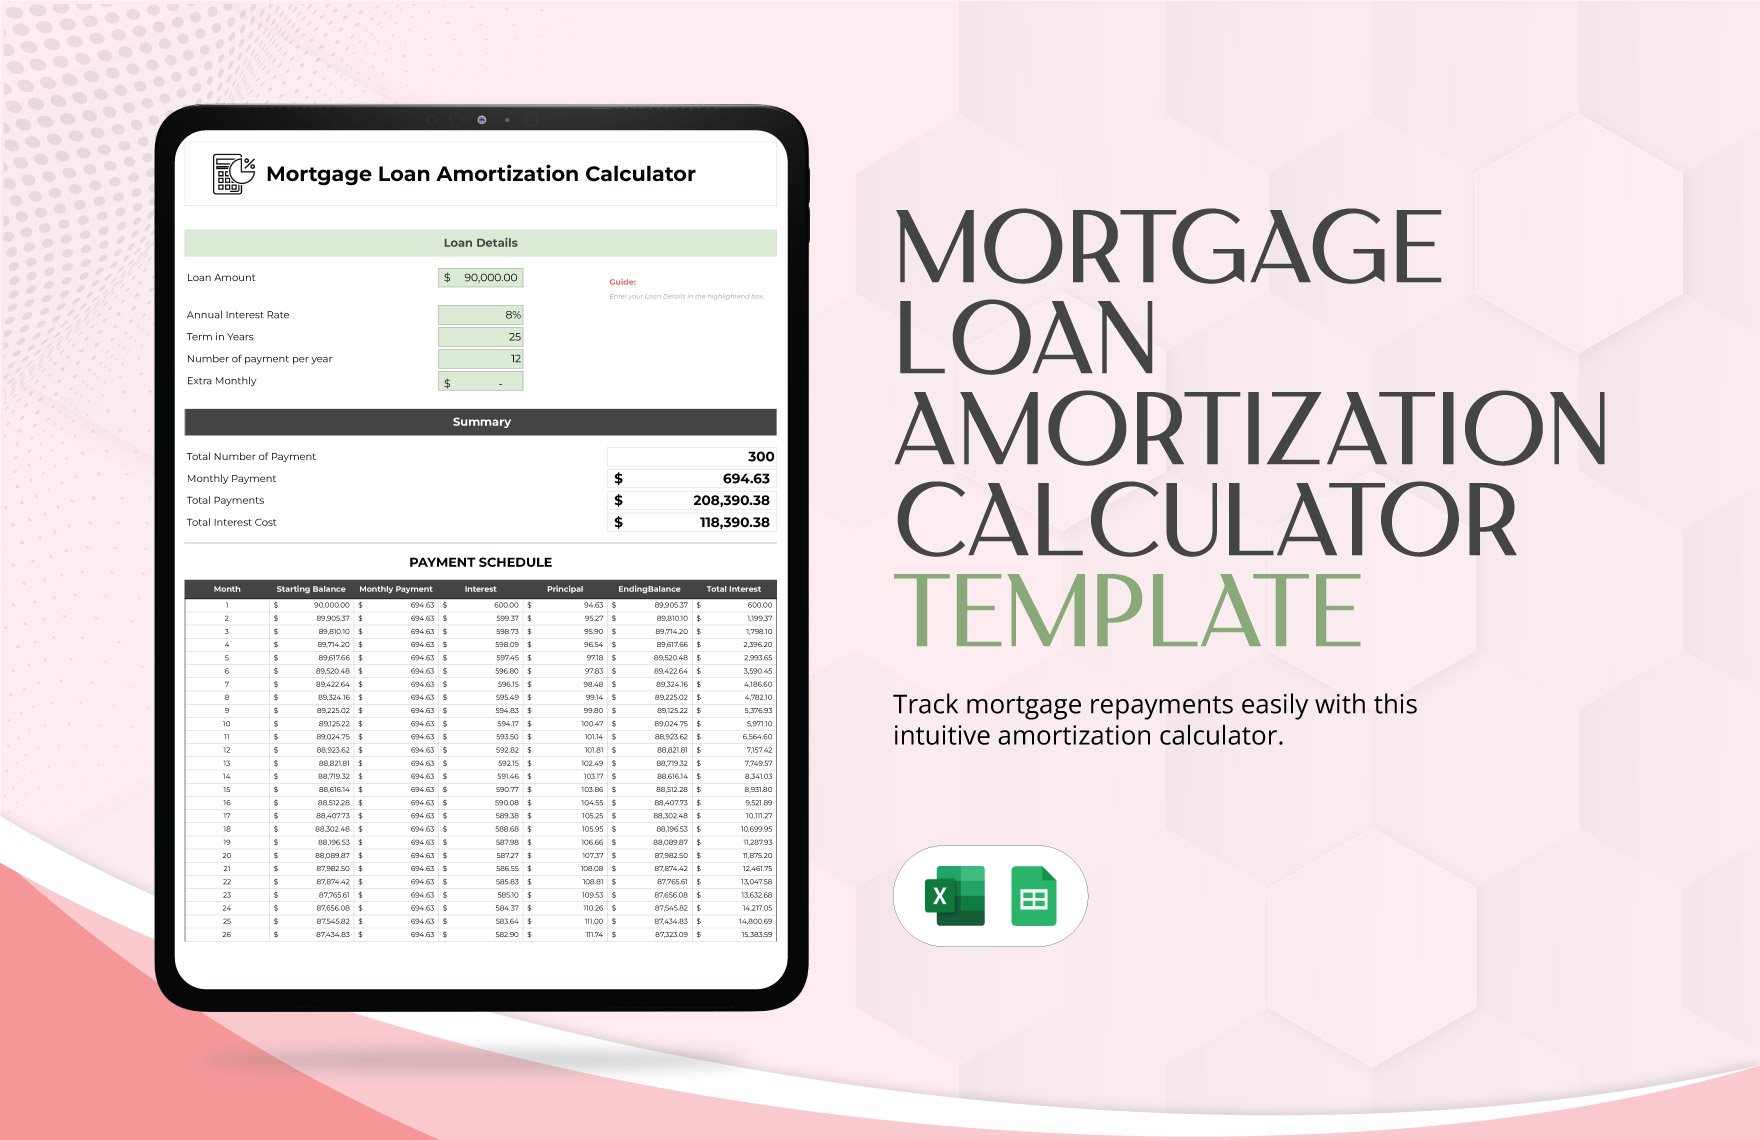
I built my own calculator because existing tools were missing pieces. Most show the payment but don't handle the messy reality of how prepayments actually interact with the schedule. Here's the practical method: Start with the principal balance. Multiply it by the monthly interest rate to get that month's interest charge. Subtract the interest from your payment to find the principal portion. Reduce the balance. Repeat until the balance hits zero. The Excel formula for the payment itself is PMT(rate, nper, pv), which returns a negative number you just flip to positive for display. It's straightforward once you stop treating it like black box magic.
The Problem I Ran Into: Biweekly Payments and the Recalculation Trap
A few years back I was helping a friend who wanted to switch to biweekly payments on a $320,000 loan. He thought he'd save years by paying half every two weeks. The calculator showed a clean schedule. What it didn't show was what happened when he made an extra lump sum payment of $10,000 mid-year. The balance dropped, but the payment stayed the same, and the recalculated payoff date shifted by almost two years. Standard amortization tables don't account for this without rebuilding the entire schedule from that point forward. My workaround was simple but necessary: when a prepayment occurs, I recalculate the remaining payment amount based on the new balance and the original loan term, then generate a fresh schedule. This is what most free online tools don't do. They just show a reduced number of periods without adjusting the monthly payment, which gives misleading results.
Get the Full Details

What Most Calculators Get Wrong
The biggest issue I see is that they ignore tax implications entirely. The interest deduction on a mortgage isn't linear. In the early years you're deducting the most, which matters significantly for people in higher tax brackets. A $400,000 loan at six percent generates about $24,000 in interest in year one. At a 24 percent marginal tax rate, that's roughly $5,760 in tax savings. By year fifteen, the interest portion has dropped to maybe $14,000. The same loan structure, completely different tax impact. A proper calculator should show this distribution because it affects the real cost of borrowing. Another thing people miss: PMI and how it disappears. On a conventional loan with less than twenty percent down, private mortgage insurance adds to your monthly payment until you reach 20 percent equity. Some calculators factor this in, most don't. If your loan amount is $350,000 and you put five percent down, you're paying PMI on $332,500 until the balance drops below $280,000. That could be three to five years depending on your payment pace. I built a toggle into my version specifically for this because it's the single biggest source of confusion I see in comments and forum posts.
Edge Case: The Balloon Payment Scenario
I worked with a client who had a five-year balloon mortgage. The amortization schedule looked normal for 30 years, but the loan matured after sixty payments. The remaining balance at that point was still substantial—maybe 85 percent of the original principal depending on rates and timing. A standard calculator would show you a 30-year payoff that never actually happens. The correct approach is to calculate the remaining balance at the balloon date, which is the present value of all remaining payments, then treat that as a new loan if you refinance. The formula for the remaining balance after n payments is: B = P × [(1 - (1+r)^(n-N)) / r], where P is the payment, r is the monthly rate, n is payments made, and N is total payments. I use this whenever someone asks about selling before the loan matures or refinancing mid-term.
Common Pitfall: Adjustable Rates and the Initial Teaser Period
Most calculators assume a fixed rate throughout. ARMs complicate this. The initial adjustment period might be six months, a year, or two years with a teaser rate. After that, the rate resets based on an index plus a margin. A proper amortization schedule for an ARM needs to recalculate the payment at each adjustment date. What I do is project the payment changes year by year rather than trying to build a single static table. It's less pretty but far more accurate. Here's a practical tip that saves headaches: when an ARM adjusts upward, the payment increase can sometimes exceed what the borrower qualifies for under debt-to-income ratios. A calculator that only shows the new payment without flagging qualification issues is incomplete. I added a simple check that compares the adjusted payment against a standard 43 percent DTI threshold and flags it if exceeded.
A Note on What This Can't Do
No calculator accounts for every variable. Property taxes, homeowners insurance, HOA fees, and special assessments all factor into your true monthly housing cost but aren't part of the mortgage amortization. Some calculators include them as escrow estimates, but those are guesses. I separate the mortgage from the housing expense entirely because mixing them creates false precision. Another limitation: these tools assume you never miss a payment. If you're three months behind, the amortization schedule becomes theoretical. Late fees, penalty interest, and potential default change everything. A calculator isn't a financial advisor. It shows the mathematical ideal, not the messy reality of financial distress. If you're dealing with negative amortization loans or option ARMs, forget the standard formula. Those products are designed to confuse even experienced lenders. My recommendation there is to pull the actual loan documents and work from the disclosed payment schedule, not any generic calculator.
The tool I built handles standard fixed and adjustable rate mortgages, includes prepayment scenarios, flags PMI removal dates, and recalculates at adjustment points. It's not fancy, but it answers the questions I kept seeing people struggle with on forums. The spreadsheet is available if you need it, but understanding the mechanics matters more than having a pre-made file. Numbers shift when life does, and the calculator won't adjust for your situation unless you understand what it's actually calculating.