So You're Figuring Out Motorcycle Payment
Most people look at the monthly number and stop there. That is a mistake that costs thousands. Motorcycle Payment is only one piece of the actual cost of owning the bike, and it hides several things from you if you are not paying attention. Let me walk you through how this works in practice, not from a textbook. A motorcycle payment is your monthly principal and interest obligation on a motorcycle loan. The formula lenders use is straightforward, but the inputs matter a lot more than you might think. The payment comes out to something close to P times r times (1 plus r) to the n power, divided by (1 plus r) to the n power minus 1, where P is the financed amount, r is your monthly interest rate, and n is the number of months. I know that sounds like homework, but the reason I am writing it out is because most riders skip this part and just type a number into a calculator without understanding what shifts the result. If you put 20 percent down on a nine thousand dollar bike and finance the rest at 7.5 percent annual rate over sixty months, your payment lands around one hundred eighty-eight dollars. Change the term to forty-eight months and it jumps to about two hundred thirty-nine dollars. Same bike, same rate, different monthly number. The total interest paid over forty-eight months is roughly eight hundred eighty dollars compared to over fifteen hundred over sixty months. You save money by paying less time, but the monthly burden is higher. That tradeoff is the first thing you need to be honest about with yourself.
I had a rider once who was so focused on keeping the payment under two hundred dollars that he stretched the loan to seventy-two months. He did not realize the interest rate on that term was two points higher than the forty-eight month option. He ended up paying more in interest over the life of the loan than he would have with the shorter term, even though his monthly payment was lower. That is a pretty common trap with motorcycle financing.
The Parts of the Payment That Get Hidden
Your actual monthly obligation is not just principal and interest. Lenders frequently roll in property tax estimates, insurance escrow, and sometimes GAP coverage into what they call the payment. If you are looking at a number from a dealer, ask whether it includes those extras. A payment of two hundred and fifteen dollars that includes three hundred dollars in insurance escrow is not the same as a payment of two hundred and fifteen dollars that is pure finance. One of those will surprise you when the insurance bill actually comes due. Another thing most people miss is the difference between the advertised payment and the actual check they write. Some lenders use a method called accelerated repayment scheduling, where every payment after the first gets applied faster to principal because of how the billing cycle is set up. It saves you a small amount over the life of the loan, but it can make your first payment slightly larger than the quoted figure. I learned this the hard way when a quote came in at two hundred twelve dollars and my first statement showed one hundred eighty-nine dollars because I had made a partial payment during the billing window. It did not matter much in the end, but it looked wrong on paper. If you are calculating this on your own before walking into a dealership, use a simple spreadsheet or a decent calculator and include the tax and title fees in the financed amount. Those are not optional. In most states they get added to the loan balance if you do not pay them upfront, and they increase your interest cost. A thousand dollar tax and title spread over sixty months at seven percent adds roughly eighteen dollars to your monthly payment and over a hundred ten dollars in total interest. It does not sound like much until you are paying it every month for five years.
Get the Full Details
How to Calculate Your Real Motorcycle Payment
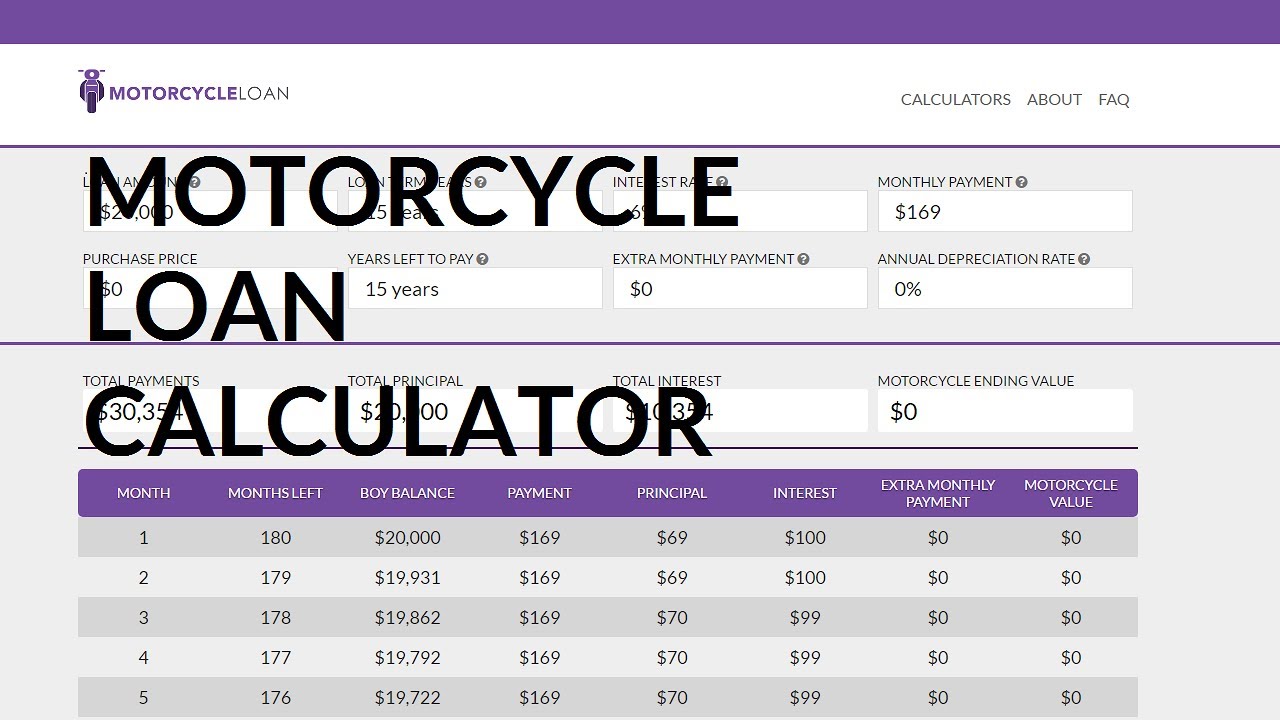
Here is the practical version of what I do when a rider asks me to help them figure this out. First, get the out-the-door price, not the sticker price. Negotiate the bike price, then add tax, title, registration, and any dealer fees. That is your total cost. Subtract your down payment. That remaining number is your principal. Next, decide how many months you are comfortable paying. Shorter terms mean higher payments but significantly less interest. After that, shop for the rate. Credit unions almost always beat dealer financing on motorcycles, and the difference is usually one to three percentage points depending on your credit profile. I worked with a guy last year who had an eighty-two credit score and walked into a dealership expecting the best rate they could offer. They gave him eight point nine percent. He took the deal because he was tired of being there. A week later he went to his credit union and refinanced at four point two percent. His payment dropped by about thirty-five dollars a month on the same loan. He did not change the bike, the term, or the down payment. He just used a different lender. That is the single biggest variable you can control, and most people do not even think about it. If you want to run the numbers yourself, you can find free calculators at places like NerdWallet or Bankrate. They are accurate enough for this purpose. Enter the exact principal, not an estimate. Round numbers make the math easier but they also make your estimate less useful. If your principal is eight thousand two hundred and forty dollars, type that in. The difference between using the exact number and a rounded number is negligible for the monthly payment but it tells you that you care about the details, which is exactly the mindset you need going into a financing discussion.
When the Numbers Stop Working for You
Motorcycle payment is not a perfect tool for every situation. It breaks down in a few specific cases. If you have bad credit and are looking at subprime rates above twelve percent, the monthly number can become absurdly high relative to the remaining principal. On a six thousand dollar loan at fourteen percent over sixty months, you pay over a thousand dollars in interest alone. The payment is around one hundred forty-six dollars, but the total cost of the bike is closer to seven thousand. That is worth understanding before you sign anything. Balloon payment loans are another area where the stated monthly number is misleading. These loans have low monthly payments because a large chunk of the principal is deferred to the end. You might see a payment of ninety dollars a month on a seven thousand dollar bike, but at the end of the term you owe three thousand dollars in a single lump sum. If you are not prepared for that balloon, you either refinance at a worse rate or sell the bike under pressure. I have seen this bite people who thought they were getting a deal. Prepayment penalties are rare on motorcycle loans but they exist, and they matter. Some lenders charge a fee if you pay off the loan early or refinance within the first twenty-four months. It can be structured as a percentage of the remaining balance or as a set number of months of interest. Always read the disclosure documents before signing. The monthly payment will look great, but a two percent prepayment penalty on a five thousand dollar remaining balance is a hundred dollars you did not budget for.
There is also the issue of negative equity from a trade-in. If you owe more on your current bike than it is worth, the dealer can roll that negative equity into your new loan. You end up financing more than the bike is worth, which means your payment is higher and you are underwater from day one. This is one of the fastest ways to get into a situation where selling the bike later does not cover what you owe. If you have negative equity, be honest about it and factor it into your monthly calculation before you commit. Do not let the dealer hide it in the paperwork. The bottom line is that Motorcycle Payment is a useful number to track, but it is not the whole story. Look at the total cost, compare rates from multiple lenders, avoid balloon structures unless you have a clear exit plan, and never sign without reading the fine print on prepayment penalties and escrow. A well-calculated payment protects you. A payment you accept without understanding protects nobody.