Why Your Spreadsheets Lie to You
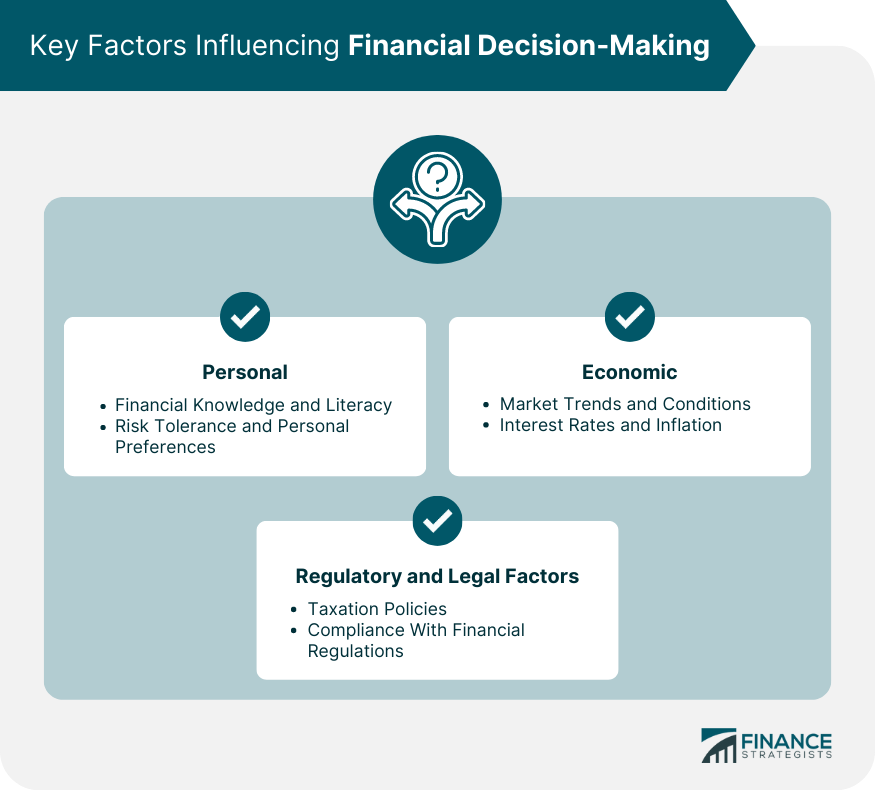
I spent six years building financial models for a mid-market private equity firm before walking away. Not because the math was hard, but because the people using it kept pretending the numbers meant something they didn't. The truth is Of Financial Decision Making has very little to do with formulas and everything to do with knowing which inputs you are willing to bet your career on. Financial decision making is really just three things: forecasting cash flows, assigning a cost of capital, and discounting. That is it. Everything else is decoration. A DCF model is still a DCF model whether you build it in Excel or Python. What separates good decisions from expensive mistakes is not the tool, it is the assumptions sitting at the top of the spreadsheet. I have seen senior analysts spend two weeks refining a terminal value assumption that ends up moving the enterprise value by less than four percent. Meanwhile the revenue growth rate, which actually determines whether the deal works at all, gets rubber-stamped in five minutes because someone said "let's use consensus estimates." It happens constantly.
How I Actually Build Models
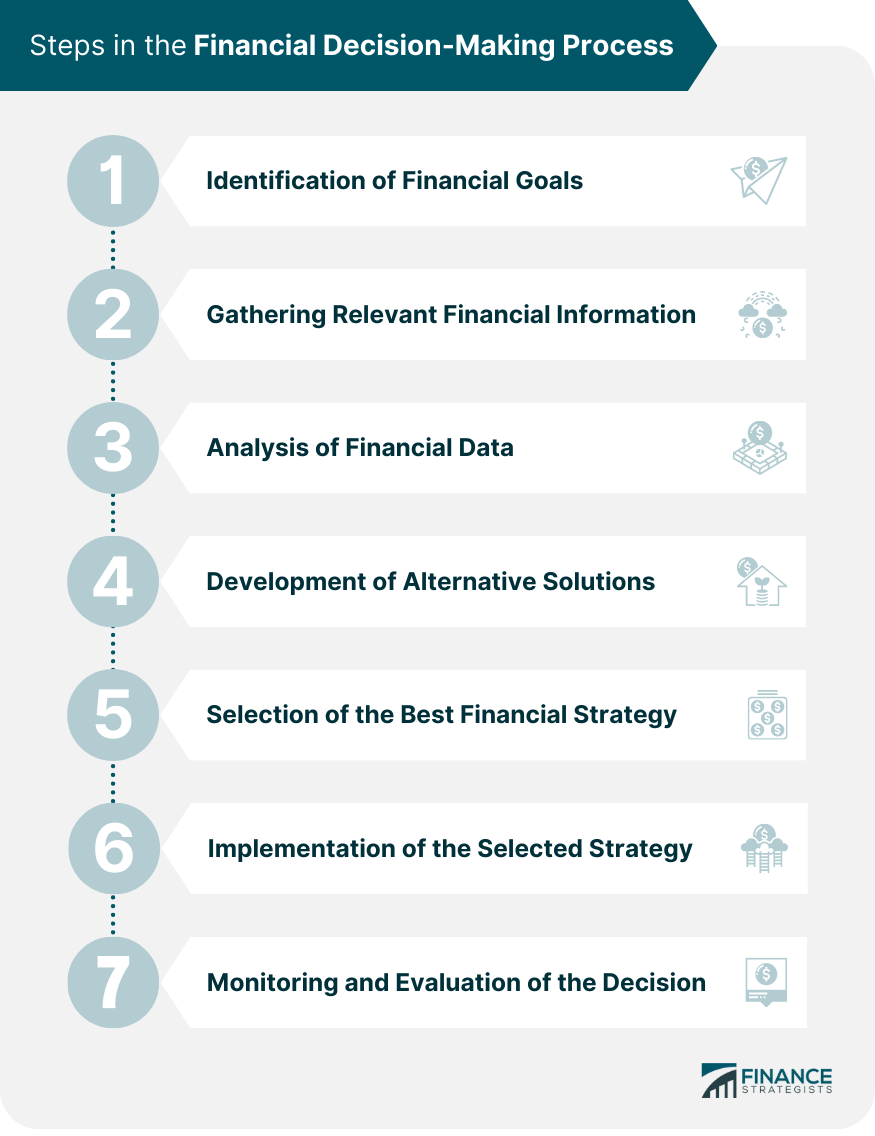
When I start a new model I do not touch the income statement. I begin with working capital drivers, debt schedules, and capital expenditure requirements. Those are the items that strangle companies quietly. Revenue looks sexy on a presentation slide. Liquidity kills them in practice. My process looks like this: Step one: Map every line item on the balance sheet to an operational driver. Days sales outstanding ties to collections policy. Inventory turns tie to supply chain flexibility. If you cannot explain the driver in plain language, do not put it in the model.
Step two: Stress the drivers, not the outputs. Change gross margin by two points instead of changing net income directly. The model should still make sense when you break it. Step three: Run a sensitivity table on the top three assumptions. Usually revenue growth, operating margin, and reinvestment rate. If the valuation swings wildly between those scenarios, you do not have a pricing problem, you have a knowledge problem.
Get the Full Details
A Real Example That Cost Me Sleep
In 2019 I modeled a manufacturing acquisition where the seller claimed thirty percent EBITDA margins based on peak utilization. The number looked fine on paper until I traced their overhead allocation methodology. They were spreading fixed plant costs across variable output, which meant margins collapsed to twelve percent once normalized production levels kicked in. The deal was structurally unprofitable at any reasonable purchase price. The workaround was simple but annoying. I pulled their actual utility bills, property tax assessments, and equipment maintenance logs from the past three years. Those data points revealed the fixed cost floor. Once I rebuilt the margin profile around those numbers instead of their claimed percentages, the internal rate of return dropped from eighteen percent to negative four. We walked away. Two quarters later the seller disclosed a pending equipment lease that would have eaten another six percent of operating income.
Cost of Capital Mistakes
Everyone knows to use the weighted average cost of capital. Very few people actually calculate it correctly. The CAPMbeta you find on Bloomberg is backward-looking and often stale. A more reliable approach for private companies is to take the public comparable beta, unlever it using the peer median capital structure, and relever it using your target debt-to-equity ratio. The size premium argument is also mostly dead. Modern academic literature shows that after controlling for value factors, small-cap risk does not explain excess returns the way people think it does. If you are adding a two percent size premium on top of everything else, you are double counting risk. I stopped doing it around 2016 and have not looked back. For the equity risk premium, use forward-looking estimates rather than historical averages. The historical ERP in the United States sits around five to six percent depending on the sample period, but implied equity premiums from current market prices tend to run higher for emerging markets and lower for mature ones. A static five percent number works for rough screening but destroys precision when you are within a few percentage points of a decision threshold.
Common Pitfalls That Waste Time
Pitfall one: Forgetting taxes on intercompany transactions. If your model includes management fees flowing from subsidiary to parent, those fees create deductible expenses at the subsidiary level and taxable income at the parent. Most quick models skip this and overstate free cash flow by a meaningful amount. Pitfall two: Using ending balance sheet figures instead of averages. Working capital requirements should be based on average balances during the period, not the endpoints. Year-end numbers are frequently distorted by seasonal spikes or window-dressing that has nothing to do with operations. Pitfall three: Assuming perpetual linear growth in terminal value. A growing perpetuity with a five percent growth rate into infinity sounds sophisticated until you remember that no company grows faster than the economy forever. Five percent is roughly nominal GDP growth in developed markets. If your terminal value implies the company will eventually become larger than the sector itself, your model is wrong.

What Actually Moves Deals
In my experience the three assumptions that determine whether a deal passes or dies are working capital intensity, maintenance capital expenditure, and customer concentration. Everyone obsesses over revenue growth because it is easy to change. These three are harder to see but far more damaging when wrong. Maintenance capex alone can erase twenty to thirty percent of free cash flow in asset-heavy businesses. I have seen models project twenty-five percent annual FCF growth for ten years on companies that needed to replace nearly all their equipment just to stay competitive. The reality is maintenance capex usually tracks inflation plus modest capacity additions, not explosive growth. Customer concentration deserves a separate discussion. If a single client represents more than fifteen percent of revenue, the standard DCF breaks down because the probability distribution of outcomes is no longer normal. A lost contract does not cause a small dip, it causes a cliff. I switch to scenario-based modeling for those cases, building explicit downside scenarios rather than relying on standard deviation metrics.
When Models Fail Completely
Financial models cannot handle binary events. A pending lawsuit, a regulatory hearing, or a key person dependency does not discount gracefully. The numbers look fine until the event hits, and then the entire framework is meaningless. Pharmaceutical pipelines are the classic example. A single FDA decision can swing value by an order of magnitude. Standard DCF approaches produce comforting-looking numbers that are completely detached from reality. In those cases I use real options valuation or at minimum run explicit go-no-go branching scenarios with assigned probabilities. Cyclical industries suffer from a different failure mode. Applying a single discount rate across full-cycle earnings smooths over the volatility that defines the business. An auto manufacturer or commodity producer needs cycle-adjusted earnings, not trailing averages. The difference can be twenty or thirty basis points in discount rate alone, which compounds to millions in valuation.
Practical Tools I Use
For quick screening I rely on a simple rule of thumb: if the unlevered free cash flow yield does not exceed the weighted average cost of capital by at least three hundred basis points, stop digging. Most deals that look attractive on revenue multiples fail this test because they ignore the capital intensity required to sustain growth. For deeper analysis I build three models instead of one. The base case uses management assumptions. The downside case strips away all growth and assumes margin compression. The upside case assumes everything goes right but keeps the discount rate conservative. If all three produce positive net present value under realistic assumptions, the deal deserves serious consideration. If only the base case works, walk away. The spreadsheet templates I use are straightforward. Standard five-year projection with monthly detail for the first two years, quarterly thereafter. Annual terminal value calculation. Sensitivity tables on the top three drivers. A bridge chart showing how enterprise value moves between scenarios. Nothing fancy, but it forces discipline that most ad-hoc modeling lacks.
Download and Resources
There is no single authoritative source for Of Financial Decision Making because the field is practitioner-driven rather than academic. The closest thing to a standard reference is the CFA curriculum, specifically the corporate finance and equity valuation sections. Beyond that, industry-specific frameworks vary so much that general templates tend to miss the nuances that actually matter. I keep a collection of working capital normalization worksheets and maintenance capex benchmarks sourced from SEC filings of comparable companies. Those documents are not publicly distributed in a single package, but building your own database from public filings typically takes two to three weeks for a first pass and pays for itself immediately on any deal where margins are contested. The single most useful skill I learned is reading footnotes instead of the income statement. Deferred tax assets, lease obligations, pension funding status, and contingent liabilities all hide in notes. A company reporting strong operating cash flow can be quietly leveraged through operating leases that do not appear on the face of the statements until you dig into the disclosures.
Finally, remember that any financial model is only as good as its weakest assumption. Garbage in still produces garbage out, regardless of how elegant the Excel formatting looks. The models that survive scrutiny are the ones where every input can be defended with primary data rather than inherited convention.