So You Need to Compare Payment Options and Not Go Insane
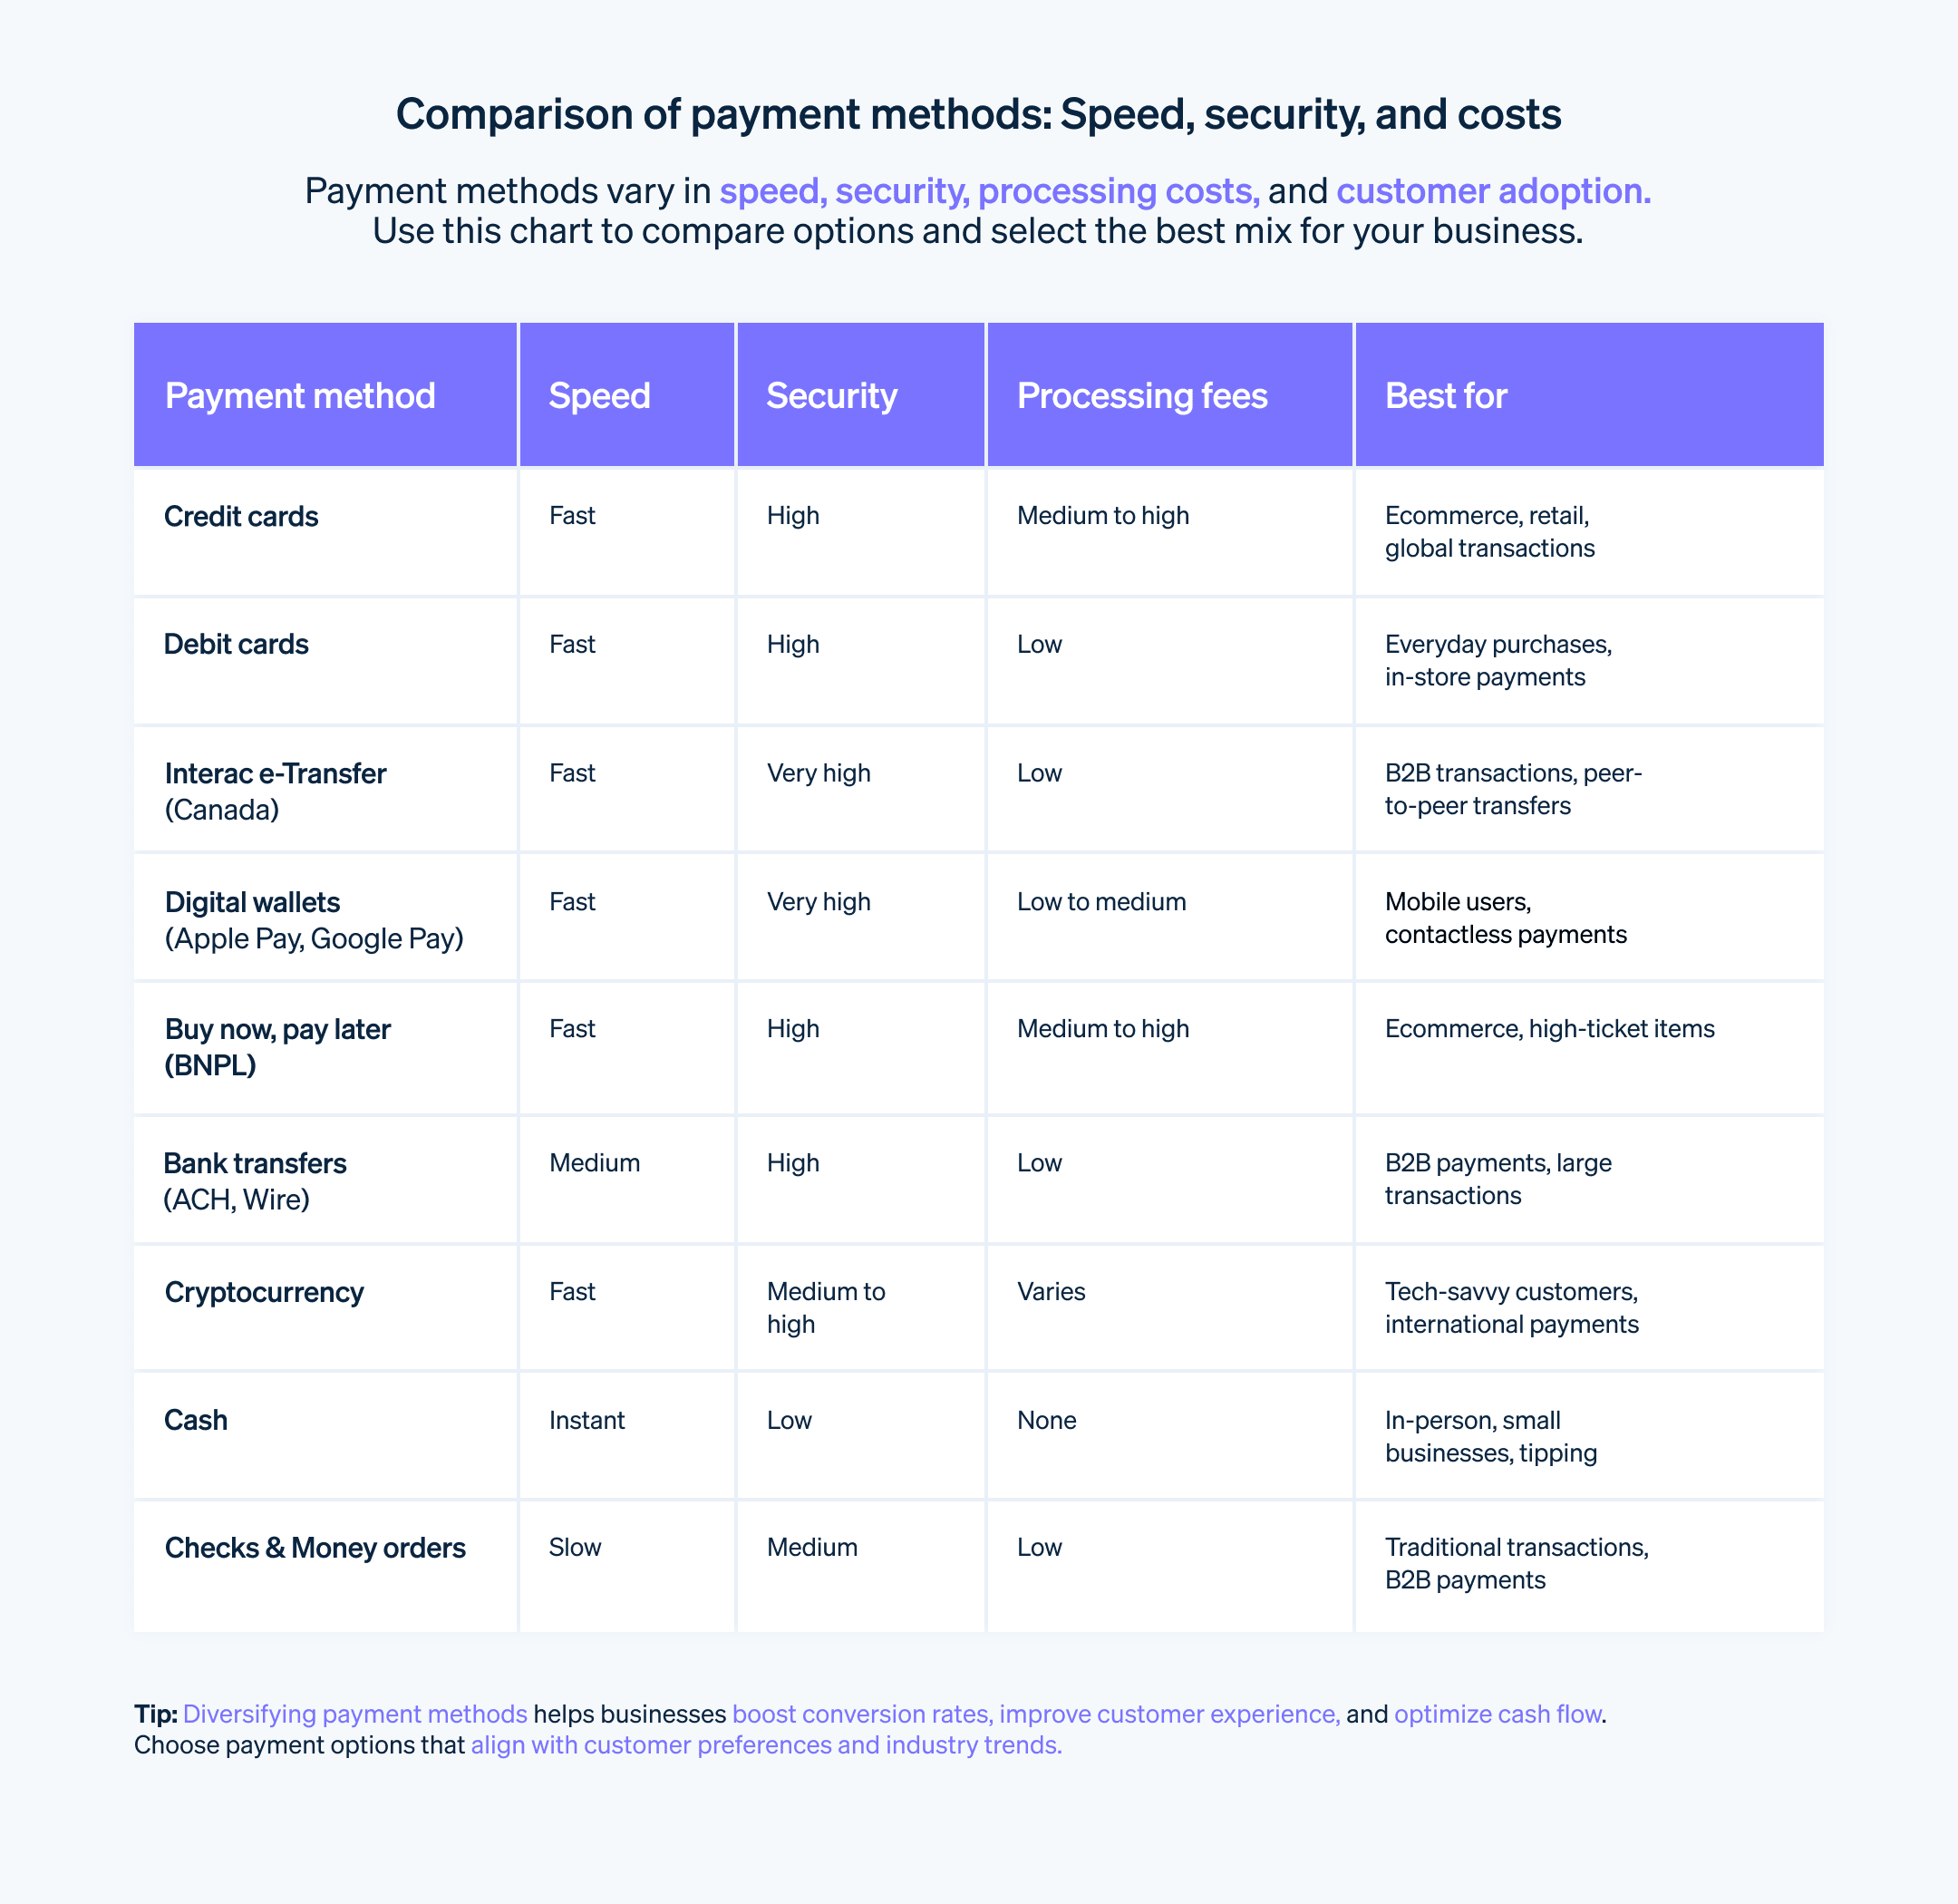
Payment Comparison is the process of evaluating different payment processors, gateways, or methods against each other to figure out which one actually makes sense for your situation. Everyone tries to simplify this into a spreadsheet with checkboxes, but it doesn't work that way in practice. The numbers on a pricing page are only part of the equation, and the part that bites you most. I spent about three weeks comparing providers last year for a client who was stuck on an old gateway with escalating hidden fees. I thought I had it figured out after looking at their published rates. I was wrong. The real cost delta between two supposedly similar processors ended up being roughly 0.4% per transaction once you accounted for chargeback handling, cross-border markups, and settlement timing. That difference adds up to tens of thousands annually depending on volume. The published rate sheets don't show any of that.
Getting Started With Payment Comparison
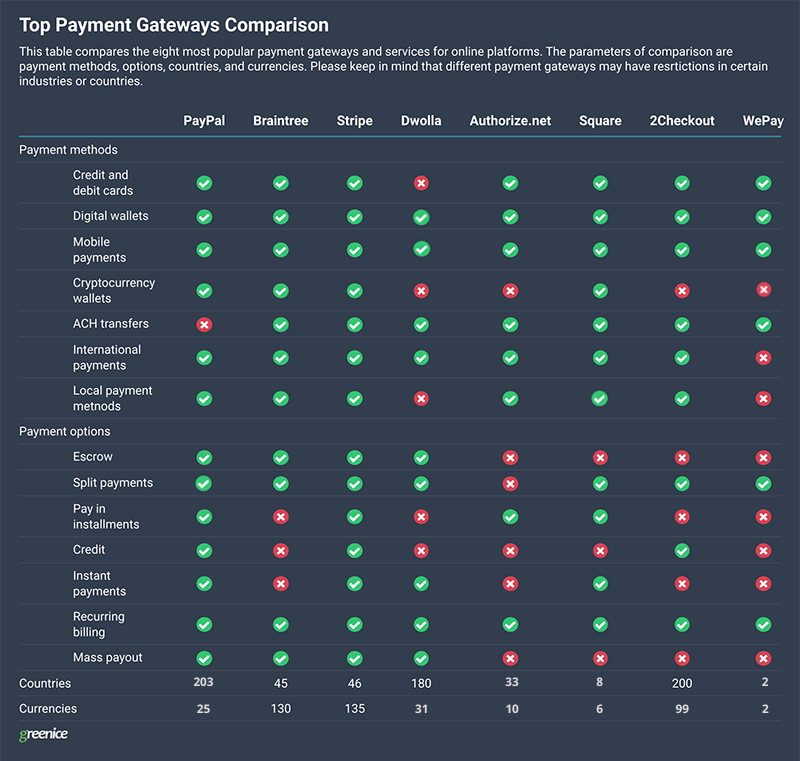
Start by writing down your actual transaction profile. Monthly volume, average ticket size, whether you process international cards, what your chargeback rate has been over the last twelve months, and how much time you can realistically spend on integration. If you're running under five thousand dollars a month in transactions, the whole exercise is probably overkill. Just pick whoever has the simplest dashboard and move on. The nuanced comparison matters when you're past that threshold. Next, pull the full pricing schedules from at least three providers. I recommend Stripe, Square, and one regional processor that specializes in your industry. Stripe's pricing is transparent but favors high-volume businesses with complex integrations. Square looks cheap until you factor in their default 2.9% plus thirty cents on card-not-present transactions. Regional processors sometimes offer flat monthly rates that make more sense if your transaction count is predictable and moderate. The spreadsheet approach falls apart because every provider structures their fees differently. Stripe lists separate rates for domestic versus international cards. Square bundles everything into one rate but charges extra for features you'd expect to be included. Some processors add a monthly gateway fee, others bake it in. You need to normalize everything to a per-transaction cost based on your actual mix of transaction types before you can compare anything fairly.
The Settlement Timing Trap
This is the part nobody mentions. Settlement timing directly affects your cash flow, and a provider that charges slightly more but settles funds next business day instead of two days out might actually be cheaper overall. I learned this the hard way when a client switched from a processor that offered next-day settlement to one that advertised lower rates but held funds for five business days. The lower rate looked great on paper until payroll came due three days into each settlement cycle and they couldn't cover it. Look at the actual settlement schedule for each provider, not just the headline rate. Ask about expedited settlement options and what those cost. Some processors offer instant payout to your bank account for an additional percentage point, which matters if you're running a seasonal business with uneven cash flow. You also need to check what happens during chargebacks. Some processors automatically reserve a percentage of your incoming funds as a rolling reserve if your chargeback rate exceeds certain thresholds. Stripe does this. Others just flag the account and hope you fix it. A provider that doesn't do rolling reserves but charges slightly more per transaction might save you from having forty percent of your monthly revenue locked up for no reason.
Get the Full Details
Integration Realities
The technical side of Payment Comparison matters more than most people account for. I worked with a merchant who chose a processor because of competitive pricing, only to discover six weeks into integration that the API didn't support recurring billing in the way their platform required. They ended up paying a premium to switch providers anyway, losing both the promised savings and two months of development time. Check the documentation before you sign anything. Look for the specific endpoints you'll need, confirm webhook support for payment events, and verify whether the sandbox environment matches production closely enough that your testing will be meaningful. Some providers have sandbox quirks that don't surface until you're processing real money. If you're building a custom integration rather than using a hosted checkout, the quality of the SDK and developer tools will determine whether this integration takes a weekend or a month. Stripe's libraries are genuinely good. Square's are functional but less polished. Regional providers often have documentation that reads like it was written by someone who hasn't talked to a developer in years.
Customer Support Quality
This seems irrelevant until a transaction fails at 2 AM on a Friday and you need someone to answer. I've watched businesses lose money because their processor's support team couldn't resolve a routing issue for four hours during peak shopping time. Check forums and review sites for current support experiences, not the aggregate star rating. Look for specific complaints about response times and resolution quality. Some processors offer dedicated account managers only at higher volumes. If you're not there yet, verify whether you can escalate to someone with actual authority when things break, or whether you're stuck in a tier-one support loop that can only reset your credentials.
A Common Edge Case
Here's a scenario I ran into recently that illustrates why Payment Comparison needs to go beyond published rates. A client was processing a mix of domestic and international cards with roughly sixty percent of transactions coming from outside their home country. The processor they were considering had excellent domestic rates but applied a two percent foreign exchange markup on every international transaction. When I recalculated their effective rate including that markup, the provider was actually more expensive than their current one by about 0.8% overall, despite having a lower base rate on domestic transactions. The workaround was to route international transactions through a separate gateway that specialized in multi-currency processing. This meant maintaining two accounts, which added operational overhead, but the cost savings justified it at their transaction volume. The lesson here is that you need to model your actual transaction mix against each provider's pricing structure, not just compare headline rates.

When Payment Comparison Fails Completely
There are situations where doing a detailed comparison is a waste of time. If you're a small business doing under ten thousand dollars per month in transactions, the differences between major processors will amount to maybe fifty dollars per month at most. The time you spend evaluating providers will cost you more than the savings you'd find. In those cases, just pick the one with the simplest onboarding and strongest documentation, and don't look back until your volume justifies the effort. Similarly, if you're in a high-risk industry like adult entertainment, gambling, or CBD, most mainstream processors simply won't touch you. Your comparison shrinks to whoever will accept your business, and pricing becomes secondary to approval odds. Factor that in early so you don't waste time researching providers that will reject your application anyway. The thing about Payment Comparison is that it's only as good as the data you feed into it. Get the numbers right, account for the hidden costs, and factor in your actual operational needs, and you'll save money. Do it poorly, and you'll end up somewhere worse than where you started, which happens more often than people admit.