Starting With the Calculations Instead of the Theory
Most people learn the formula first, memorize it, and then try to make sense of what it actually means. That approach works until you hit a problem where the compounding frequency isn't annual, or the payments aren't even, or you're solving for a rate that won't converge on the first five tries. I stopped doing it that way years ago. Now I work backward from what the problem is actually asking, figure out which variables are known and which are missing, and only then decide whether to reach for the formula or just let Excel do the heavy lifting. The time value of money concept is straightforward once you've seen enough variations. A dollar today is worth more than a dollar tomorrow because you can invest it and earn something. That's it. Everything else is just mechanics. But the mechanics get complicated fast, especially when practice problems start mixing in annuities due, perpetuities, uneven cash flows, and rates that need to be converted between periods.
Working Through Time Value Of Money Practice Problems
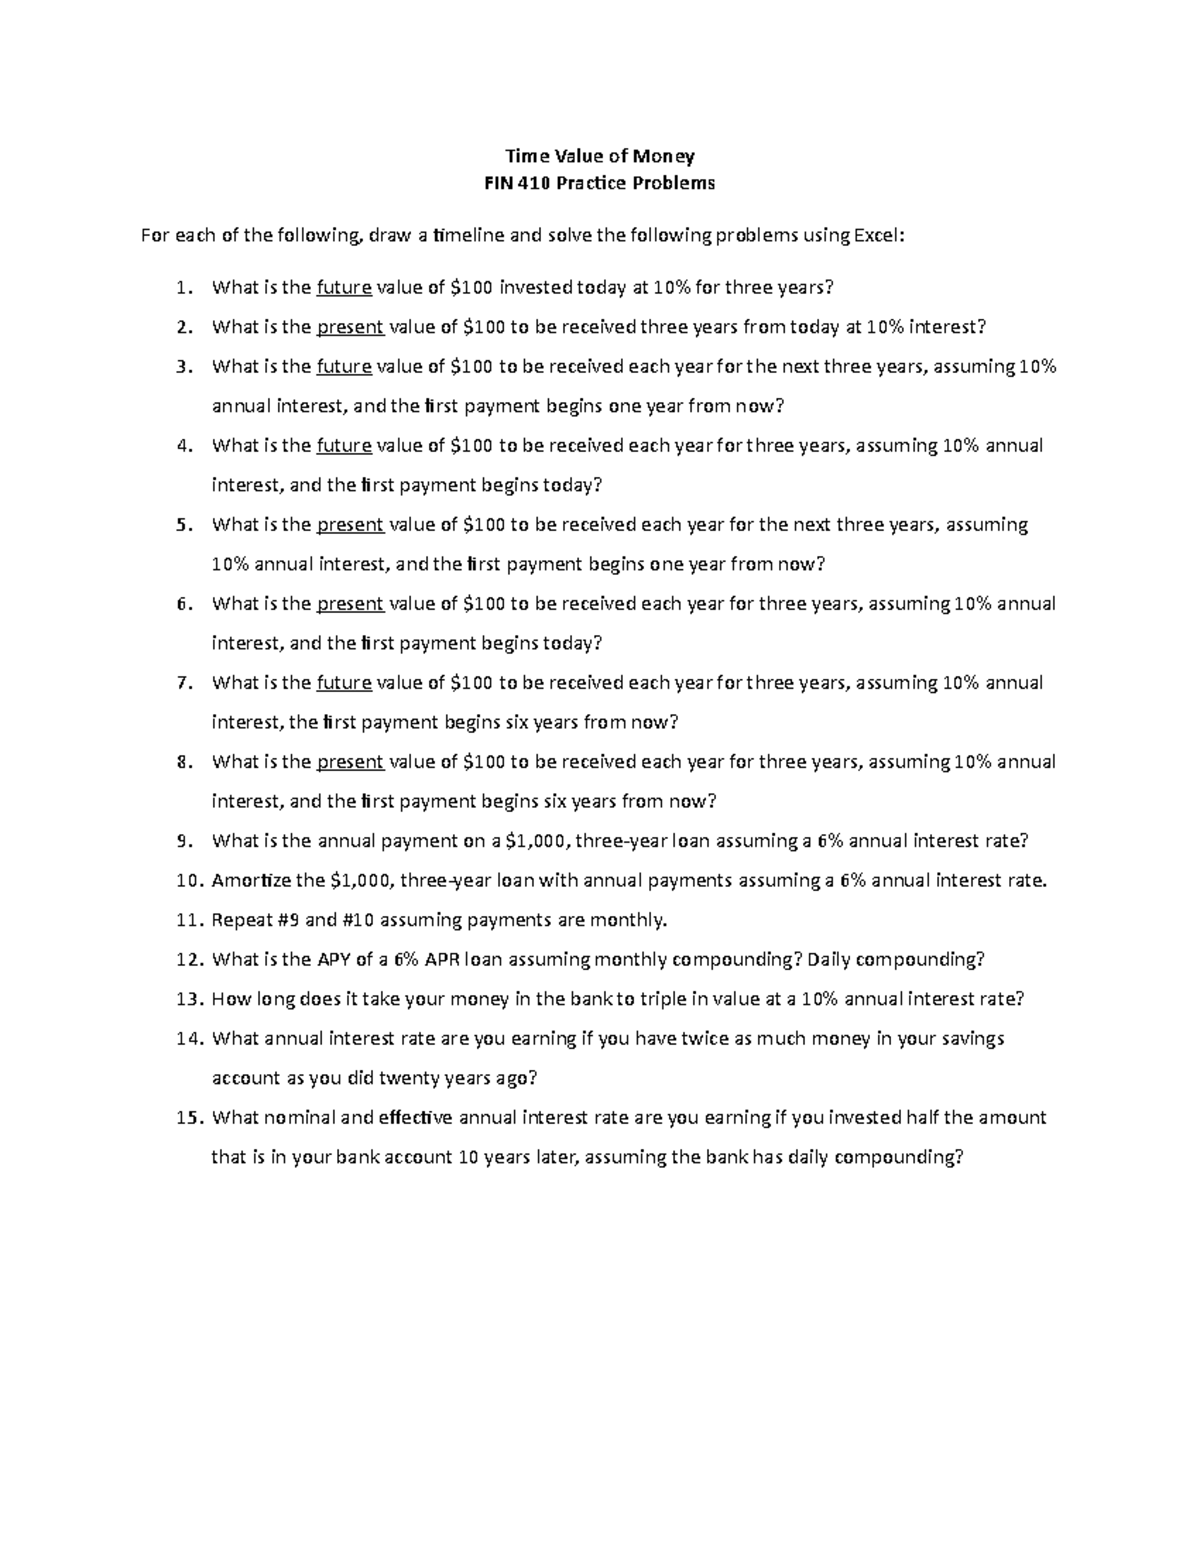
Here's how I actually approach a set of TVM practice problems, the way I do it when I'm grading student work or checking my own understanding before an exam. Step one is always identifying the cash flow type. Is it a single lump sum? An ordinary annuity where payments happen at period end? An annuity due where payments come at the beginning? Uneven cash flows that require individual discounting? Getting this wrong at the start wastes more time than any calculation error later. I've watched people lose points on exams not because they couldn't compute present value, but because they used the ordinary annuity formula on an annuity due problem without adjusting for the extra period of compounding. Step two is locking down the compounding period and the payment period. They don't always match. A common problem format gives you an annual percentage rate but monthly compounding with quarterly payments. You need the effective periodic rate, not the nominal rate. Divide the annual rate by the number of compounding periods per year to get your periodic rate. If the payment frequency differs from the compounding frequency, you need to convert. The formula for that is (1 + r/n)^(n/m) - 1, where r is the annual rate, n is compounding periods per year, and m is payment periods per year. This trips people up constantly.
Step three is setting up the timeline. Draw it out. Put the known cash flows on a number line, mark the periods, and clearly label when each payment or receipt occurs. This sounds silly for simple problems, but when you're dealing with deferred annuities or cash flows that start three years from now, a visual timeline prevents you from off-by-one errors that are brutal to catch afterward. I still do this even for problems I could solve in my head. It takes ten seconds and it saves me from the kind of mistake that costs fifteen minutes of debugging. Let me walk through a concrete example. Say you're given this: Find the present value of receiving $500 at the end of each quarter for five years, with an annual interest rate of 8% compounded quarterly. First, cash flow type: ordinary annuity, since payments are at period end. Second, periodic rate: 8% divided by 4 quarters equals 2% per quarter. Number of periods: 5 years times 4 quarters equals 20 periods. Third, timeline: twenty quarterly payments stretching from period 1 to period 20.
Get the Full Details
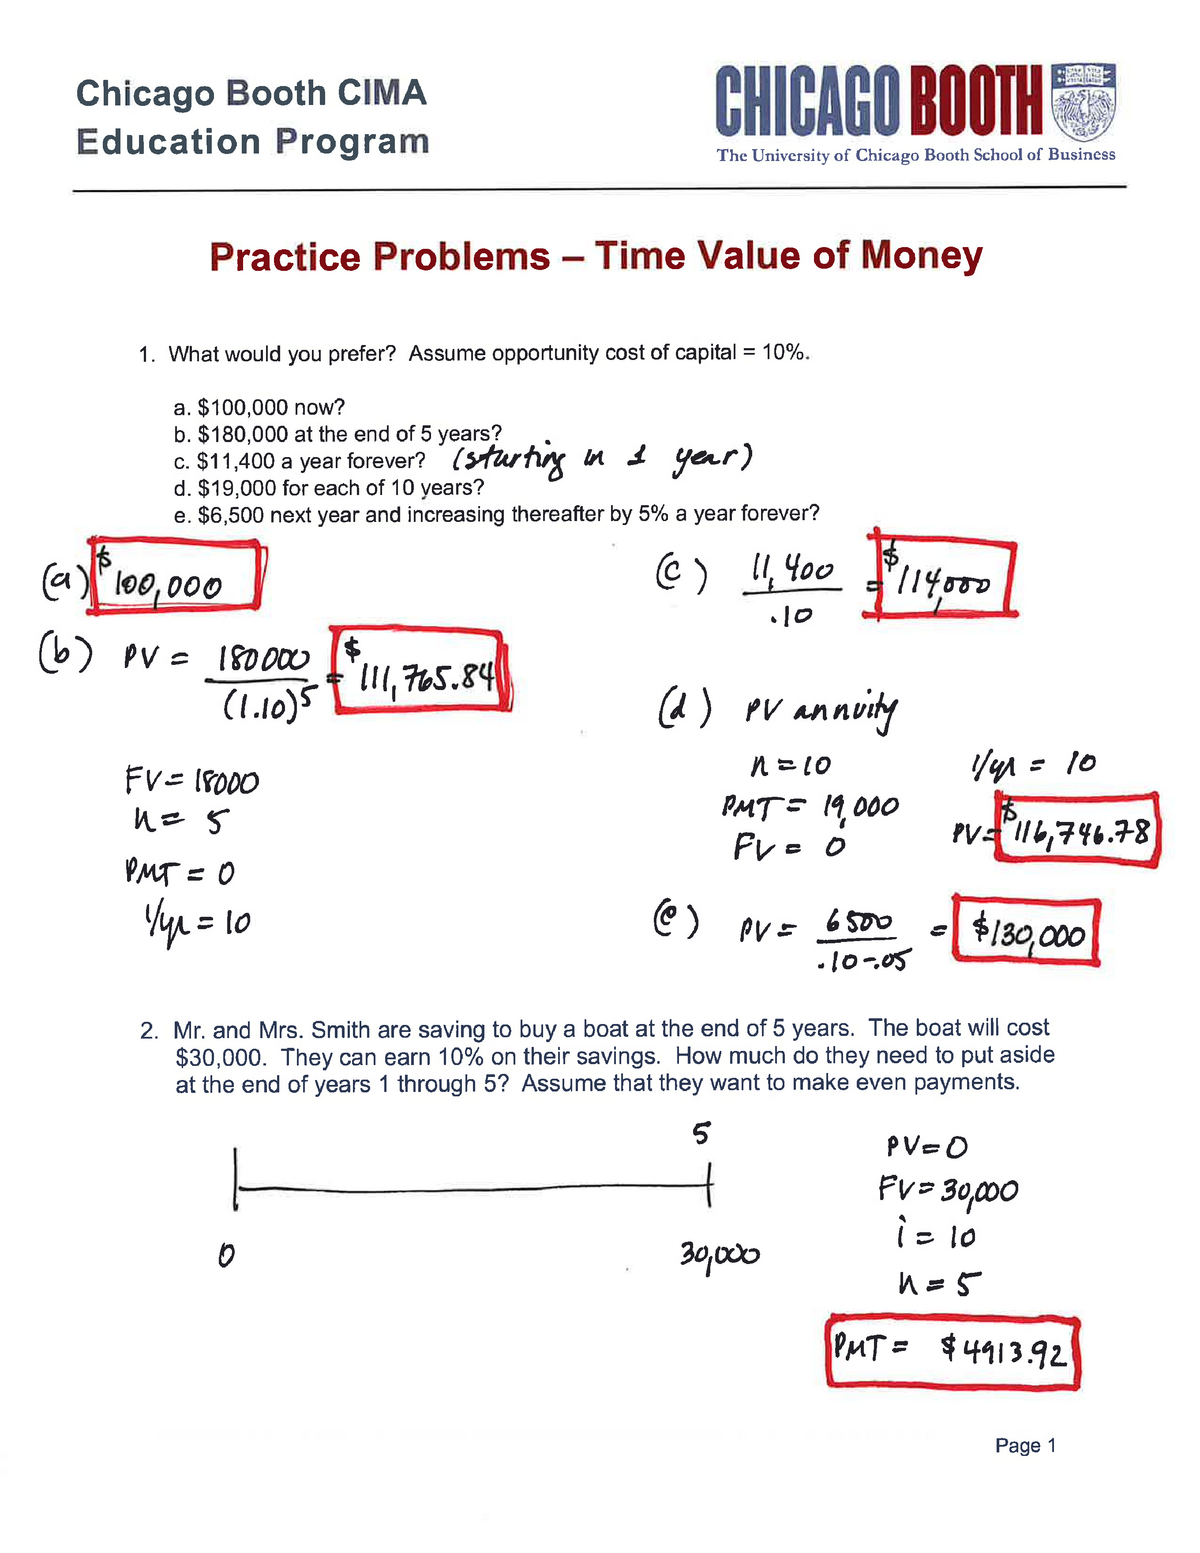
The present value of an ordinary annuity formula is PV = PMT × [1 - (1 + r)^-n] / r. Plugging in: PV = 500 × [1 - (1.02)^-20] / 0.02. Working through the exponent first: 1.02 to the negative 20th power comes out to approximately 0.67297. Subtract that from 1 to get 0.32703. Divide by 0.02 to get 16.3515. Multiply by 500 and the present value is roughly $8,175.77. Check your answer makes sense. You're receiving a total of $10,000 over five years in nominal dollars. Discounting at 8% should bring that well below ten thousand. Eighteen hundred discounting across twenty periods at 2% per period feels right. Now the thing most practice problem sets don't emphasize enough: solving for the rate or the number of periods is where TVM problems actually get interesting. These don't have clean algebraic solutions. You solve them iteratively or with a financial calculator's built-in functions. The NPER and RATE functions in Excel handle this, but understanding what's happening under the hood matters. When you use the RATE function and it returns something unexpected, knowing whether the issue is a sign convention problem, a convergence failure, or a genuinely impossible combination of inputs will save you from copying someone else's wrong answer.
I ran into a specific edge case recently that illustrates this. A student was working on a problem involving a perpetuity with growth, where the first payment was $1,000 one year from now, growing at 3% annually, and the discount rate was 7%. The formula is straightforward: PV = C / (r - g), which gives 1,000 / (0.07 - 0.03) = $25,000. But then the problem added a twist: the first payment was delayed by two years instead of one. The instinctive response is to discount the $25,000 back two periods. That's wrong. The standard perpetuity formula assumes the first payment comes one period from now. If it comes two periods from now, you discount the result back one additional period, not two. The answer is 25,000 / 1.07, which is approximately $23,364.49. Students who discounted by two periods got $21,835.98 and couldn't figure out why their answer was marked wrong. The perpetuity formula already embeds a one-period delay, so the additional delay is only one period, not two. Another common pitfall involves mixed cash flows. You'll get problems where there's a base annuity and then extra irregular payments layered on top. The approach is to split it into separate components, value each one individually, and sum them. Don't try to force a single formula onto a messy cash flow stream. It won't work and you'll end up with garbage results that look plausible enough to be dangerous. Here's a practical set of practice problems with increasing difficulty, the kind I'd assign if I were running a review session:
Problem 1: What is the future value of $10,000 invested today at 6% annual interest compounded annually for 10 years? This is a basic lump sum FV problem. FV = 10,000 × (1.06)^10 = $17,908.48. Problem 2: You want to have $50,000 in eight years. How much must you invest today at 5% compounded semi-annually? Rearranging the PV formula: PV = 50,000 / (1.025)^16 = $34,074.57. Note the semi-annual rate is 2.5% and there are 16 periods. Problem 3: An ordinary annuity pays $2,000 at the end of each year for 15 years at a discount rate of 9%. What is its present value? PV = 2,000 × [1 - (1.09)^-15] / 0.09 = $17,184.63.
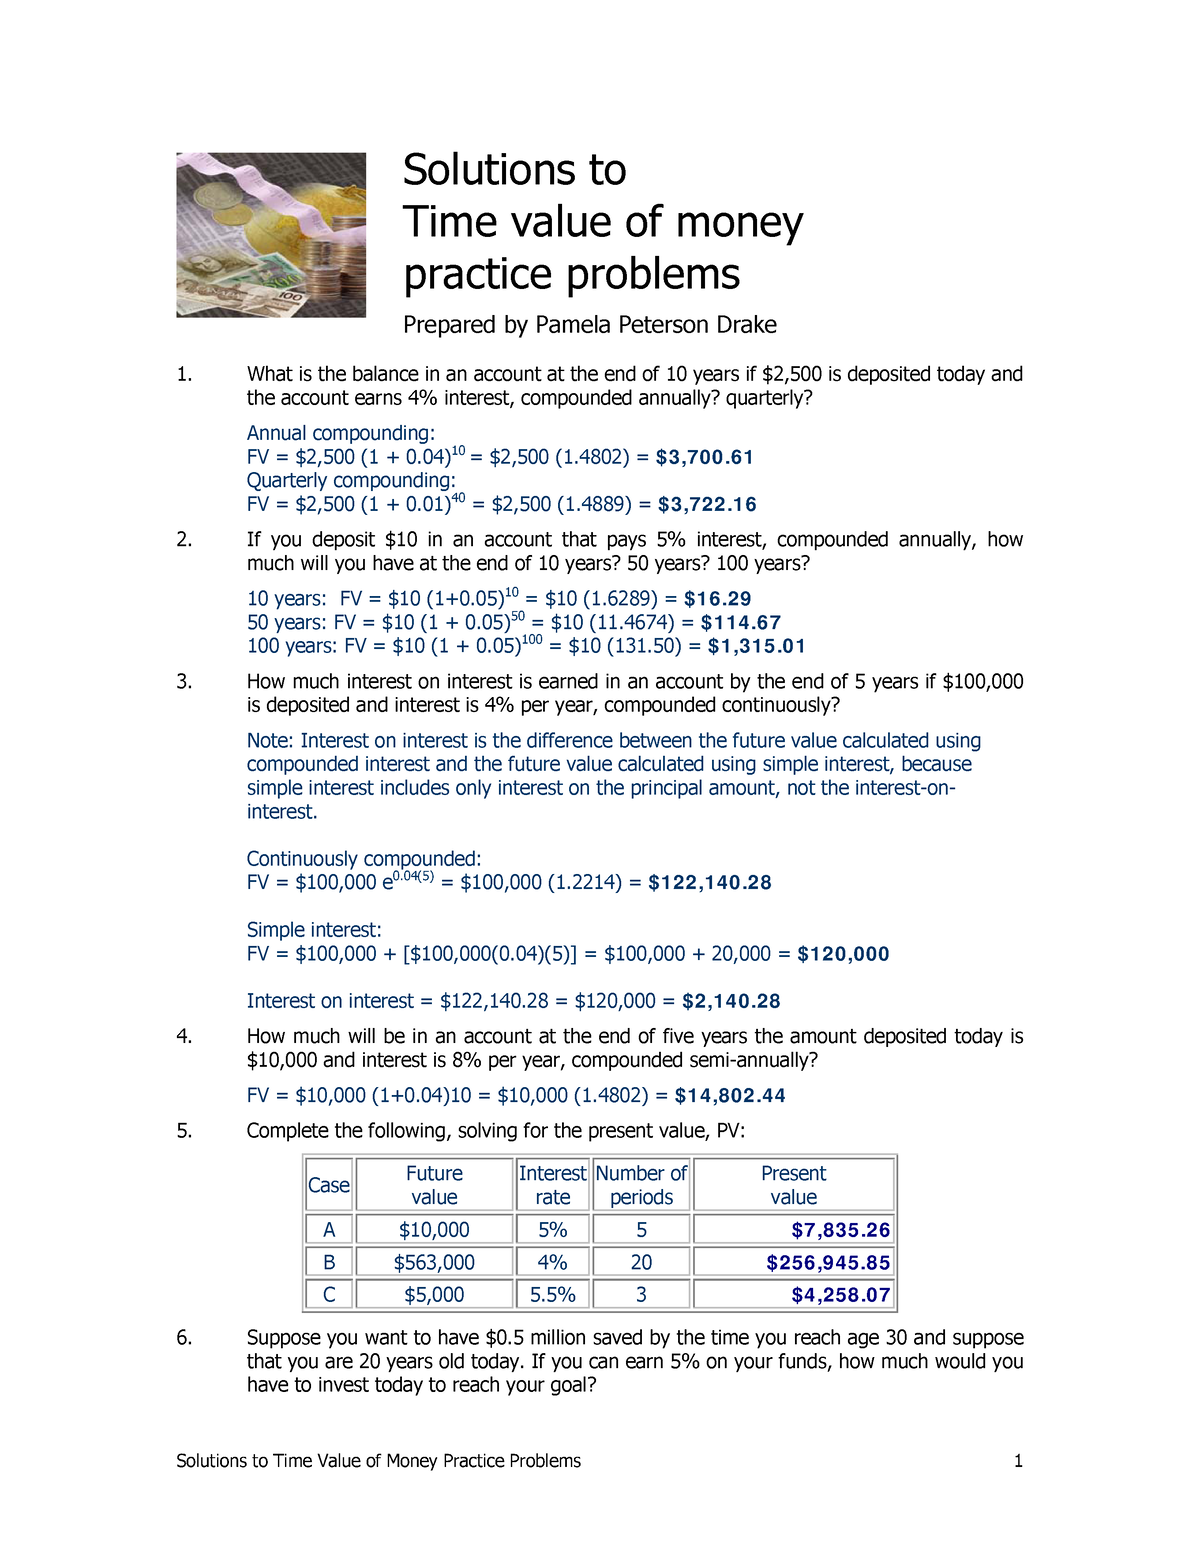
Problem 4: Same as Problem 3, but payments are at the beginning of each year (annuity due). Multiply the ordinary annuity result by (1 + r): 17,184.63 × 1.09 = $18,731.25. The annuity due is always worth more because each payment earns interest for one additional period. Problem 5: You borrow $25,000 at 7% annual interest and will repay it in equal annual payments over ten years. What is your annual payment? This is solving for PMT. Using the annuity payment formula: PMT = PV × r / [1 - (1 + r)^-n] = 25,000 × 0.07 / [1 - (1.07)^-10] = $3,619.30 per year. Problem 6: An investment costs $100,000 today and returns $30,000 at the end of each year for five years, $40,000 in year six, and $50,000 in year seven. The discount rate is 10%. What is the NPV? This requires discounting each cash flow individually. PV of years 1-5: 30,000 × [1 - (1.10)^-5] / 0.10 = $113,723.61. PV of year 6: 40,000 / (1.10)^6 = $22,599.21. PV of year 7: 50,000 / (1.10)^7 = $25,667.43. Total PV = $161,990.25. NPV = $161,990.25 - $100,000 = $61,990.25.
Problem 7: What annual rate of return is required to grow $5,000 to $25,000 in twelve years? Solving for r: r = (25,000 / 5,000)^(1/12) - 1 = 14.35%. This requires either a financial calculator's I/Y function or trial and error with the FV formula. Problem 8: A perpetuity pays $500 every year forever. What is its present value at a 6% discount rate? PV = 500 / 0.06 = $8,333.33. Simple, but remember this only works when payments never change and never stop. Problem 9: A perpetuity with growth pays $1,000 next year, with payments growing at 4% annually. The discount rate is 9%. PV = 1,000 / (0.09 - 0.04) = $20,000. The growth rate must be less than the discount rate or the formula breaks down entirely. If g equals or exceeds r, the present value is undefined or infinite, which is a practical reminder that not every combination of inputs produces a meaningful answer.
Problem 10: You're comparing two annuities. Annuity A pays $1,200 at the end of each month for ten years. Annuity B pays $14,000 at the end of each year for ten years. Both have a 6% annual discount rate compounded monthly. Which has the higher present value? For annuity A, the monthly rate is 0.5% and there are 120 periods: PV = 1,200 × [1 - (1.005)^-120] / 0.005 = $98,782.53. For annuity B, you first need the effective annual rate: (1.005)^12 - 1 = 6.17%. Then PV = 14,000 × [1 - (1.0617)^-10] / 0.0617 = $100,425.18. Annuity B wins despite the smaller total nominal payout because the effective discount rate is higher, making the larger annual payments relatively more valuable. This is counter-intuitive for most students who assume more frequent payments automatically means more value. A few things I want to stress that practice problem sets rarely highlight. Sign convention matters in calculators and spreadsheets. If you enter PV as a positive number, PMT and FV should be negative, or vice versa. Mixing signs is the single most common reason people get wrong answers on financial calculators. Always verify your periodic rate matches your period count. If you're using monthly periods, your rate must be monthly and your N must be months. Using an annual rate with monthly periods is a mistake I see in literally every batch of student work. There are limits to what TVM analysis can tell you. It assumes a constant discount rate, which is almost never true in practice. It doesn't account for inflation unless you explicitly use a real rate. It treats cash flows as certain when they often aren't. For long-horizon problems, a small change in the discount rate produces enormous changes in present value. A 1% difference in rate can swing a twenty-year valuation by 20% or more. That's not a flaw in the method, it's a feature you need to acknowledge. Sensitivity analysis on the discount rate is usually more useful than a single point estimate.

If you're working through practice problems and hitting wall after wall, the issue is rarely the math. It's usually that you're skipping the setup steps. Identify the cash flow type, convert your rates to match your periods, draw the timeline, then calculate. In that order. Doing it in any other order is just creating extra work for yourself.