What Would Happen If The Irs Was Abolished
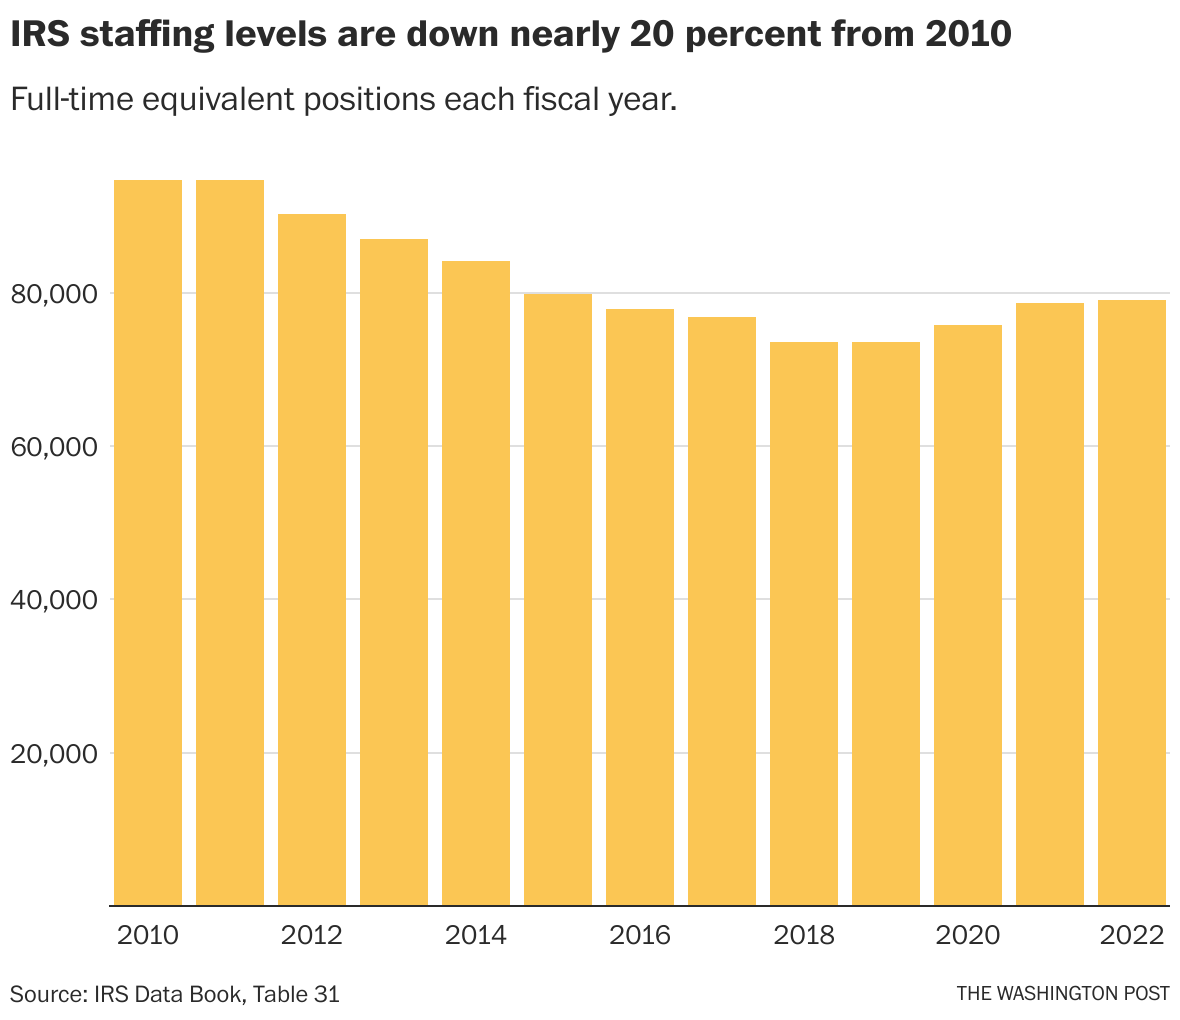
The United States federal government collects roughly $4.9 trillion a year in revenue. That money pays for everything from highway construction to Social Security to the military budget. The agency responsible for collecting most of that is the Internal Revenue Service, with about 80,000 employees and an annual operating budget of around $14 billion. If you remove the IRS tomorrow, you don't remove the need for revenue. You just remove the mechanism for collecting it. I've spent twenty years working in tax policy and public finance, mostly on the state level but with enough federal interaction to know how the machinery actually functions day to day. Let me walk through what would realistically happen, not what advocates on either side claim would happen. The first thing to understand is that the IRS is not the tax system. It's the collection and enforcement arm of it. Congress writes tax law. The Treasury Department sets broad policy. The IRS does the actual work of processing 160 million individual returns, auditing businesses, collecting delinquent accounts, and running the earned income credit and child tax credit distribution programs. Abolishing the IRS means redistributing those functions somewhere else or eliminating them entirely.
There are three general categories of replacement models people propose. The first is a consumption tax swap, typically a national VAT or fair tax model. The second is a flat tax or simplified filing system administered through a different agency. The third is devolving revenue collection to the states or relying on existing infrastructure like W-2 reporting without centralized enforcement. Each has very different operational consequences. With a VAT system, you eliminate individual income tax filing for most people. That sounds appealing until you account for the fact that the United States has no nationwide point-of-sale value-added tax infrastructure. Implementing one would require building an entirely new collection apparatus from scratch, similar in many ways to what the IRS currently is but focused on business-to-business transactions rather than individual returns. The transition period alone would take five to seven years minimum based on how long it took other countries with existing frameworks to implement theirs. Canada took nearly a decade. A flat tax at something like 17 percent with no deductions would dramatically simplify the form itself. But simplification is not the same as elimination of enforcement. You still need people verifying that reported income matches actual income, that W-2s correspond to real employers, that pass-through entities aren't inflating losses. The audit function doesn't disappear just because the rate schedule is simpler. You'd likely see a smaller agency, maybe 20,000 to 30,000 staff, handling a narrower scope of collection and compliance.
The third option, shifting to states, is where things get genuinely complicated. Several states already have income taxes with their own revenue departments. But state tax systems are fragmented by design. They differ in brackets, deductions, filing thresholds, and enforcement priorities. A business operating in fifteen states currently deals with fifteen different compliance regimes. If the federal government disappeared and states absorbed new revenue responsibilities, you'd either have states negotiating uniform collection standards — which is politically nearly impossible given state-level competition for economic activity — or you'd create a patchwork that makes interstate commerce significantly more burdensome than it already is. I worked on a project back in 2016 analyzing what happens when a mid-size manufacturing company with operations in eight states faces simultaneous audits by multiple state revenue departments. We're talking about 18 months of internal staff time, external consultant fees around $200,000, and inconsistent rulings across jurisdictions on the same transaction. Multiply that by the addition of new federal-level revenue collection layered on top of existing state systems and you get an administrative cost increase that probably exceeds the savings from abolishing the IRS. That's not theoretical. It's what happens when you fragment a unified collection system without a coherent replacement framework. There's also the issue of what the IRS currently does that doesn't get enough attention. The agency operates the Identity Protection PIN program, which assigns 6-digit codes to victims of tax identity theft to prevent fraudulent filings. It runs the Volunteer Income Tax Assistance program that provides free filing help to low-income taxpayers. It processes Amnerican Rescue Plan stimulus payments and CARES Act economic impact payments. It administers the Child Tax Credit quarterly payments that started in 2021. These aren't luxuries. They're infrastructure that serves millions of people and would need an alternative operator if the IRS were dissolved.
Get the Full Details
On the revenue side, the Congressional Budget Office has estimated that abolishing the individual income tax and replacing it with alternative revenue sources would require either a dramatically higher consumption tax rate or significant borrowing. A VAT sufficient to replace federal income tax revenue would need to run somewhere in the 23 to 30 percent range depending on exclusions and design choices. That's higher than Germany's 19 percent and well above what any serious American political coalition would propose in the near term. The flat tax advocates argue for rates around 17 percent, but that math only works if you accept the revenue loss from eliminating most deductions and credits, which creates either a deficit increase or requires finding replacement revenue from other sources. The political reality is that even if Congress passed legislation abolishing the IRS, the practical implementation would encounter immediate legal and administrative hurdles. The 16th Amendment authorizes Congress to lay and collect taxes on incomes. Removing the IRS doesn't remove the constitutional authority or the statutory obligations. Courts would likely be asked to rule on transition questions involving pending litigation, accrued penalties, and ongoing audit cases. The Government Accountability Office projects that full wind-down of a major federal agency like the IRS would take three to four years minimum, during which time tax collection would operate under some form of interim arrangement. Here's something most people don't consider: the IRS has significant data cross-matching capabilities that serve as a compliance backstop. When your employer reports wages on a W-2, the IRS matches it against your individual return. When a bank reports interest income on a 1099-INT, it's flagged against your filing. This matching system alone prevents an estimated 3 to 5 percent in unrecovered revenue annually. Without a centralized matching engine, that gap wouldn't just vanish. It would become a structural feature of whatever replacement system emerged, and the revenue loss would accumulate over time through underreporting that goes undetected.
I've seen this play out on a smaller scale with state-level changes. When my state temporarily reduced audit staffing due to budget constraints, we saw a measurable increase in non-filers and underreporters within two tax cycles. Compliance doesn't require perfect enforcement. It requires credible enforcement. Remove the credibility and the voluntary compliance rate drops, which means you need either higher rates on those who do comply or new administrative machinery to close the gap — both of which defeat the original purpose of the abolition. The bottom line is that abolishing the IRS is straightforward as a slogan and enormously complex as a policy action. The revenue needs of the federal government don't disappear. The collection and enforcement functions need to go somewhere. The transition costs are measured in billions and years, not months. And the people most likely to bear the burden of implementation friction are taxpayers who simply want to file their returns and move on with their lives.