So you want to automate your trading. Let's talk about what actually happens.
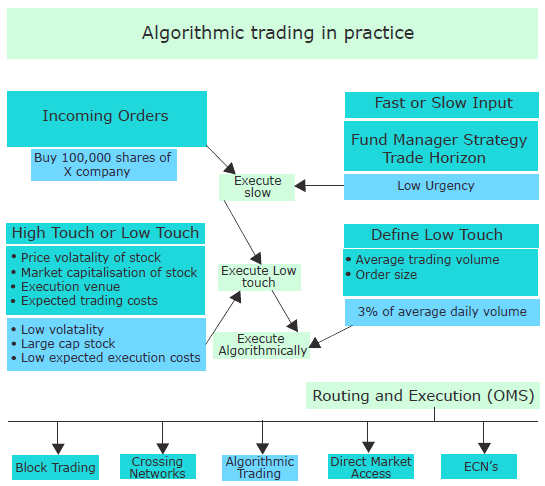
I first tried algo trading back in 2015 because I was tired of staring at charts during my day job and missing entries. I wrote a simple moving average crossover bot in Python using Interactive Brokers' API. It lost money for three weeks straight before I figured out the real problem wasn't the strategy, it was slippage. The spreads alone ate a full percentage point off my returns on illiquid small-caps. That's the thing nobody tells you upfront: the math on paper and the math in a live market are two different animals. At its most basic level, algorithmic trading means replacing manual decision-making with code that automatically enters and exits positions based on predefined rules. You're not trying to outsmart the market. You're removing your own biases and emotional fatigue from the loop. A basic bot might check every 30 seconds whether a stock has crossed above its 50-day moving average and place a market order if it has. That's it. The complexity comes from how you handle everything else: order routing, position sizing, error recovery, and the fact that your own orders can move the market against you. The main categories people run into are market-making bots, statistical arbitrage systems, trend-following engines, and execution algorithms designed to minimize slippage on large orders. Most retail traders end up in the execution or simple trend-following bucket because the other two require infrastructure and capital that institutional players already dominate.
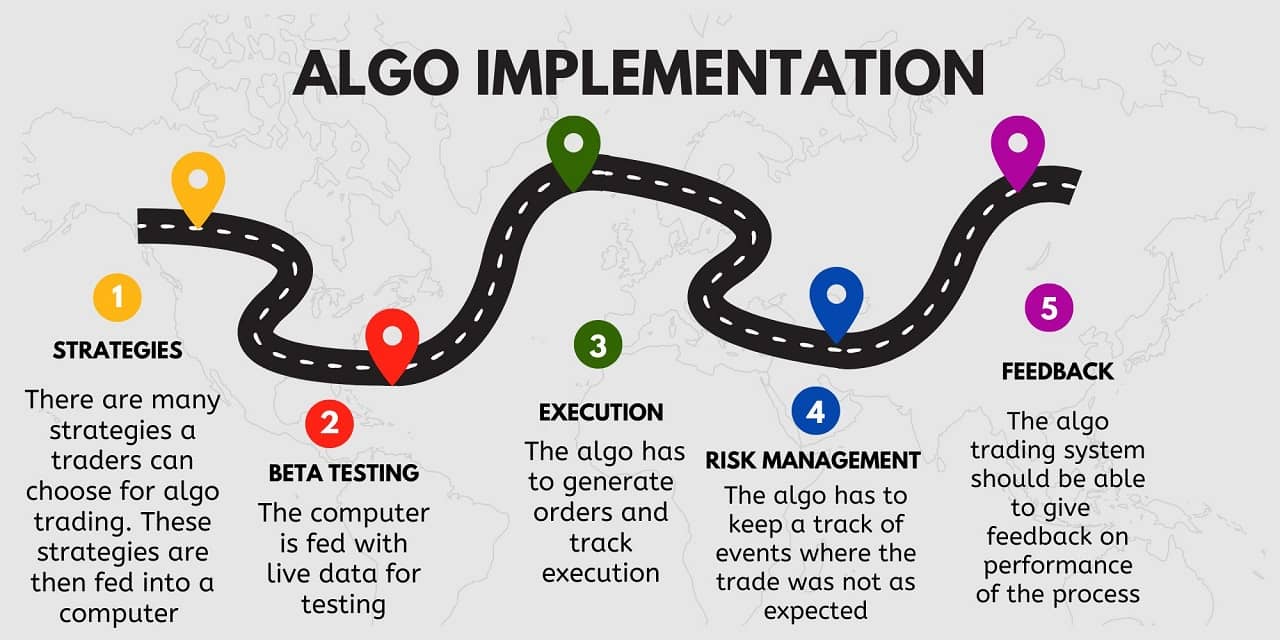
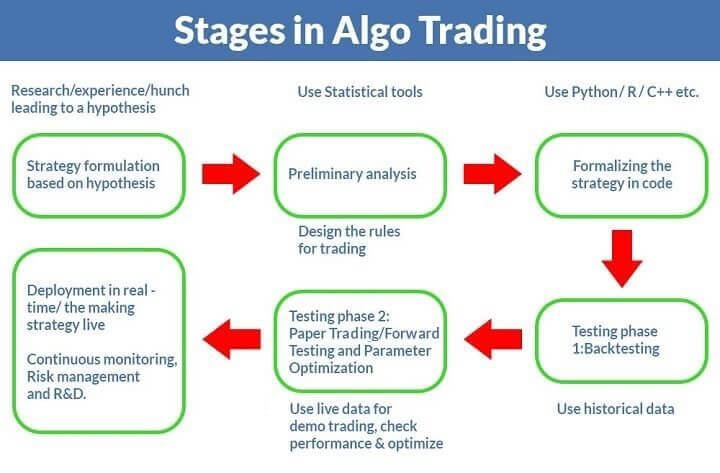
I've seen people build full backtesting pipelines with tick-level data, but here's the counter-intuitive part: the fancy backtests usually lie. They assume you fill at the exact close of a candle, they ignore latency, and they never account for the fact that by the time your signal fires, fifty thousand other algos have already traded on it. I learned this the hard way when I backtested a mean-reversion strategy on the ES futures and got a 40 percent Sharpe ratio. Live, it blew up in two days. The reversion signals were just capturing noise between algorithmic liquidity providers, not actual price inefficiencies. The practical workflow, assuming you're starting from zero, looks roughly like this. First, pick a market and a data source. Binance or Bybit for crypto, Interactive Brokers or TD Ameritrade for US equities, and download historical data from Yahoo Finance or Alpha Vantage for a first pass. Then write a backtest in Python using something like Backtrader or vectorbt. Don't overcomplicate the initial version. One entry rule, one exit rule, fixed position size. Run it against at least two years of data including a volatile period. If the strategy only works in calm markets, it's not a strategy, it's a coincidence. Once your backtest shows anything remotely reasonable, move to paper trading. Connect your bot to a broker's sandbox environment and run it for at least three weeks. I skip this step once and spent four hours debugging why my orders weren't submitting, only to realize the paper trading API had a different rate limit than the live one. Your live environment will have worse latency, stricter rate limits, and slightly different price feeds than your backtest. Expect a 15 to 30 percent degradation in performance versus your backtested results as a baseline.
For the actual bot code, I keep it modular. Separate the data fetcher, the signal engine, the order manager, and the risk checker into distinct classes. A crash in one shouldn't take down the whole system. Use asyncio for concurrent operations instead of threading, because a threaded bot that deadlocks during a volatile spike will still have open positions while you're frantically SSHing into your server to kill the process. Something I learned after a 2 AM incident where my bot kept doubling down on a losing position because the error handler had a logic bug that retried failed orders instead of flagging them for manual review. Here's a realistic problem I ran into that most tutorials won't mention: partial fills and order state reconciliation. Let's say your bot sends a limit order at 49.50 for 100 shares. The exchange partially fills 60 shares and cancels the rest. Your bot doesn't know that immediately. Five minutes later it sends another order at 49.45. Now you're accidentally doubling your exposure. I solved this by implementing an order tracking table that logs every submitted order with a unique ID, and a reconciliation function that queries the broker every 30 seconds to match open orders against my internal state. If there's a mismatch, the bot pauses and alerts me. This adds maybe 10 minutes of development time but prevents the kind of catastrophic over-leveraging that can wipe out an account in a single session. A few things that are worth knowing before you start. Transaction costs matter way more than most people expect. A strategy with a 60 percent win rate but five trades per day on a $5,000 account will lose money if each trade costs $1.25 in fees and slippage. Run your numbers with at least $0.50 per round trip for crypto and $0.005 per share for equities. Second, overfitting is the silent killer. If your backtest has more than three adjustable parameters, you're probably curve-fitting noise. The moment you add a new parameter, test it on out-of-sample data before declaring it an improvement. Third, broker APIs change without warning. I had a working bot on Alpaca that broke when they deprecated their v1 endpoint. Version pinning your dependencies and monitoring API changelogs is not optional.
Get the Full Details
If you're looking for a place to get started with code, the Backtrader GitHub repository is the standard open-source backtesting framework, and the QuantConnect platform offers free cloud-based backtesting with built-in data for stocks, futures, and crypto. For live trading with brokers, Alpaca has the most straightforward API for US equities and ccxt is a unified Python library that works with nearly every major crypto exchange. Neither requires a paid subscription to start. The honest takeaway is that algo trading is more about risk management and infrastructure reliability than it is about finding a secret profitable strategy. The edge comes from executing reliably, managing your drawdowns, and not blowing up because your code assumed the market would behave the way your backtest said it should. A decent bot will save you from your own mistakes. A great one just means you're making fewer mistakes, faster. That's usually enough, but it's nowhere near as exciting as the YouTube videos make it sound.